Copper Sentiment Data for Institutional Commodities Desks: How Sentiment Flagged the 2026 Supply Squeeze Early
06 Oct 2026
06 Oct 2026
Copper sentiment data from Permutable’s Asset Sentiment Indices registered tightening availability almost ten weeks before July’s return to sustained backwardation, offering an early read on a squeeze that would go on to reprice prompt delivery.
After a year in which copper warehouse stocks accumulated, availability concerns intensified and the nearby curve swung into steep backwardation, copper enters the fourth quarter with much of its advance intact. LME three-month metal stands at $14,366 a tonne, approximately 15% above its level at the end of 2025 and 36% higher than in early October last year. The rise in quarterly averages underscores how far the market has travelled: Q3 averaged $14,034 a tonne, compared with $9,849 a year earlier.
While recent consolidation has left the copper benchmark close to its early-September rally level, renewed widening in the cash premium has kept prompt availability in focus. Cash copper reached $14,430 on 5 October, lifting its premium over three-month metal from $35 to $64 a tonne in a single session. The spread remains substantially narrower than in August, although its latest movement points to continuing sensitivity around immediate delivery.
The inventory chronology traced by Permutable’s Asset Sentiment Indices reveals how that sensitivity developed while the visible stockpile still appeared substantial. Total LME stocks rose from approximately 147,000 tonnes at the start of January to 403,000 tonnes on 15 April. When inventory sentiment crossed above its trailing-year norm on 13 May, stocks remained close to their April peak and cash copper traded at a $43 discount to three-month metal.
Almost ten weeks separated that sentiment turn from the curve’s return to sustained backwardation on 20 July, before stocks reached roughly 205,000 tonnes in mid-August, 49% below their April peak. Availability coverage had become more bullish during the early drawdown, well before the summer’s delivery pressure found pronounced expression in the nearby spread (Chart 1).
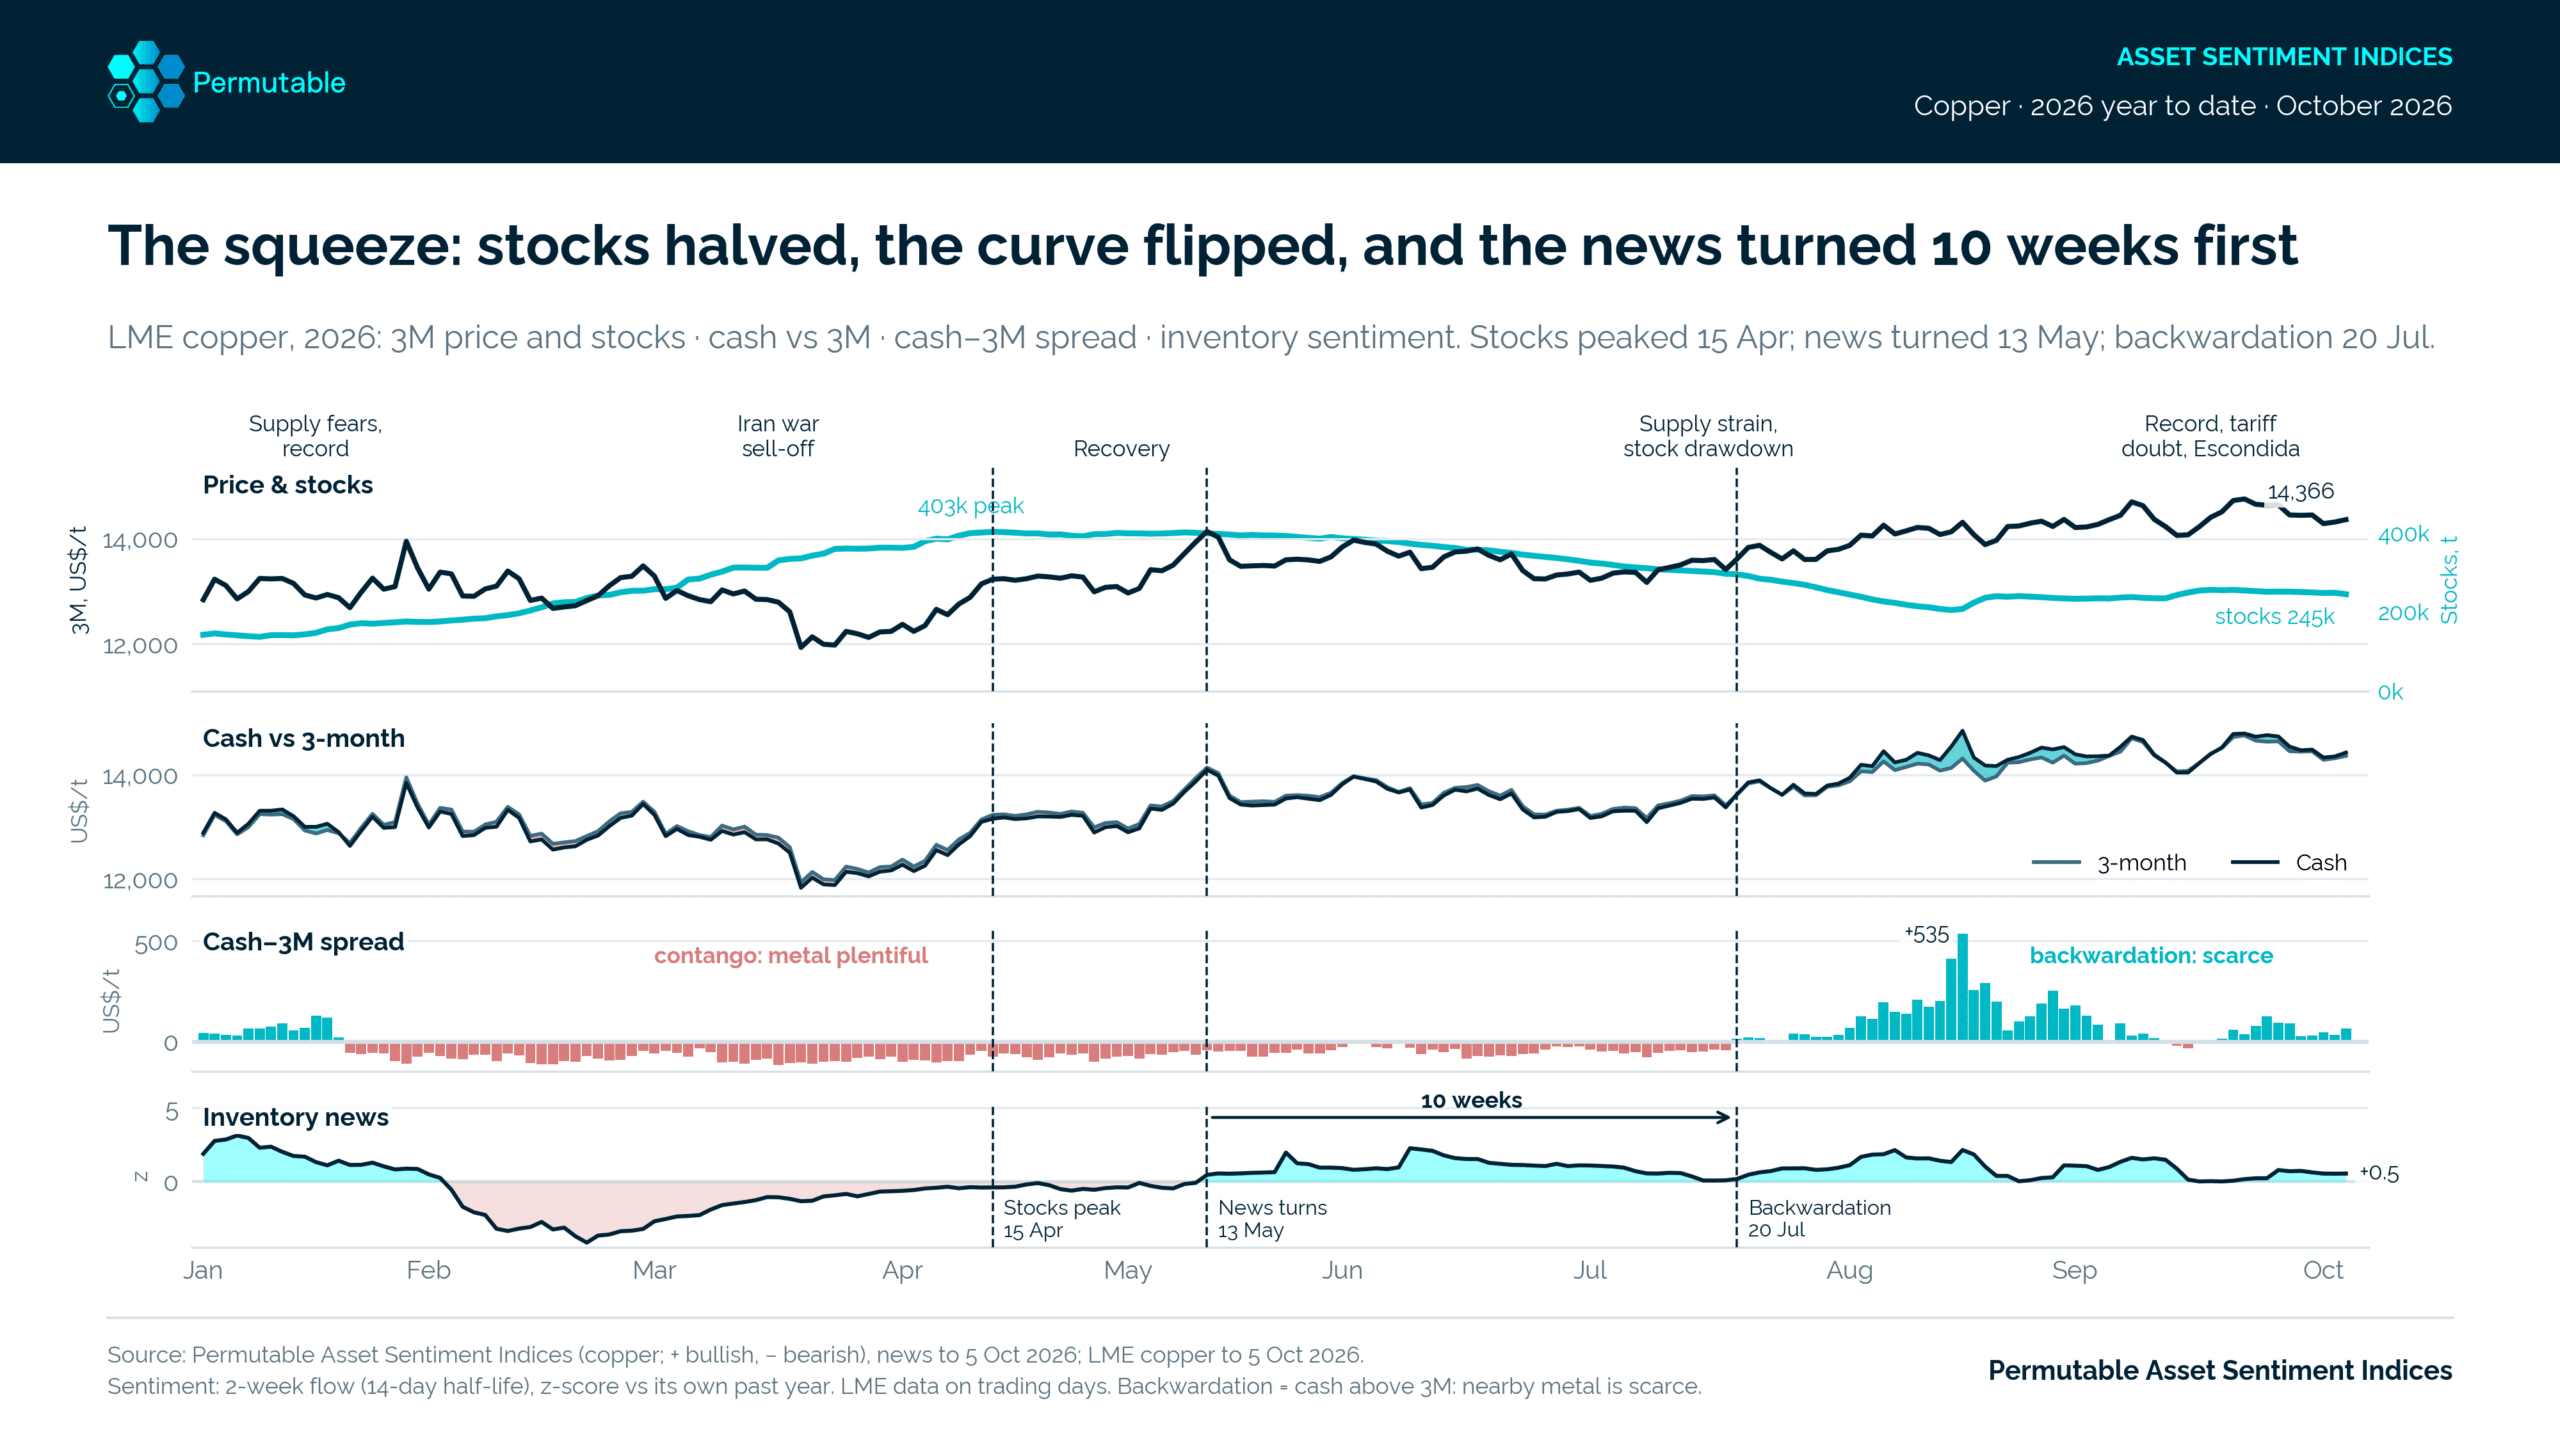
Over the summer months, the premium for obtaining copper promptly increased sharply. Cash metal traded at an average discount of about $82 a tonne during February–April, then commanded an average premium of approximately $198 in August, reaching $535 on 17 August. Read alongside the inventory series, the sequence suggests that deteriorating availability deserved attention even while warehouse holdings remained large; the changing news flow supplied information about the developing pressure that the stock level alone could obscure.
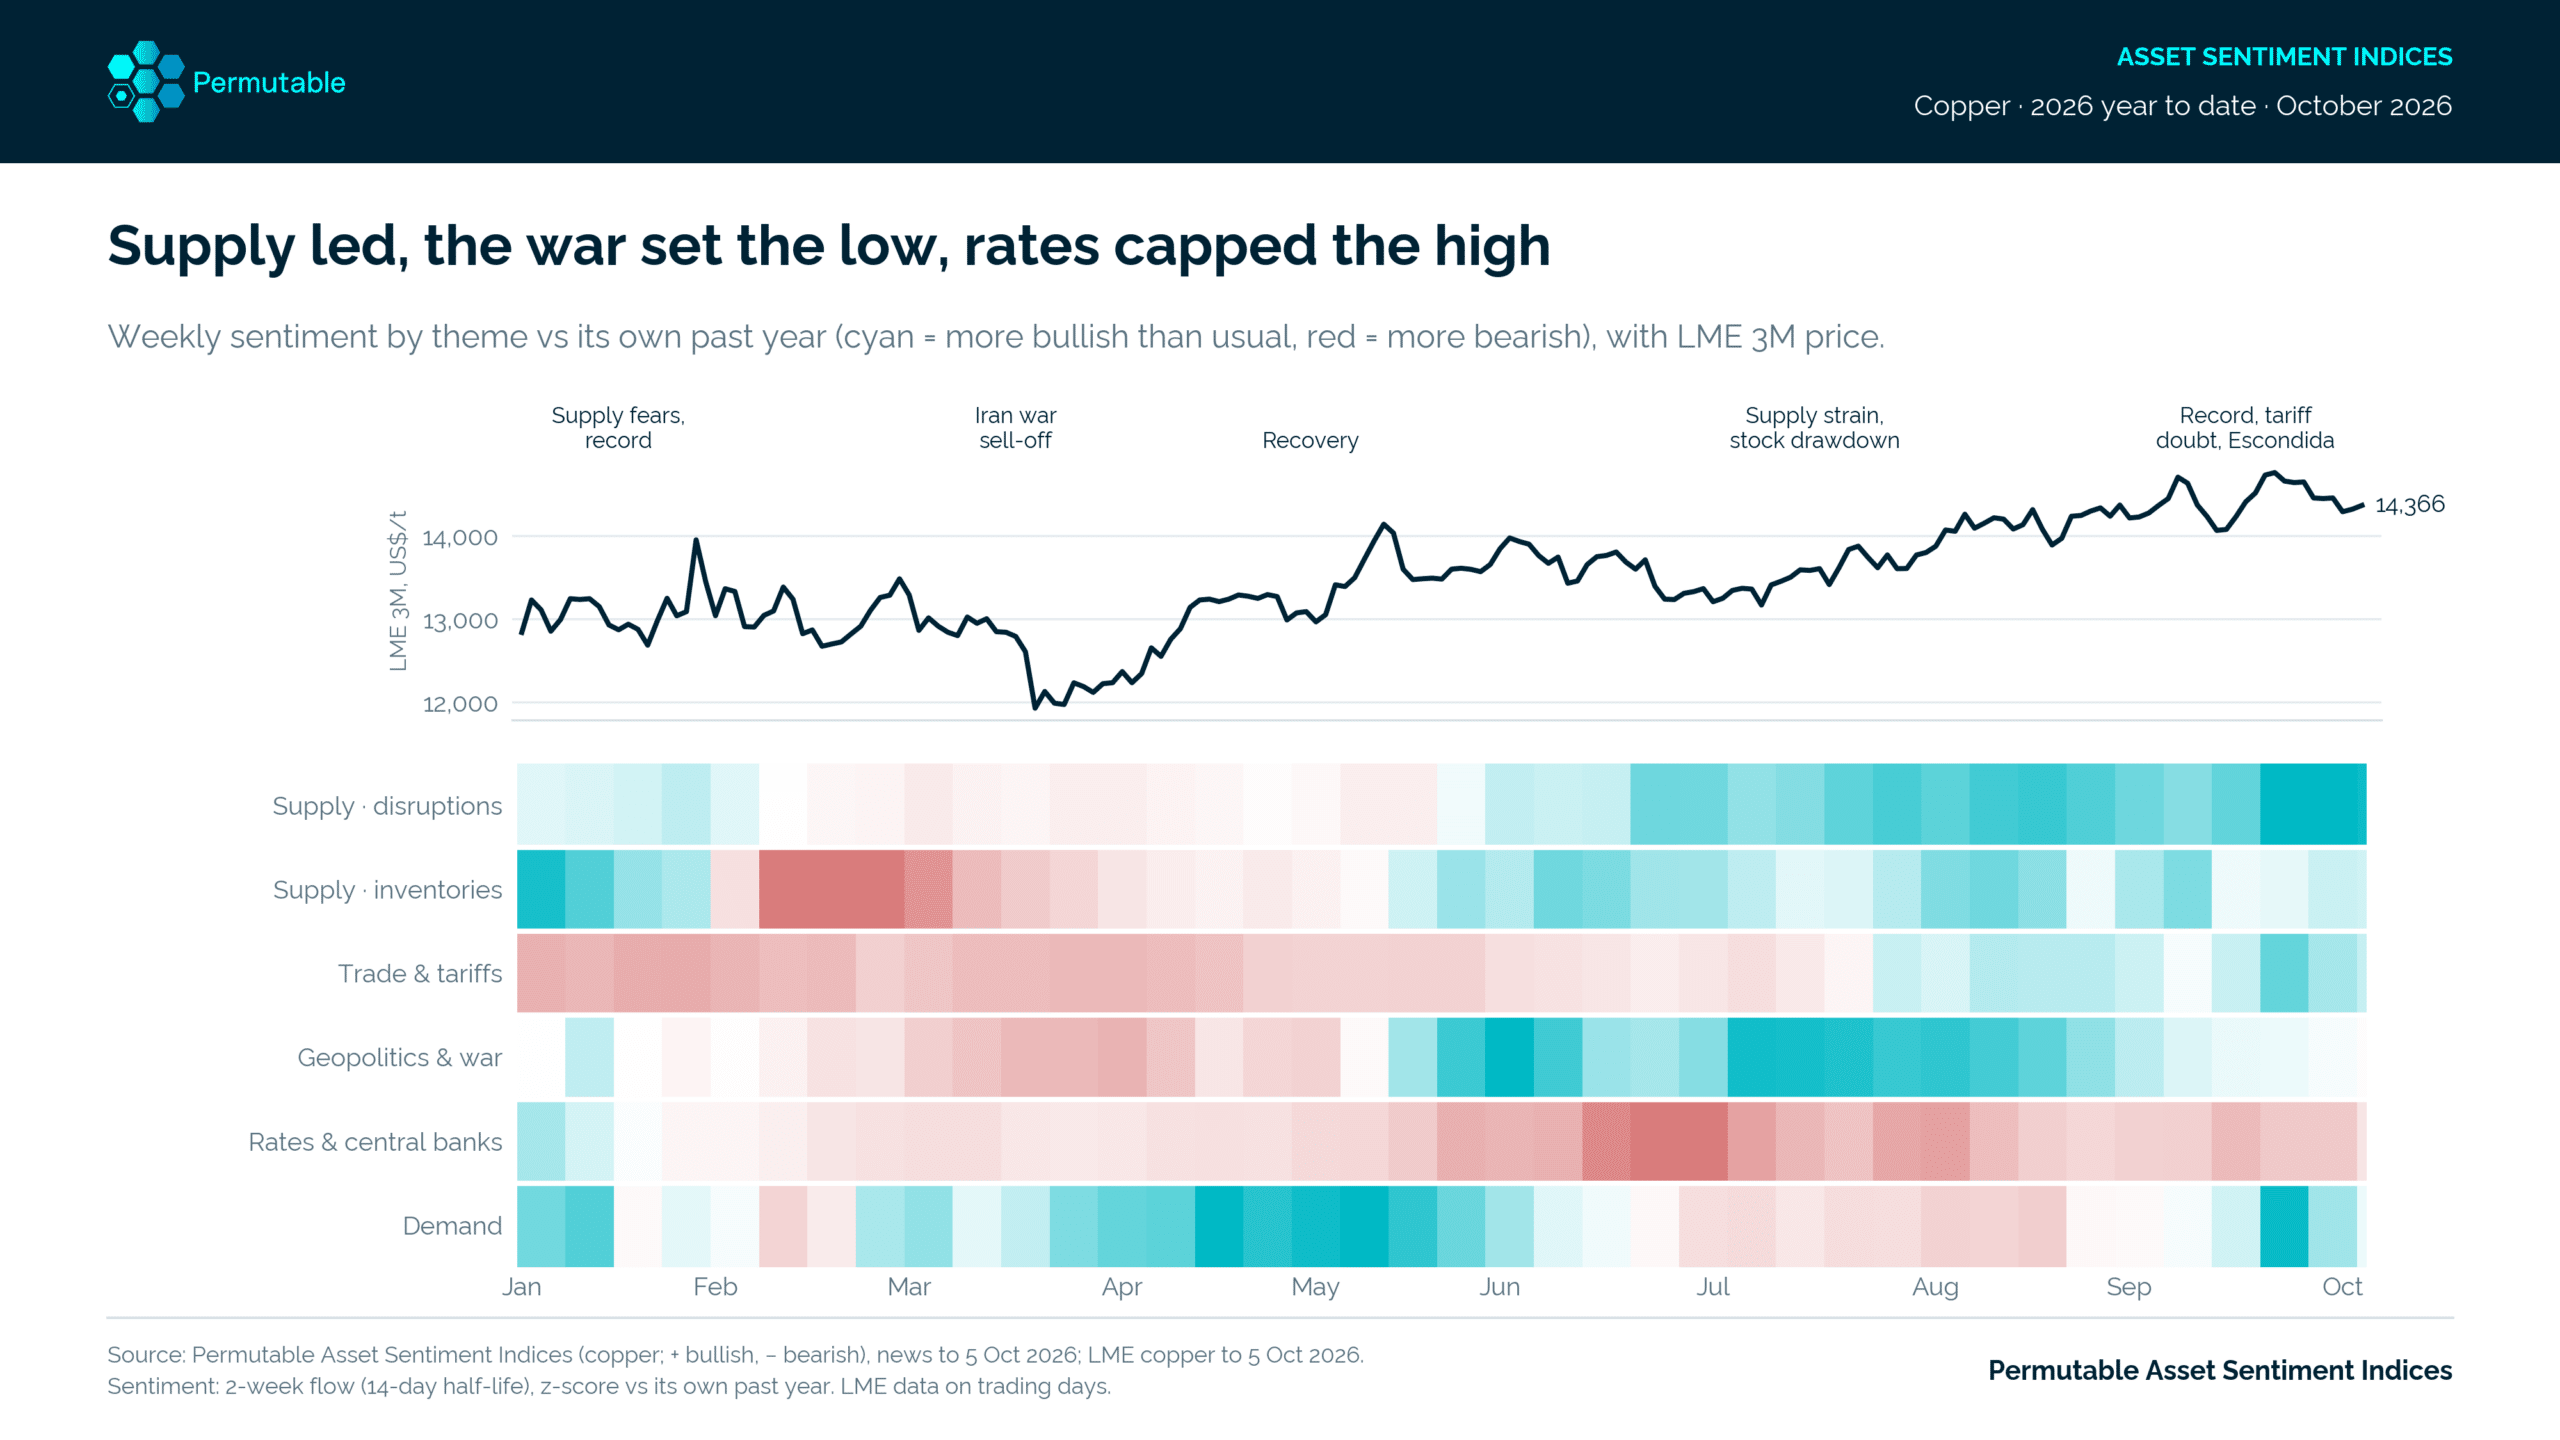
Through successive phases of the rally, the supporting coverage also shifted, with Permutable’s thematic readings recording a handover between geopolitical, demand and supply narratives. Comparatively bearish geopolitical news accompanied the March sell-off, stronger demand sentiment emerged during April and May, and disruption coverage became persistently bullish from June. Rates sentiment weakened through the summer, introducing a monetary counterweight as supply concern gathered force (Chart 2).
The latest snapshot retains a broadly supportive bias, with six of the nine thematic series above their respective one-year norms. Industrial demand stands at +0.9 and trade and tariffs at +0.7, while the broader demand reading of +0.2 shows more modest optimism relative to its own history. Rates and currency register the clearest negative deviations, at −0.6 and −0.9 respectively, with rates coverage remaining below its norm every day since 1 June.
Trade policy adds a geographical complication because the incentive to hold copper depends partly on the jurisdiction in which it can be delivered. Expectations of possible US refined-copper tariffs have encouraged accumulation in American warehouses, reducing availability elsewhere. Pressure in the LME system can therefore coexist with considerable holdings outside it, making the distribution and accessibility of inventories central to interpreting the curve.
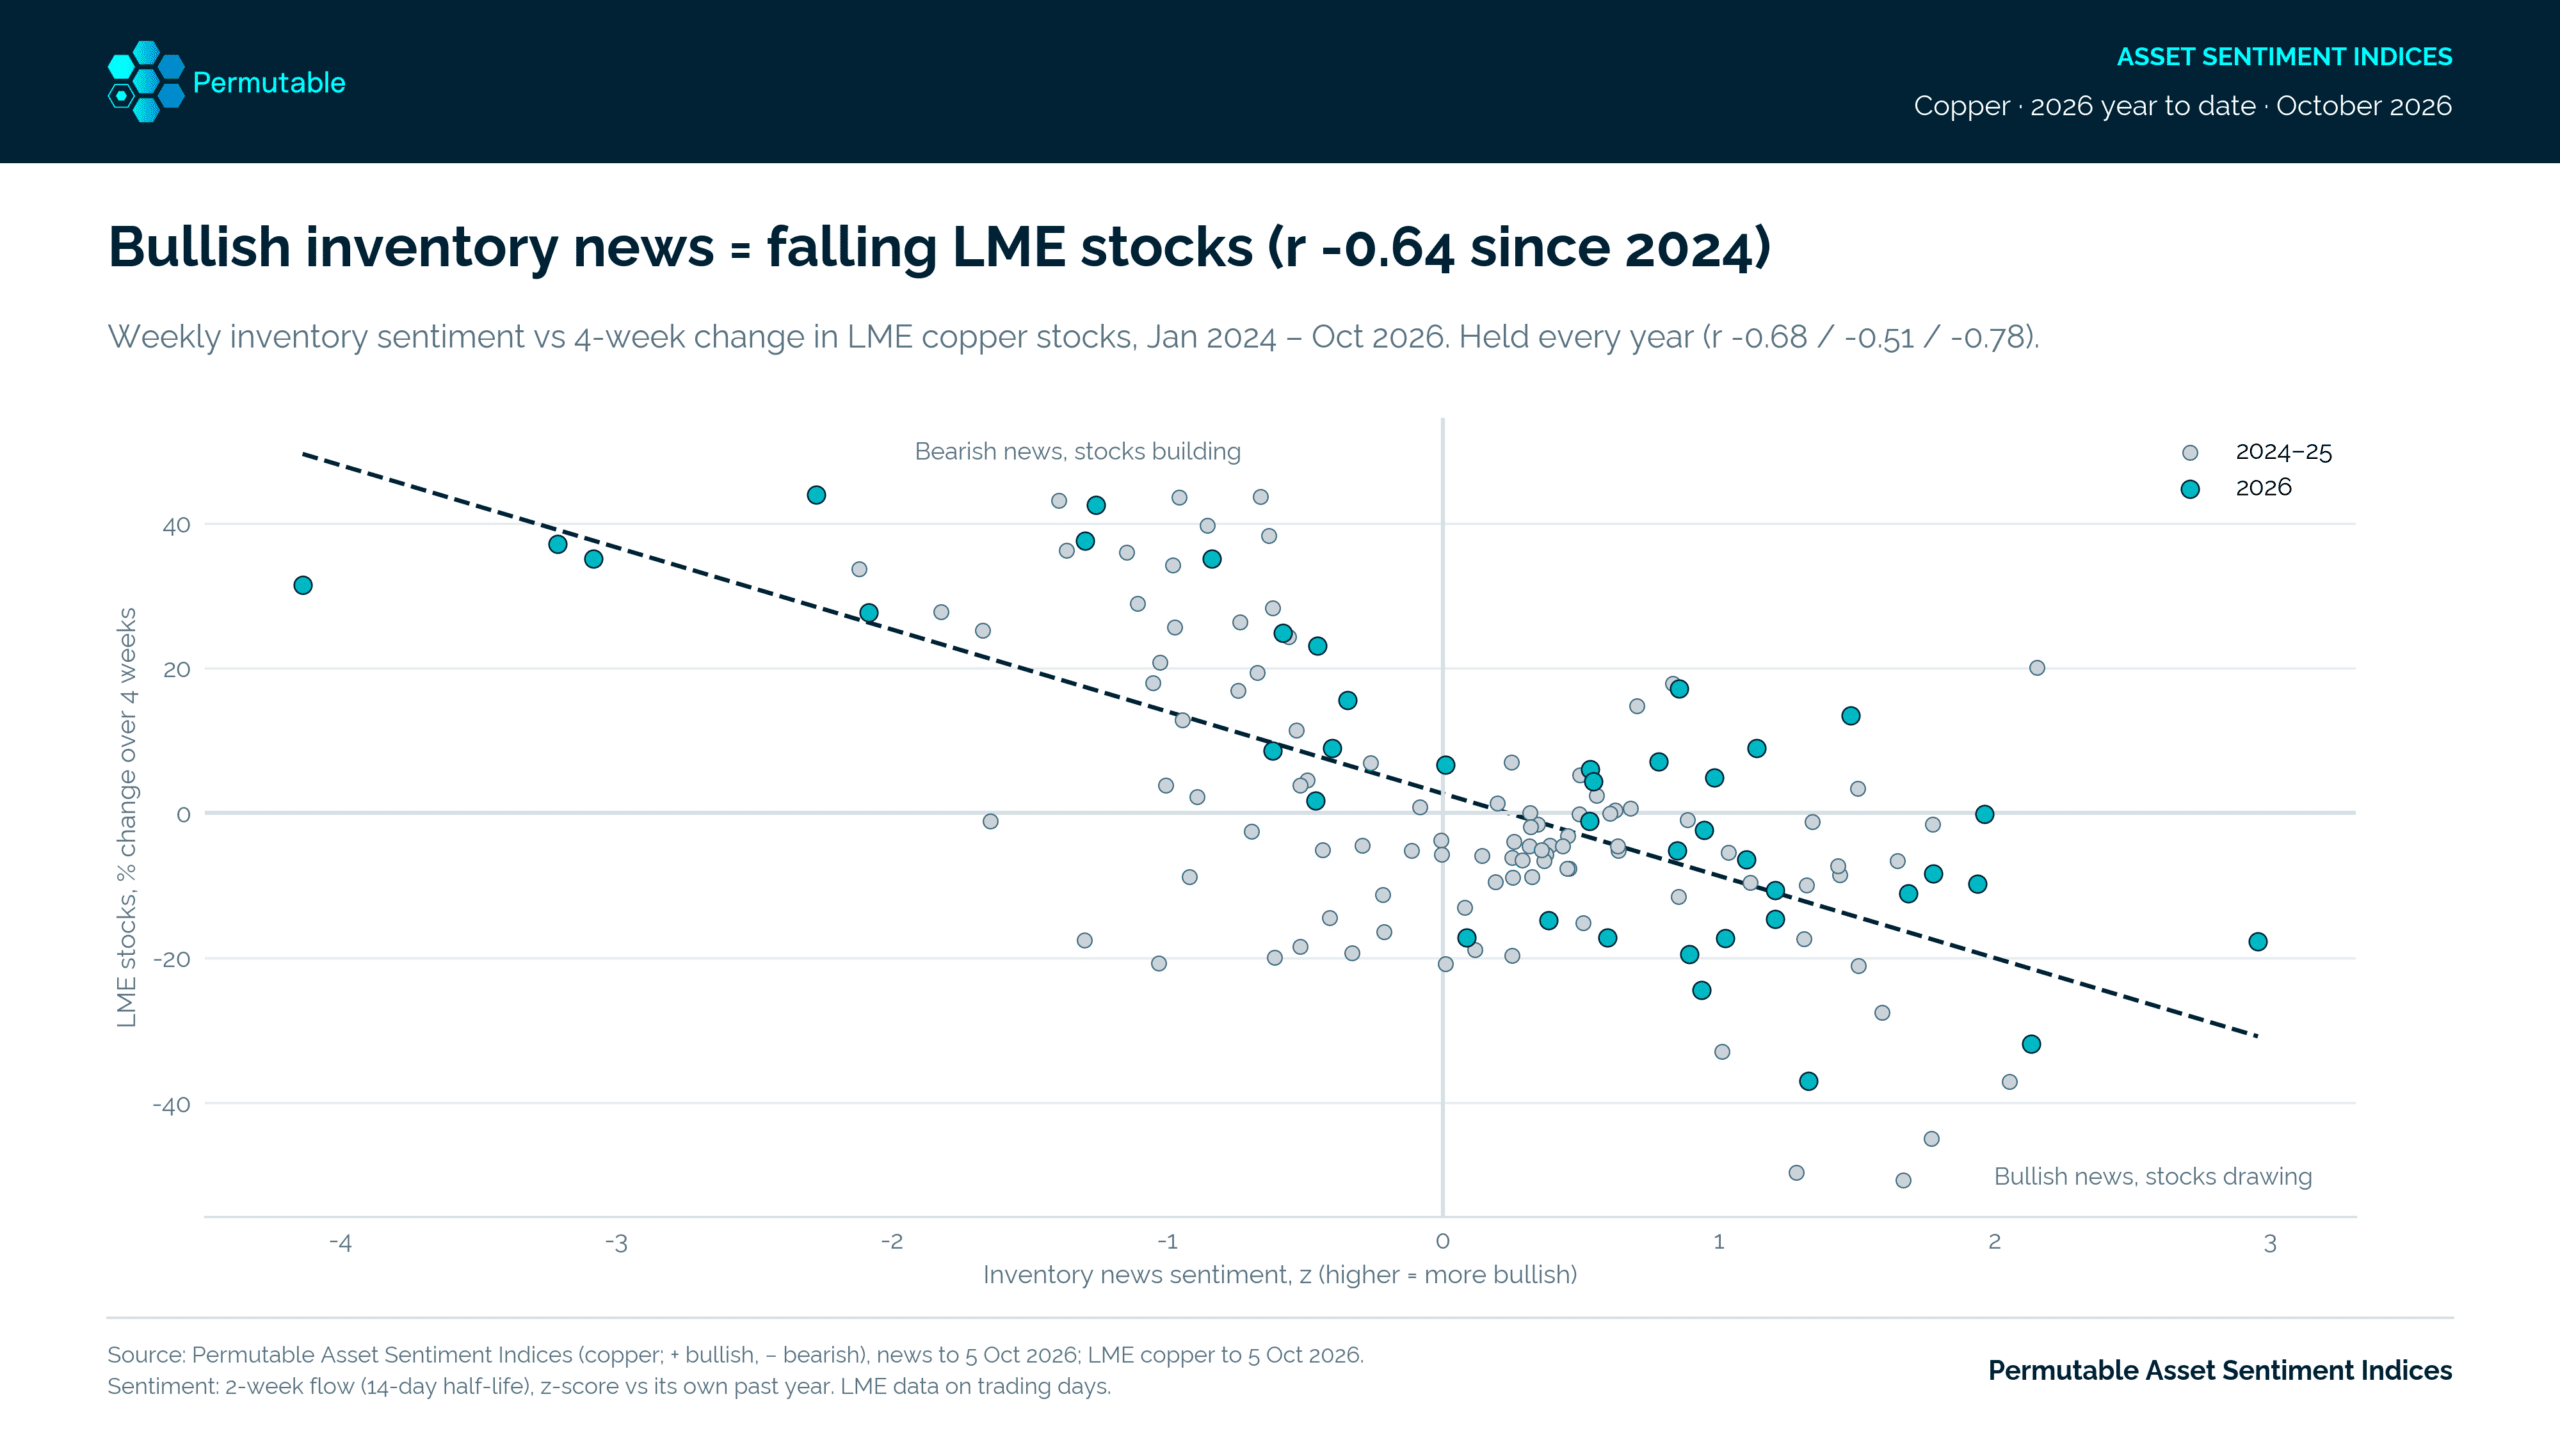
Across a longer sample, the inventory news series has maintained a recurring association with physical warehouse movements, giving the May episode a broader empirical context. Since January 2024, weekly inventory sentiment has correlated at −0.64 with four-week changes in LME stocks. The inverse relationship appears in each annual sample, with correlations ranging from −0.51 to −0.78, as more bullish coverage has accompanied larger stock draws (Chart 3).
From June onwards, disruption coverage has shown particular persistence, exceeding one standard deviation above its trailing-year norm on 89% of days. The reading peaked at +4.5 on 24 September, following the temporary halt at Escondida, and remained elevated at +2.8 on 5 October. Chilean weather interruptions, production guidance cuts and unresolved labour negotiations have sustained this concentration of bullish supply news (Chart 4).
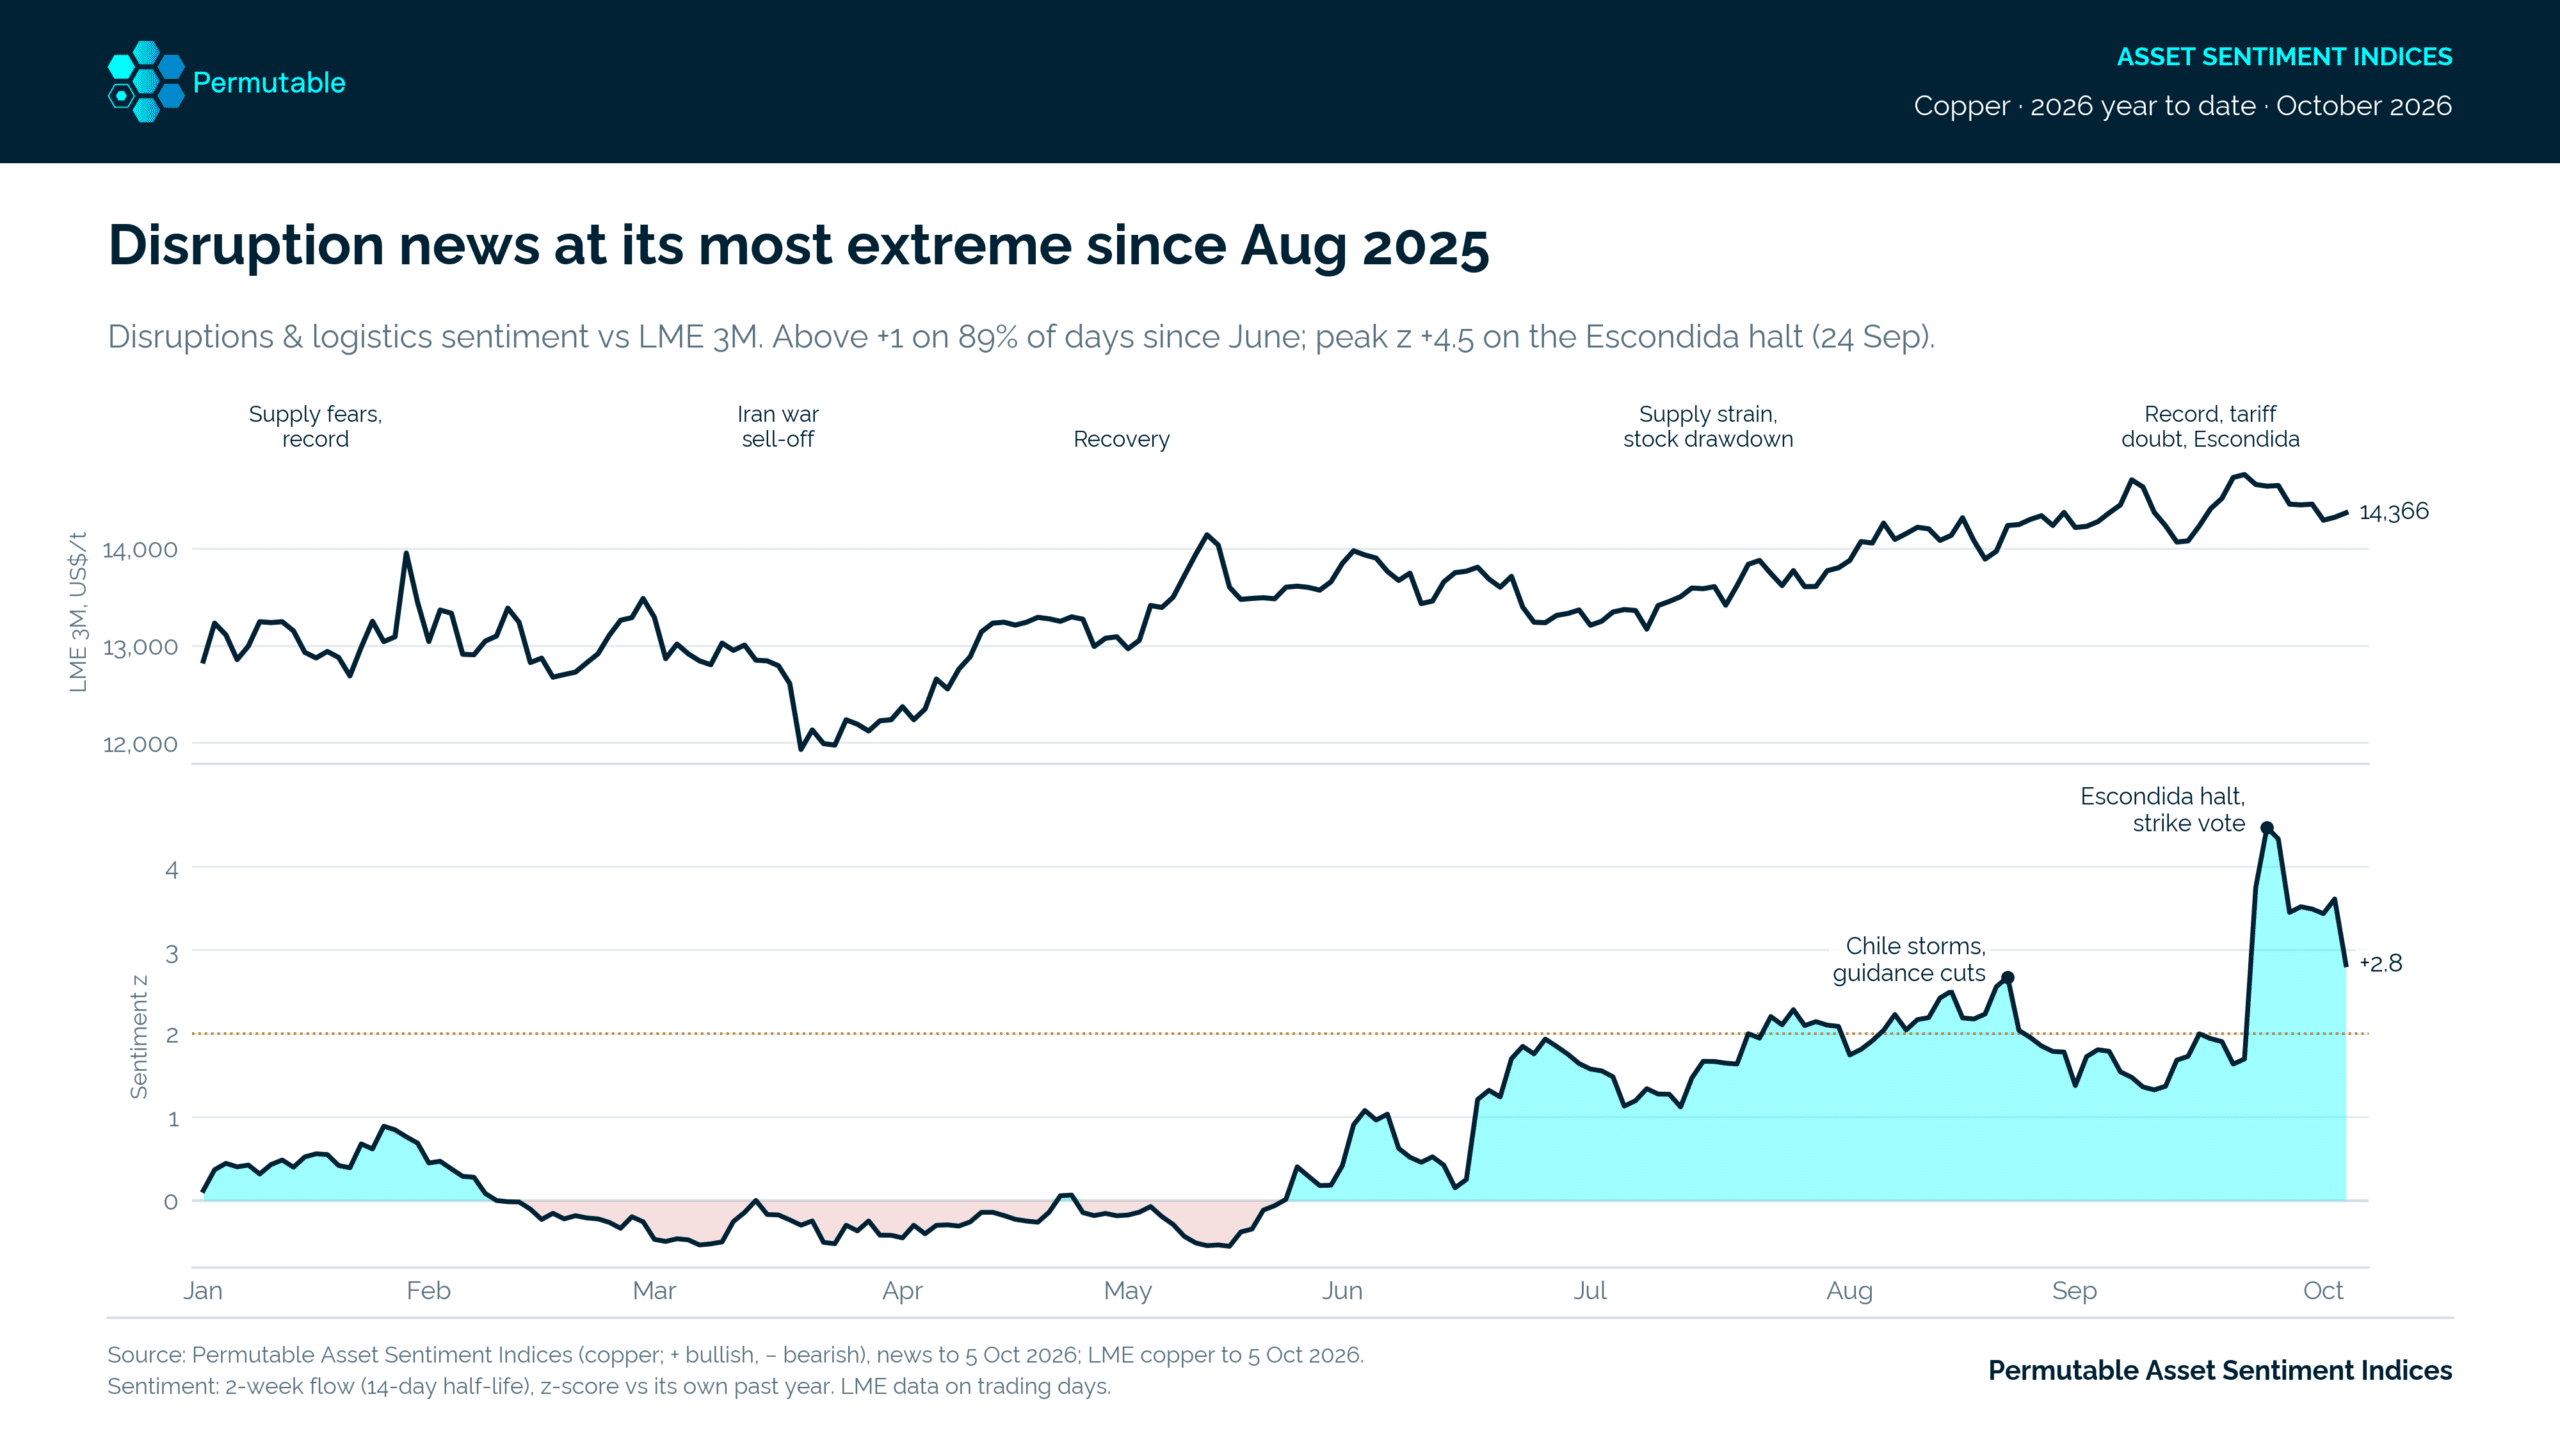
Following supervisors’ rejection of a contract offer at Escondida, the request for mediation on 5 October left the prospect of a stoppage unresolved. The negotiations create a risk to future availability, with the strike vote preceding any confirmed additional production loss. Their outcome carries significance while disruption sentiment remains elevated and nearby metal continues to command a premium.
The rebuilding of LME stocks to 244,900 tonnes nevertheless qualifies the severity of current physical pressure, alongside the substantial narrowing in backwardation since August. Warehouse holdings remain well below April’s peak, but the recovered buffer indicates some relief from the summer’s most acute conditions. A 3,750-tonne draw on 5 October, coinciding with the widening cash premium, deserves scrutiny as a fresh movement within that recovery.
As Chinese buyers return from the holiday break and Chilean negotiations proceed, inventory changes and nearby spreads will provide immediate checks on whether supply concern translates into renewed delivery pressure. Firmer industrial-demand coverage or a sustained improvement in rates sentiment could broaden the support for benchmark prices, while replenishing warehouses and a contracting cash premium would indicate easing availability. Permutable’s Asset Sentiment Indices allow those developments to be followed alongside the physical market, retaining the connection between emerging news, observable stock movements and the price of access to metal.
Methodology: Permutable scores news for its bullish or bearish implications for copper, contributing positively or negatively to the underlying Asset Sentiment measure. The charts use a news-flow measure with a 14-day half-life, standardised against each theme’s trailing year. Historical correlations establish association; the ten-week interval describes the May–July 2026 episode.
01 May 2026
Aluminium and copper outlook 2026: Separating scarcity from demand risk
Read more >
30 Apr 2026
Commodity shock transmission: How real-time sentiment signals reveal market moves before price adjusts
Read more >
30 Apr 2026
Weekly current precious and industrial metals sentiment: Is bullish momentum returning or fragmenting across markets?
Read more >