In this article we examine how US sanctions on Iran have moved Brent crude prices, using our point-in-time sentiment indices. Between February and August 2026 the premium moved off the possibility of lost barrels and onto the price of finding somewhere to put them. Permutable’s geopolitical sentiment indices caught the handover.
Washington called it the harshest economic campaign ever mounted against an adversary. Brent fell anyway, settling at $89.40 on 25 August, 4.7% below where it sat on 20 August. The announcement named no countries and set no dates.
Our energy market sentiment indices had the shape of it first. They score the global information flow around Brent into separate sentiment themes, so the question is never how much Iran is in the news, but which part of the Iran story the market is being asked to price. Global Trade & Sanctions turned bullish into the escalation, while Geopolitics & Conflict and Physical Supply went the other way and outweighed it.
Iran risk is rotating back towards sanctions
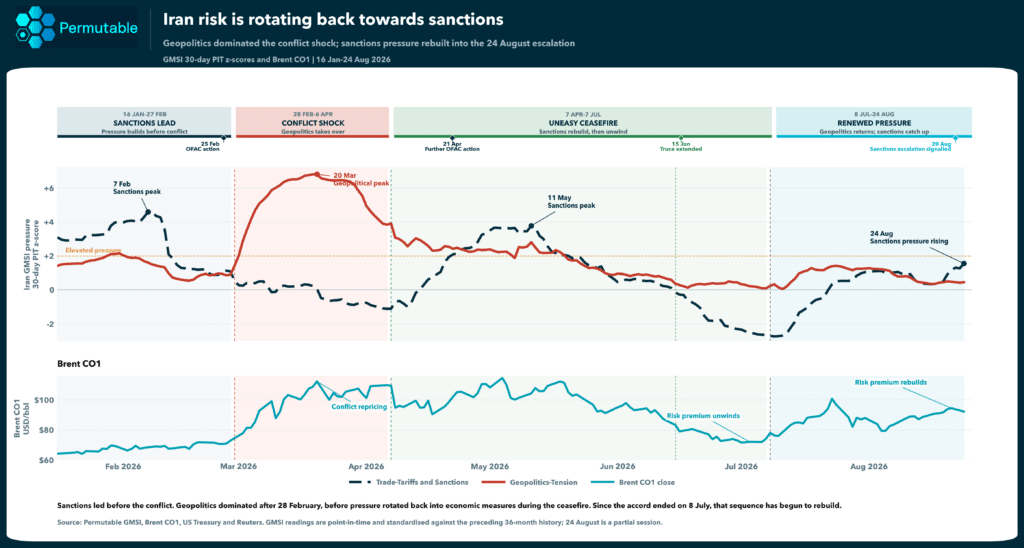
Iran GMSI pressure, 30-day point-in-time z-scores, against Brent CO1 | January to August 2026
The chart runs two macro directional Iran sentiment themes from the Global Macro Sentiment Indices against the CO1 close, standardised on the preceding 36 months. Positive is bullish for Brent, negative bearish, and each value carries only what was known on the day.
A sanctions listing counts for Brent only when it raises the odds that a cargo stops being lifted. Most do something smaller: they move the barrel to a different buyer at a worse price.
Trade-Tariffs and Sanctions moved first, reaching +4.6z on 7 February, three weeks before open conflict and following the 25 February OFAC action. Geopolitics-Tension took over, peaking at +6.8z on 20 March as Brent approached $110. The spring bid sat on that one theme, which is why it drained once the shooting stopped.
The 7 April ceasefire reversed the balance without flushing out the pressure. Sanctions rebuilt to +3.8z by 11 May. Both themes eased after the 15 June truce extension, then turned up again once the accord ended on 8 July.
By 24 August, Trade-Tariffs and Sanctions had risen to while Geopolitics-Tension kept sliding. The Brent panel beneath says the same thing in price: the premium that unwound through late June has rebuilt, and it has rebuilt on the economic leg.
The change since March is one of channel rather than intensity. Pressure now travels through Iran’s access to buyers, banks and shipping, rather than through an immediate threat to production or to passage through Hormuz. That matters for how long it lasts. A ceasefire can strip an escalation premium out inside a week, while a sanctions premium takes weeks to draft and months to unwind.
Markets are pricing trade enforcement, not an immediate supply shock
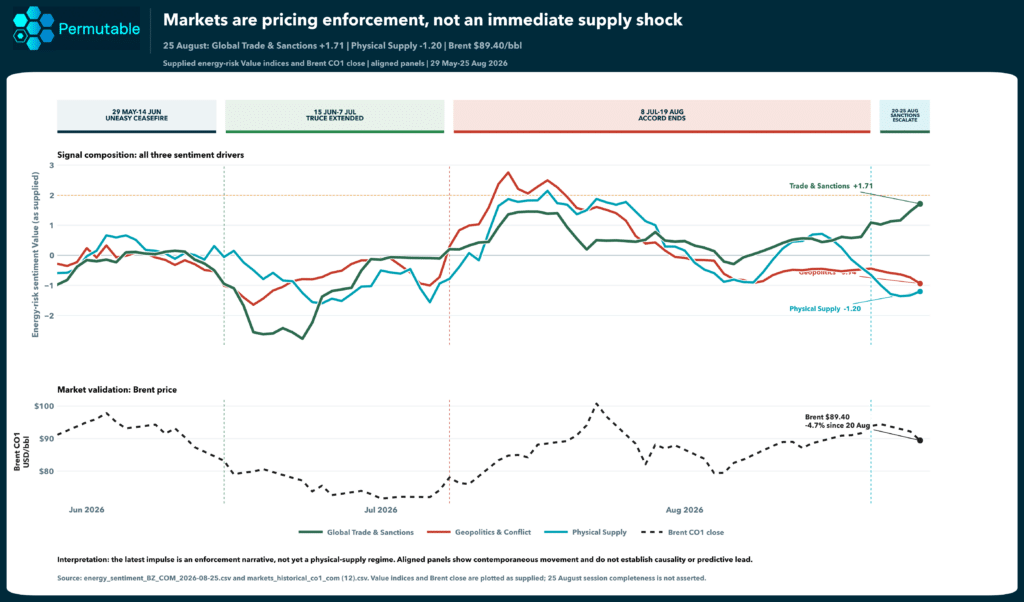
Energy-risk value indices and Brent CO1 close, aligned panels | 29 May to 25 August 2026
Between early July and early August the three drivers rose together. Brent moved from about $72 to a peak near $101 as the market rebuilt a broad Iran risk premium, with no single theme doing the pulling.
Since the 20 August escalation they have separated. Global Trade & Sanctions is at +1.71, Geopolitics & Conflict at −0.94, Physical Supply at −1.20. This is the first time since July’s repricing began that sanctions pressure has risen while the geopolitical and supply signals have fallen. The panels move contemporaneously and are not presented as evidence of a predictive lead.
A bid held up by one driver is easier to walk away from than one held up by three.
Two workings at play sit behind the recent pullback.
The near-term outlook for Hormuz has improved on the corridor framework, not on the traffic. Iran and Oman have set out a temporary joint corridor and a de-mining programme, and with no secondary sanctions in force the risk of a material interruption to Iranian flows has receded. Transits themselves remain depressed, down to a handful of commodity vessels a day against a ten-day average nearer fifteen, with a slice of what remains running dark. The market is pricing the framework rather than the tape.
Emergency releases have provided a second cushion, and it is thinning. US strategic reserves stand at 289.7mn barrels, the lowest since 1982 and around 41% of authorised capacity, so the stock draw that absorbed the spring shock is a weaker option now.
Our view is that the market is right to look past the traffic numbers while the corridor talks hold, and wrong from the moment a round fails. On the evidence to date it is pricing greater friction around trade, not an imminent shortage of crude.
China takes the large majority of Iranian crude and receives around two-thirds of everything leaving Hormuz. Independent refiners handle most of that barrel and roughly a quarter of Chinese refining capacity, which makes them the constituency a serious campaign has to reach. Nothing announced so far reaches them.
Estimated Chinese imports have fallen to roughly 0.53mn barrels/day in August from 1.57mn in February. Handle that with care, because a fall in observed volume looks identical to a fall in observable volume. Relabelled cargoes, ship-to-ship transfers and dark tonnage all remove barrels from the data without removing them from the market. Iran has also met tighter restrictions with steeper discounts, and a discount is a reason for an independent refiner to lift more.
Two readings fit. If Chinese buyers have stepped back, barrels are leaving the balance and supply pressure should build within weeks. If they have gone dark at a wider discount, nothing has left the market and the sanctions leg is a toll on the trade rather than a constraint on it.
Energy-inflation pressure and Brent across the Iran risk cycle
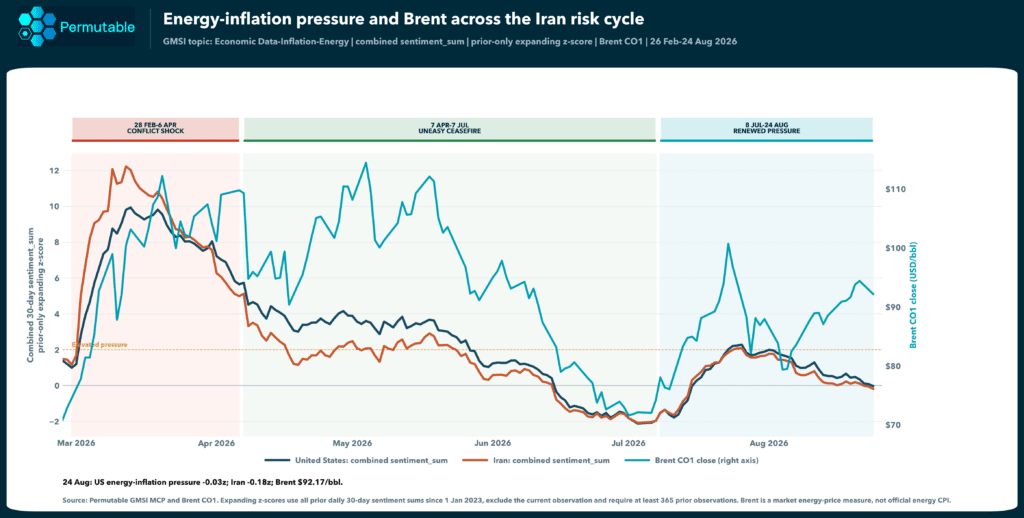
GMSI energy-inflation sentiment, prior-only expanding z-score, against Brent CO1 | February to August 2026
In March, US energy-inflation pressure reached +9.8z and Iran’s +12z as Brent approached $110. July’s rally lifted both back to about +2.2z, but by 24 August they had fallen to −0.03z and −0.18z with Brent at $92.17, and the price has eased further since.
Rates face less pressure than in March. The latest measures have not produced a sustained move in bond durations. What has gone is the marginal push, which is the part that moves expectations. The level effect of Brent well above where it started the year has not reversed with sentiment.
FX exposure remains exposure dependent. Higher crude weigh’s on India’s terms of trade, while Turkey, Pakistan and Egypt have less room to absorb imported energy costs. Those risks would build if Brent and Physical Supply turned higher together.
Secondary measures would need to name their targets. Chinese independent refiners, settlement banks or insurers, with dates attached, would change purchasing decisions instead of shipping arrangements. We are sceptical it goes that far. Penalties on major buyers carry costs Washington has flinched from before, and Mr Trump’s habit of announcing more than he imposes is now priced in as an assumption.
The physical market would then have to confirm it, through falling Iranian exports, a narrowing discount on Iranian crude, tighter freight, backwardation, or crack spreads that stop behaving. Those move on behaviour rather than on reporting volume, which is what makes them the test that settles the China question.
Energy-inflation pressure would have to rebuild last, carrying into rates, currencies and policy expectations.
Until then, sanctions are changing the routes and costs attached to Iranian oil more than the amount of crude available. A cargo can be entirely available and still short of a home.
Iran risk has moved back towards economic coercion.
Oil pressure has split: Global Trade & Sanctions is rising while Geopolitics & Conflict and Physical Supply fall.
Macro transmission remains weak, with energy-inflation pressure close to zero and Brent moving lower as central banks see through some what perodic high energy prices.
The value of using the GMSI and the asset indices is in showing where the underlying pressure sits, the hand over of driver and whether it is reaching supply or inflation.
A Brent move built on Trade & Sanctions does not last like one built on lost production or a blocked route. Trade & Sanctions reprices counterparties and differentials. Physical Supply reprices availability, and availability is the one that reaches breakevens, currencies and policy expectations with any reliability.
Permutable’s Energy Indices pull those drivers apart inside the Brent information flow, while GMSI carries the same structure across 95+ economies and 70+ macro topics. Both datasets hold 11+ years of point-in-time history and reach you through API or Excel, as well as an accessible developer platform, for use alongside discretionary or systematic research.
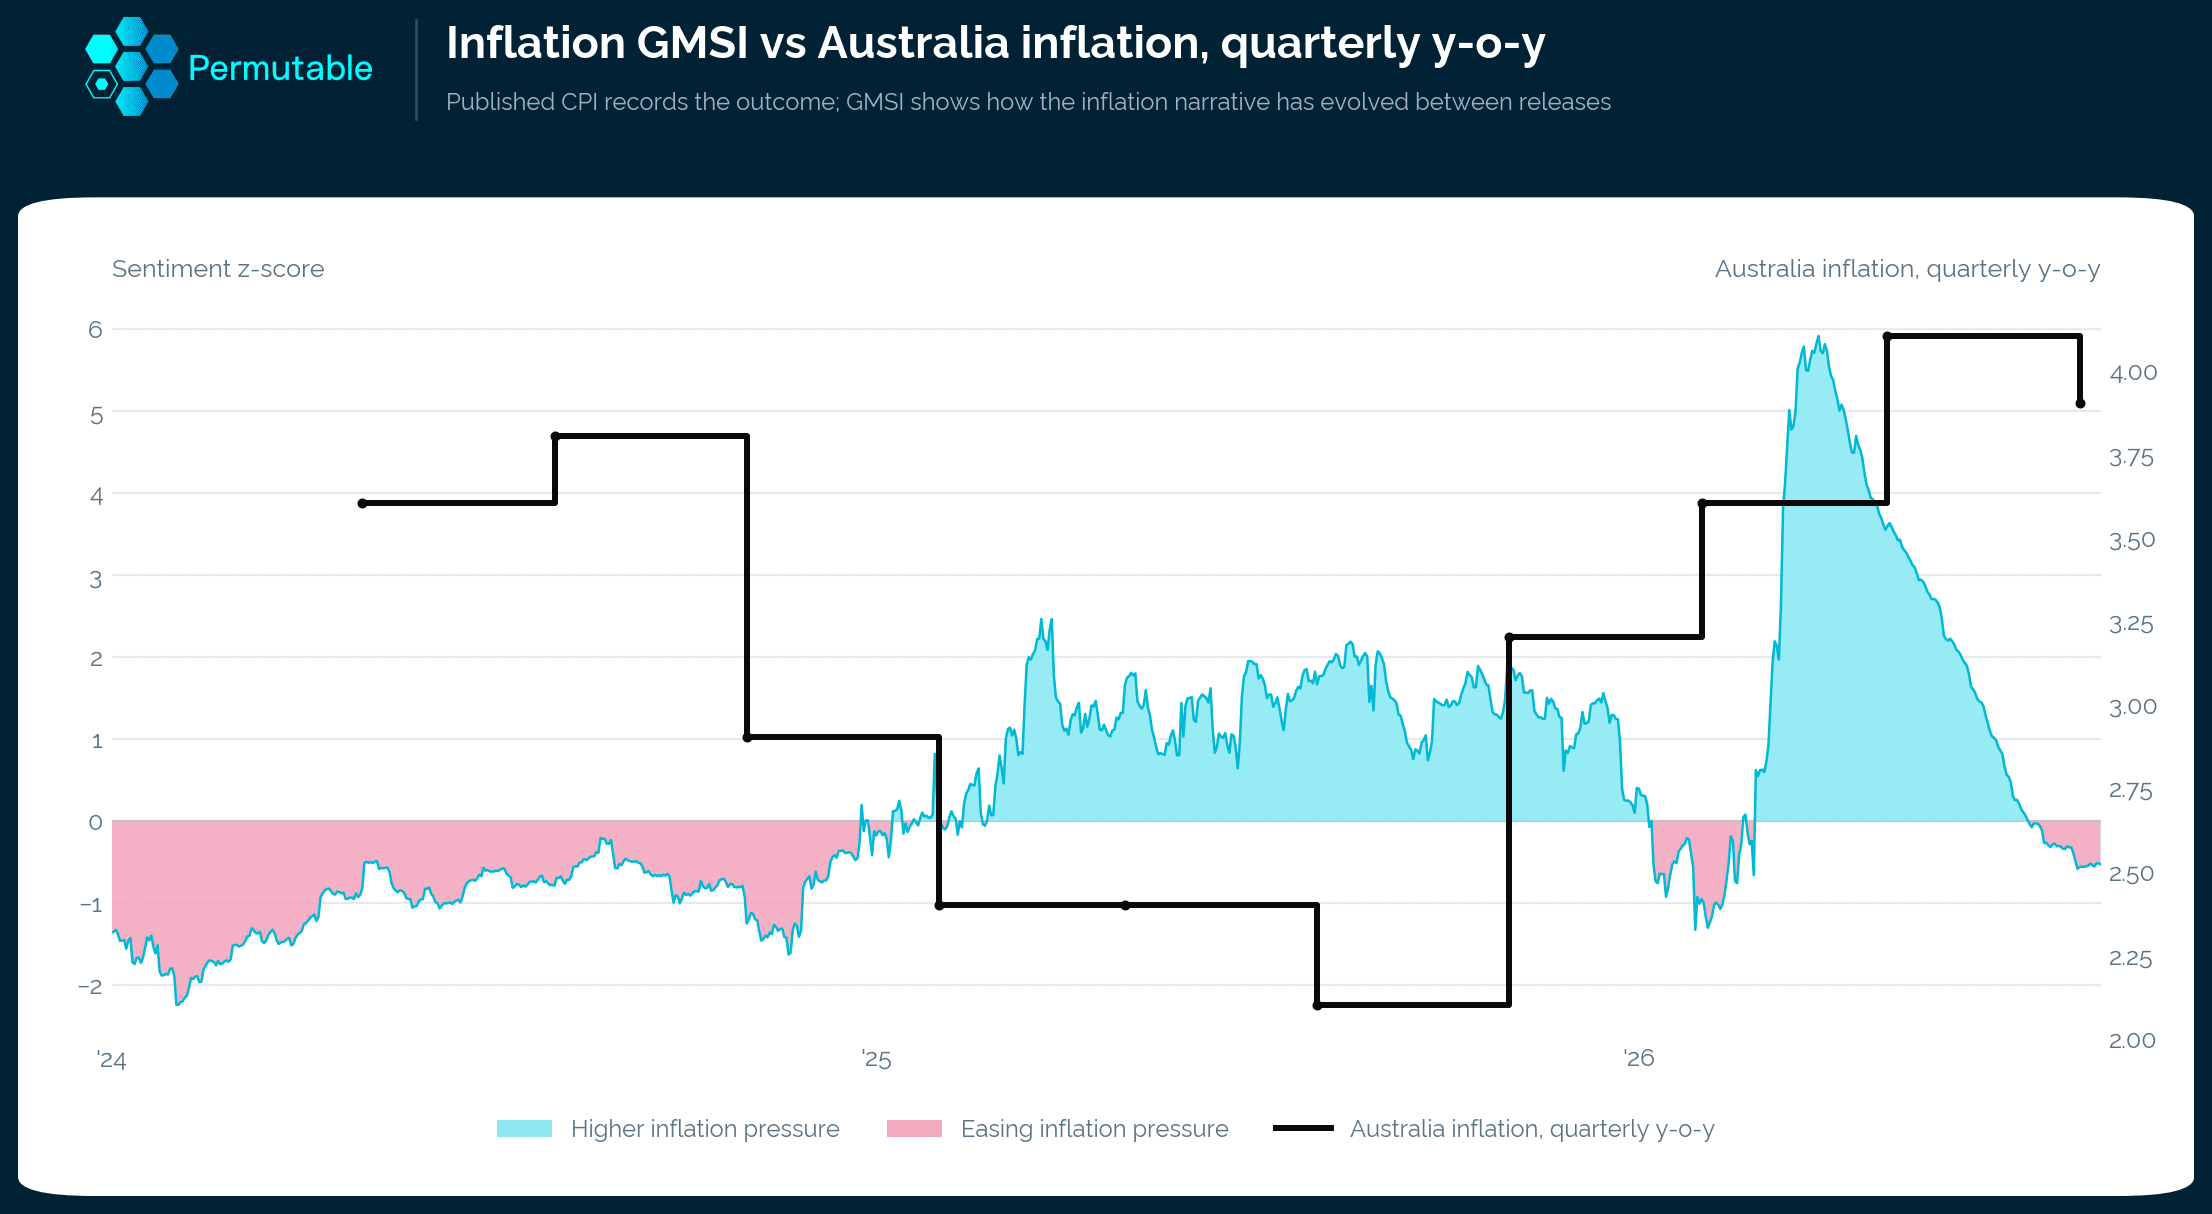
The RBA interest rate outlook points to an extended hold rather than an early easing turn. Australia’s inflation pressure has eased sharply, but the broader economy has not weakened enough to justify easier policy. Permutable’s Global Macro Sentiment Indices show softer inflation and housing alongside resilient spending, firmer employment sentiment and elevated capacity utilisation, while rising business costs continue to complicate the picture.
The inflation scare that drove Australia’s renewed tightening cycle has faded faster than expected, but the economy has not rolled over with it.
Inflation outcomes have softened, labour conditions have eased from their earlier extremes and housing expectations have weakened. At the same time, household spending remains resilient, employment conditions have firmed again and business capacity remains stretched.
This report’s central conclusion is that another rate increase is no longer the natural next step. Instead, the current configuration supports an extended period on hold.
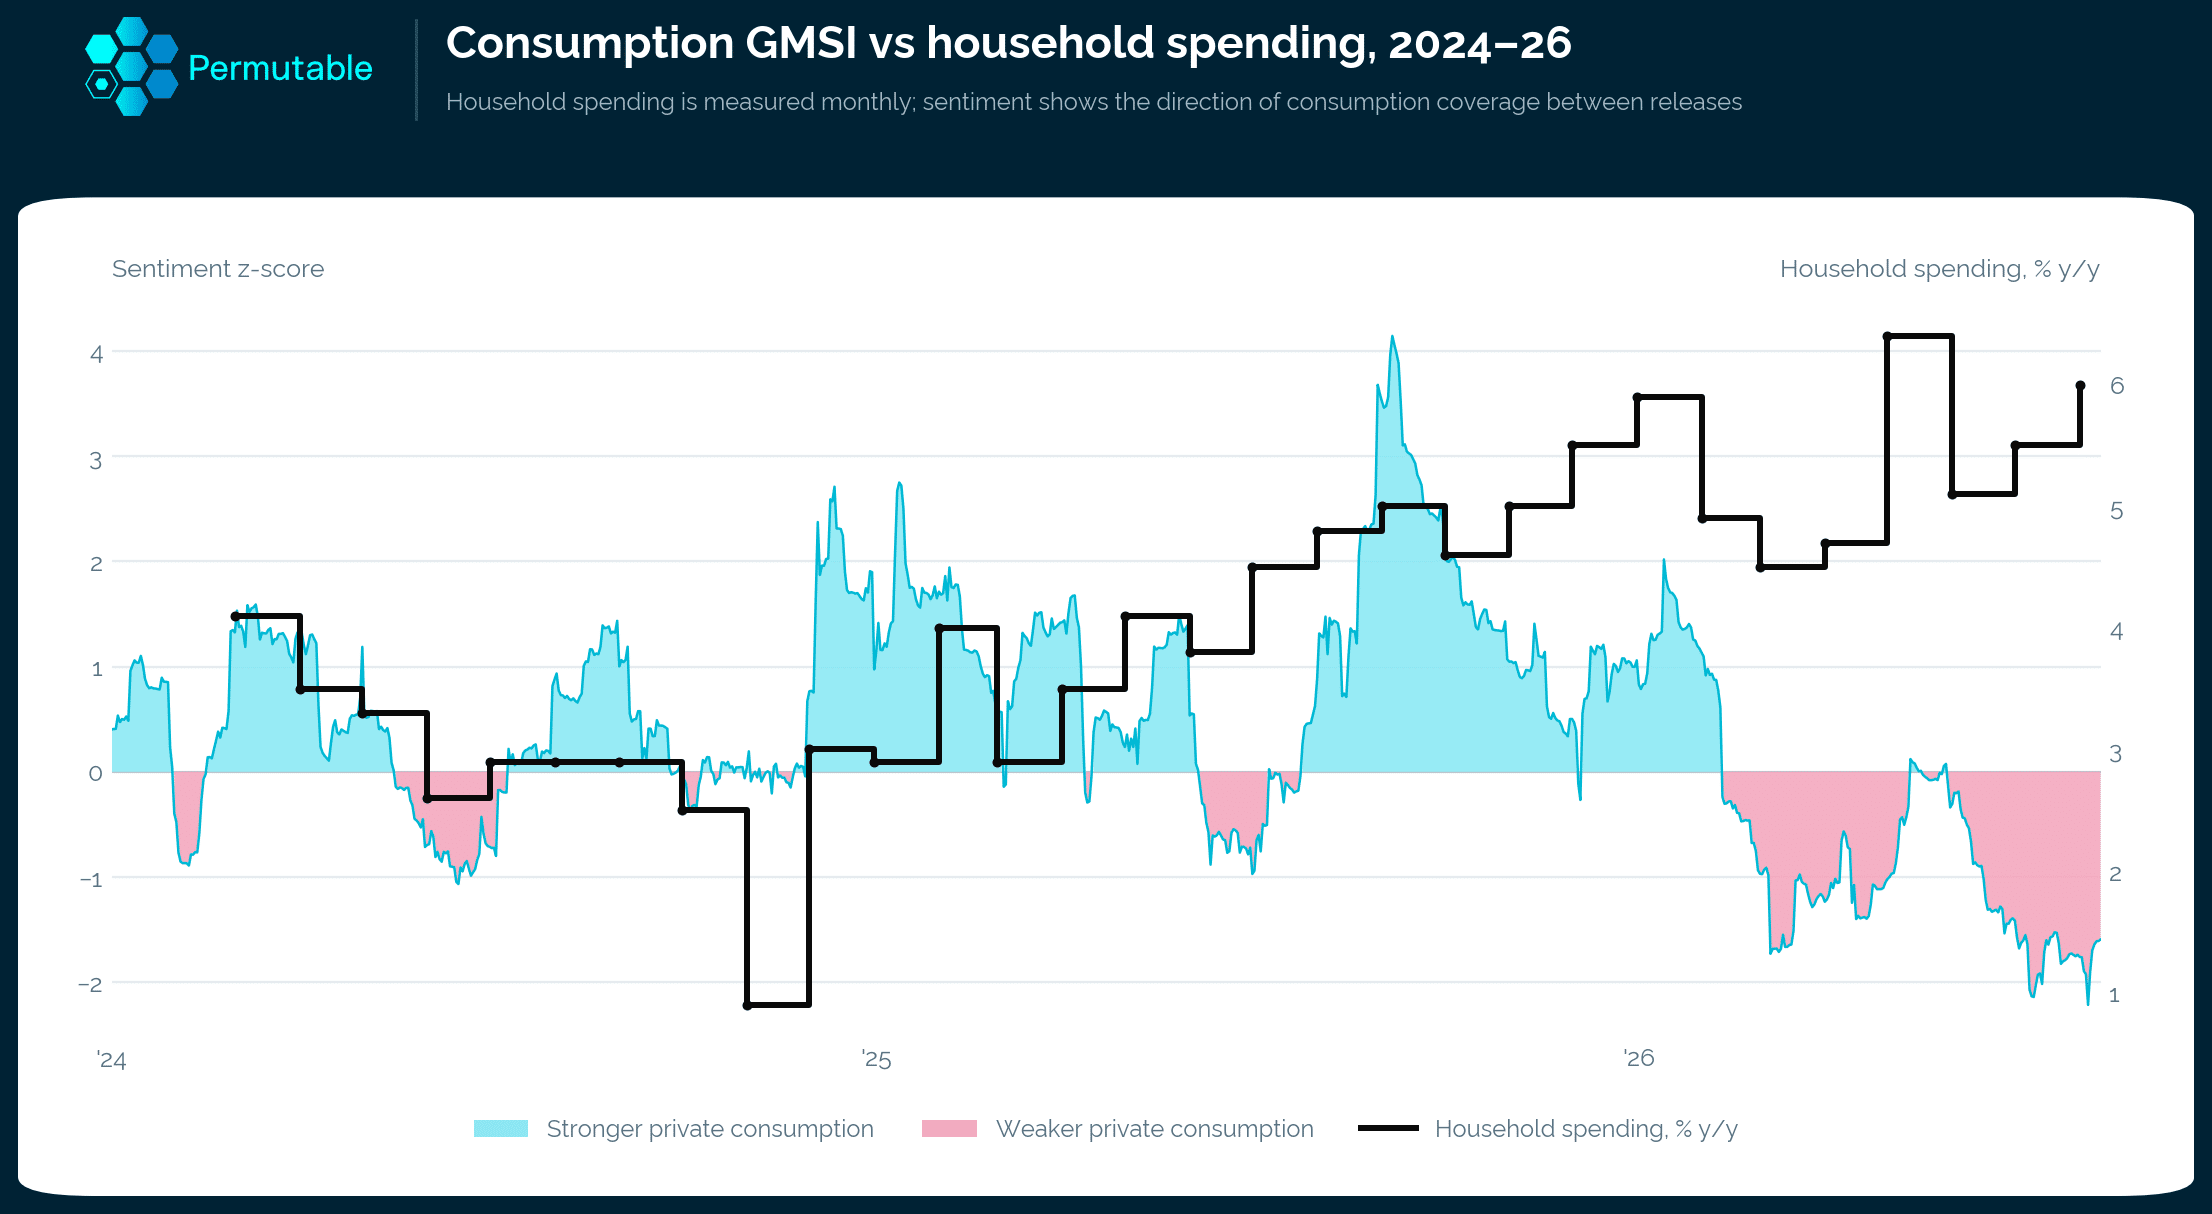
At the time of the report, the cash rate stood at 4.35%, unemployment at 4.4%, household spending was 6.0% higher year on year and the Australian two-year government bond yield stood at 4.59%.
The RBA has enough evidence that restraint is working to remain on hold.
Inflation outcomes have been softer than earlier feared, labour conditions have eased from their extremes and housing expectations have weakened. Another increase is therefore no longer the natural next step.
Permutable’s inflation GMSI rose to almost +6z in late March before subsequently falling below zero. The quarterly inflation-rate series eased much less sharply, reaching 3.9% year on year in June.
Interest-rate GMSI also moved back towards neutral following its early-2026 peak. The report interprets this as a shift in the policy debate from whether further tightening is required towards how long the existing level of restraint should remain in place.
That gives the RBA time to wait, although inflation close to 4% still leaves little room to ease.

Household demand has weathered higher rates better than expected.
Spending rose 0.8% in June and 1.3% over Q2, while real volumes increased 0.7% over the quarter.
The sentiment picture is weaker. Consumption GMSI stood at around −1.6z after reaching −2.2z in early August.
The report identifies a clear condition to watch: persistent weak coverage followed by softer spending would indicate that demand momentum had rolled over.
For now, consumers are still spending and do not provide a reason for the RBA to ease.
The labour market has eased from its earlier extremes without showing the sharp deterioration that would require policy support.
The unemployment rate edged back to 4.4% after reaching 4.5%, while Permutable’s employment GMSI recovered to around +0.8z.
The unemployment axis in the report is inverted so that the two series move in the same economic direction.
Conditions have therefore loosened compared with their earlier extremes, but there is little evidence in the report of the kind of sharp deterioration that would require policy support.
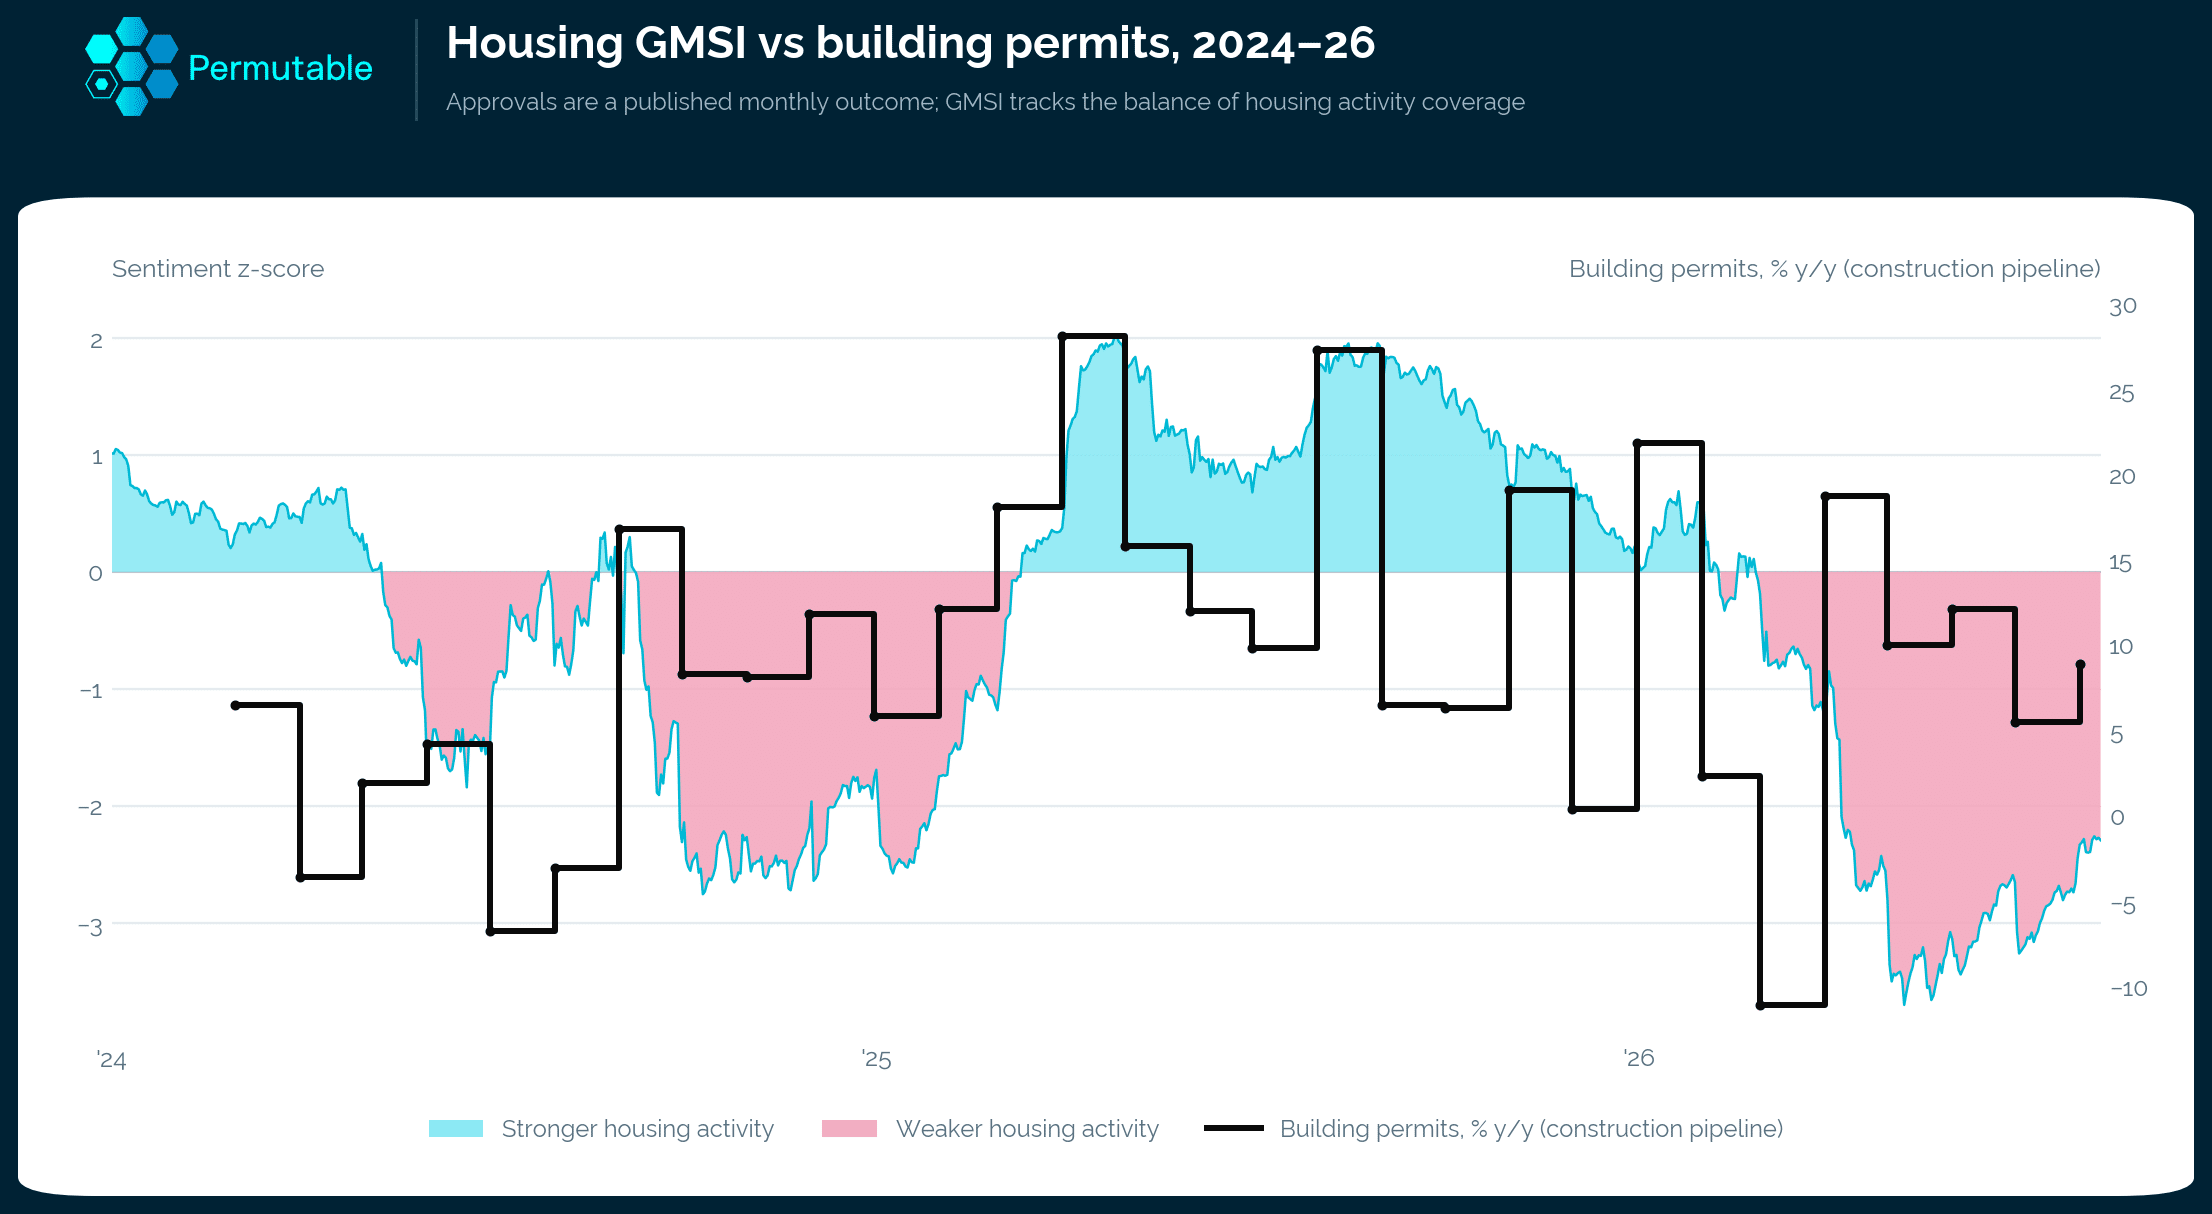
Housing GMSI remained near −2.3z, making it the weakest current macro signal identified in the report.
Home values fell 0.7% in July and stood 1.6% below their March peak, while home-loan enquiries weakened.
Building permits remained volatile and are used in the report to describe the construction pipeline.
The document notes that housing-finance approvals are the preferred direct measure of rate transmission when a point-in-time series is available. The supplied Q1 figure was −3.8% quarter on quarter.

Business confidence held at −6 in July, even as business conditions edged up to +4.
The firmer activity reading was accompanied by a renewed build-up in cost pressure. Capacity utilisation rose to 83.0%, labour costs increased 2.2% quarter on quarter, purchase costs rose 2.3% and final product prices increased 1.1%.
Forward orders fell to −3, however, suggesting that demand remains fragile beneath the surface.
For the RBA, the report describes this as an awkward mix: enough softness to justify patience, but still too much pressure on capacity and costs to support an early easing turn.
Policy-outlook GMSI and the Australian two-year yield both reversed sharply as the outlook was repriced in early 2026.
The latest configuration is different.
Policy-outlook GMSI fell from around +4z to near neutral, while the Australian two-year government bond yield remained around 4.6%.
The report states that markets are not pricing a rapid easing cycle. Instead, they continue to embed a higher-for-longer path even though the incremental shift towards further restriction has faded.
The common thread is an economy losing some momentum without becoming weak.
Housing has softened first, consumption coverage has deteriorated and inflation pressure has eased substantially from its early-year extreme.
At the same time, household spending remains firm, employment sentiment has recovered and capacity utilisation remains elevated.
That combination gives the RBA enough evidence that restraint is working to leave rates unchanged, but little justification for easier policy.
Australia has weathered the inflation storm better than feared. The RBA now has the luxury of waiting – but not yet of standing down.
Read the full three-page GMSI analysis covering inflation, interest rates, household consumption, employment, housing, business conditions and the Australian two-year government bond yield.
Explore Global Macro Sentiment Indices
This report examines the central bank policy outlook across 14 major economies using Permutable’s Major Central Bank Sentiment Index, part of its Global Macro Sentiment Indices. It finds that 12 of 14 central banks have shifted in a more hawkish direction over twelve months despite very different current policy settings. It is aimed at macro investors, rates and FX strategists, economists, risk teams and institutional research desks.
The global central bank policy outlook has shifted in a more hawkish direction even though current policy settings remain widely dispersed. Three central banks held rates last month despite objections from hawkish minorities. The Bank of Japan voted eight to one to hold, the Federal Reserve recorded three dissents in favour of an immediate quarter-point increase, and the Bank of England voted six to three to leave Bank Rate unchanged.
Every minority lost the vote. Yet Permutable’s Major Central Bank Sentiment Index, part of our Global Macro Sentiment Indices suite, shows directional policy-outlook sentiment moving towards those dissenters. Over twelve months, policy-outlook sentiment has shifted towards the hawkish end at the Bank of Japan, Federal Reserve and Bank of England by +21.2, +81.2 and +36.0 respectively.
The Federal Reserve and the Bank of England have both been on hold since December, five consecutive meetings each, and in both cases the last move either made was a cut. Japan is different: the Bank of Japan has raised rates twice within the same twelve-month window, most recently moving to 1% in June. Its dissent also flipped from dovish to hawkish in the six weeks between the June increase and the July hold. The ECB is the other central bank to have acted, raising in June for the first time in almost three years.
Across the complete cross-section, 12 of the 14 central banks have moved towards the hawkish end over the past year. Only Russia and Brazil have moved in the opposite direction, and both are currently cutting from policy rates of 14%.
The dispersion is therefore real, but it increasingly reflects how far individual central banks have travelled rather than whether they are moving in fundamentally different directions. Energy, currencies, labour markets and domestic demand are setting the pace. Policy rates themselves usually adjust later, and in this window only Japan and the ECB have adjusted at all.

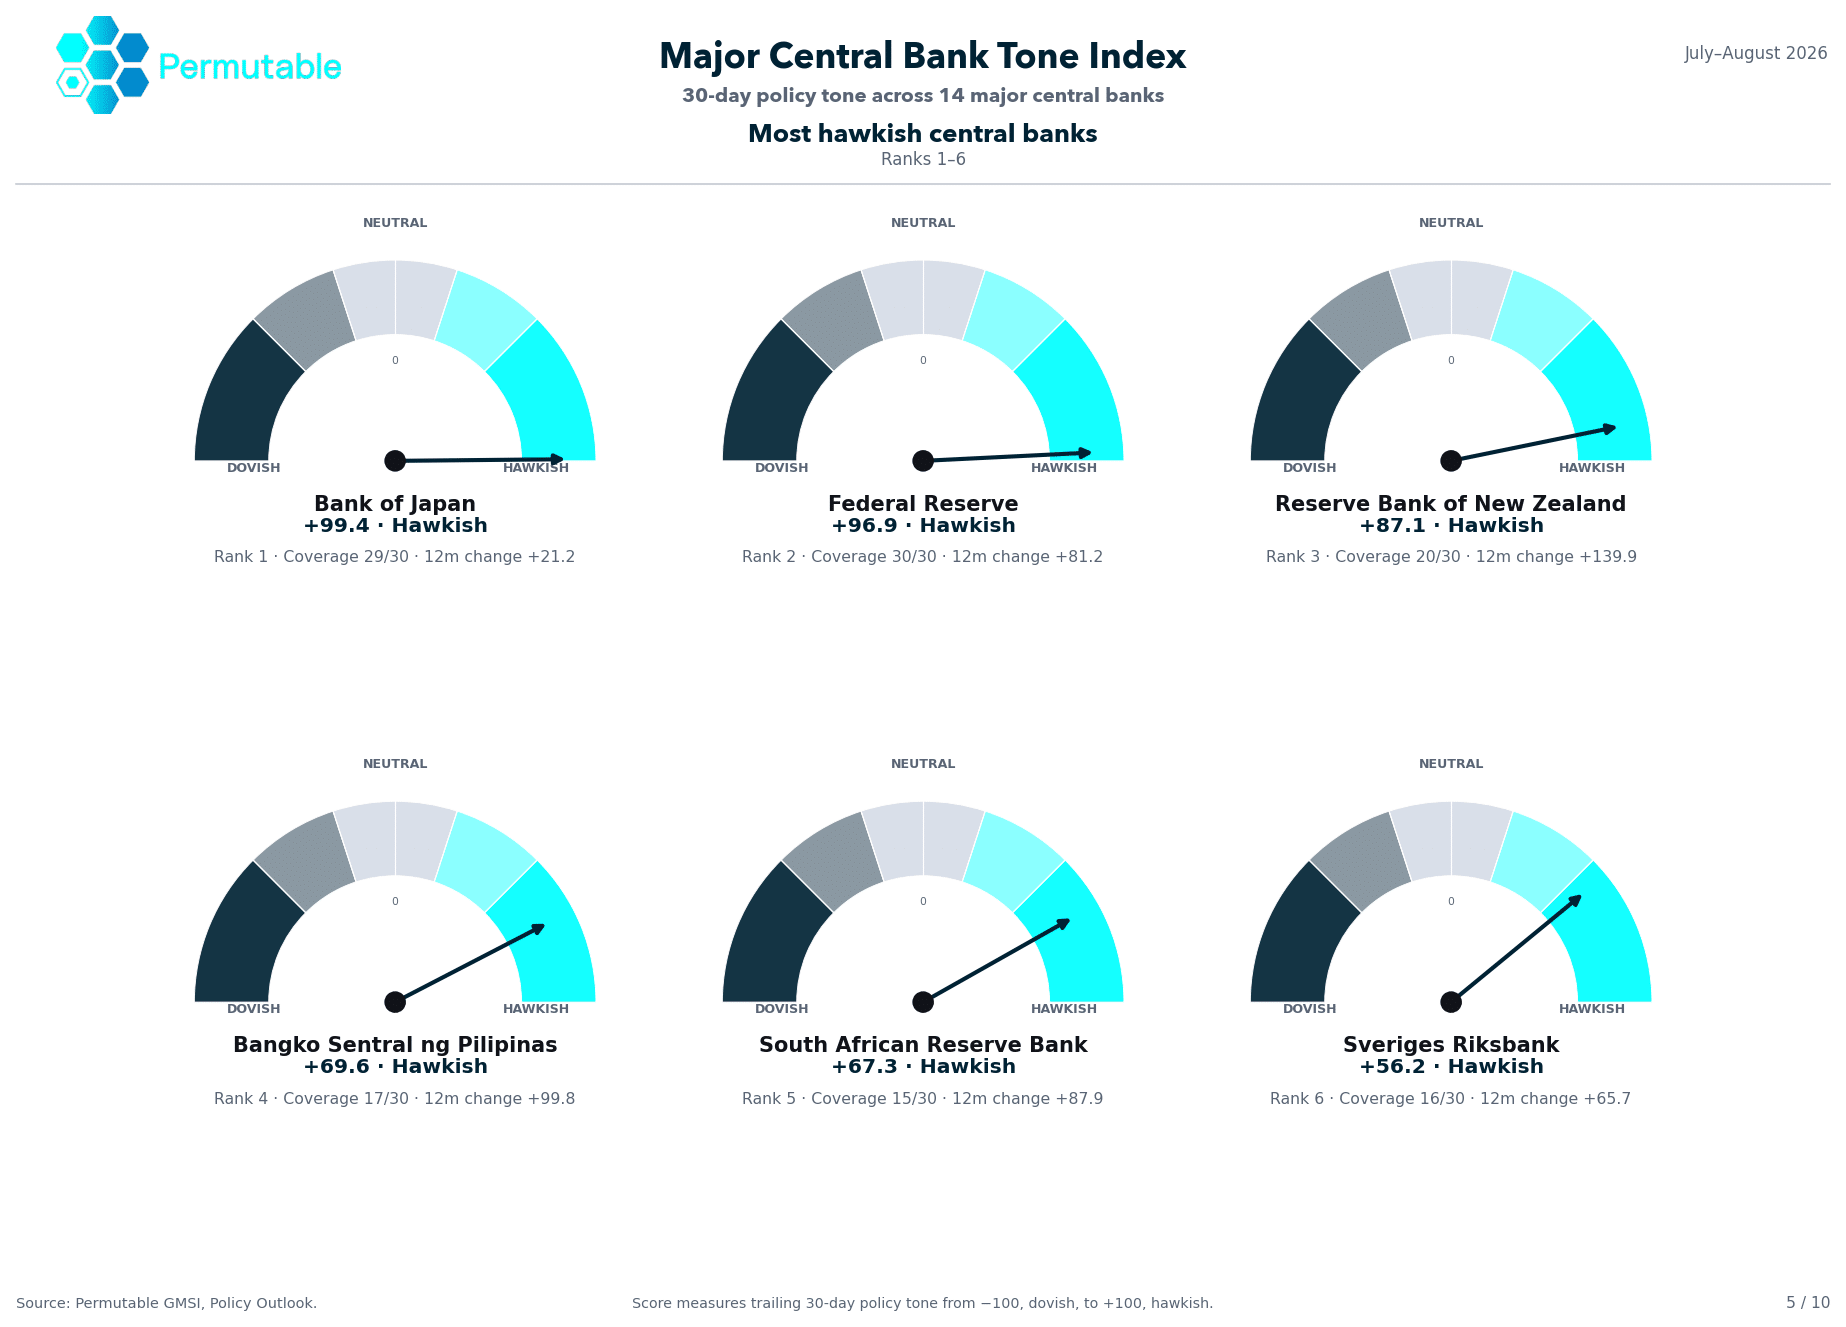
Permutable chart ranking the six most hawkish central banks, led by the Bank of Japan at +99.4, Federal Reserve at +96.9 and Reserve Bank of New Zealand at +87.1, with the Philippines, South Africa and Sweden also in positive territory.
The strongest readings in the central bank policy outlook come from Japan and the United States.
The Bank of Japan scores +99.4 on 29 of 30 qualifying coverage days, the highest reading in the monitor and close to the practical ceiling.
The Bank held its policy rate at 1% on 31 July, voting eight to one, with Hajime Takata pushing for an immediate increase to 1.25%.
Japan’s relatively modest twelve-month sentiment change of +21.2 needs to be viewed in context. Tightening has already dominated the Japanese policy discussion for much of the past year and the Bank has acted on it.
The July hold followed the move to 1% in June, itself the second increase in six months after the December 2025 rise to 0.75%. Japan is therefore different from the Fed and the Bank of England: its policy debate has moved hawkish while actual policy has tightened too.
The currency has also become part of the same policy equation. Japan and the United States are reported to have intervened jointly on 31 July after the yen weakened towards multi-decade lows. Official Japanese intervention data covering that period is not published until 28 August.
Intervention addresses the exchange rate itself but does not remove the interest-rate differential behind it. Renewed yen weakness could raise imported costs and rebuild the domestic tightening case, which is why September has returned to the policy discussion.
The Federal Reserve scores +96.9 on all 30 qualifying days, giving it the deepest evidence base in the monitor alongside Japan’s near-complete coverage.
Its twelve-month change of +81.2 shows how dramatically the policy debate has changed.
The FOMC held its target range at 3.50–3.75% on 29 July, with three dissents in favour of an immediate quarter-point increase. It was a fifth consecutive hold.
Unlike Japan, the Fed has not tightened at any point in the twelve-month window. Its most recent move was in the opposite direction: a quarter-point cut in December 2025, the third of that year.
Twelve months ago, coverage was weighted towards the timing of the next cut, and the Committee duly delivered one. It is now weighted towards whether firm inflation and solid activity warrant an increase.
The unchanged target range therefore conceals a substantial change in the central bank policy outlook, and one that points in the opposite direction to the Fed’s last actual decision.
New Zealand ranks third at +87.1 and records the largest twelve-month move in the monitor at +139.9.
The Reserve Bank of New Zealand took its official cash rate to 2.50% in July, its first increase in over three years, and indicated that some further reduction in monetary stimulus is likely to be required.
That reading rests on 20 qualifying coverage days, at the lower end of what the monitor treats as a robust evidence base, so it carries less depth than the Japanese and US readings above it.
The Philippines, South Africa and Sweden complete the top six on thinner evidence still: 17, 15 and 16 qualifying days respectively.
Sweden’s +56.2 reading, for example, represents the balance of roughly half of the 30-day window. It should therefore not carry the same weight as a reading supported by 29 or 30 qualifying days.

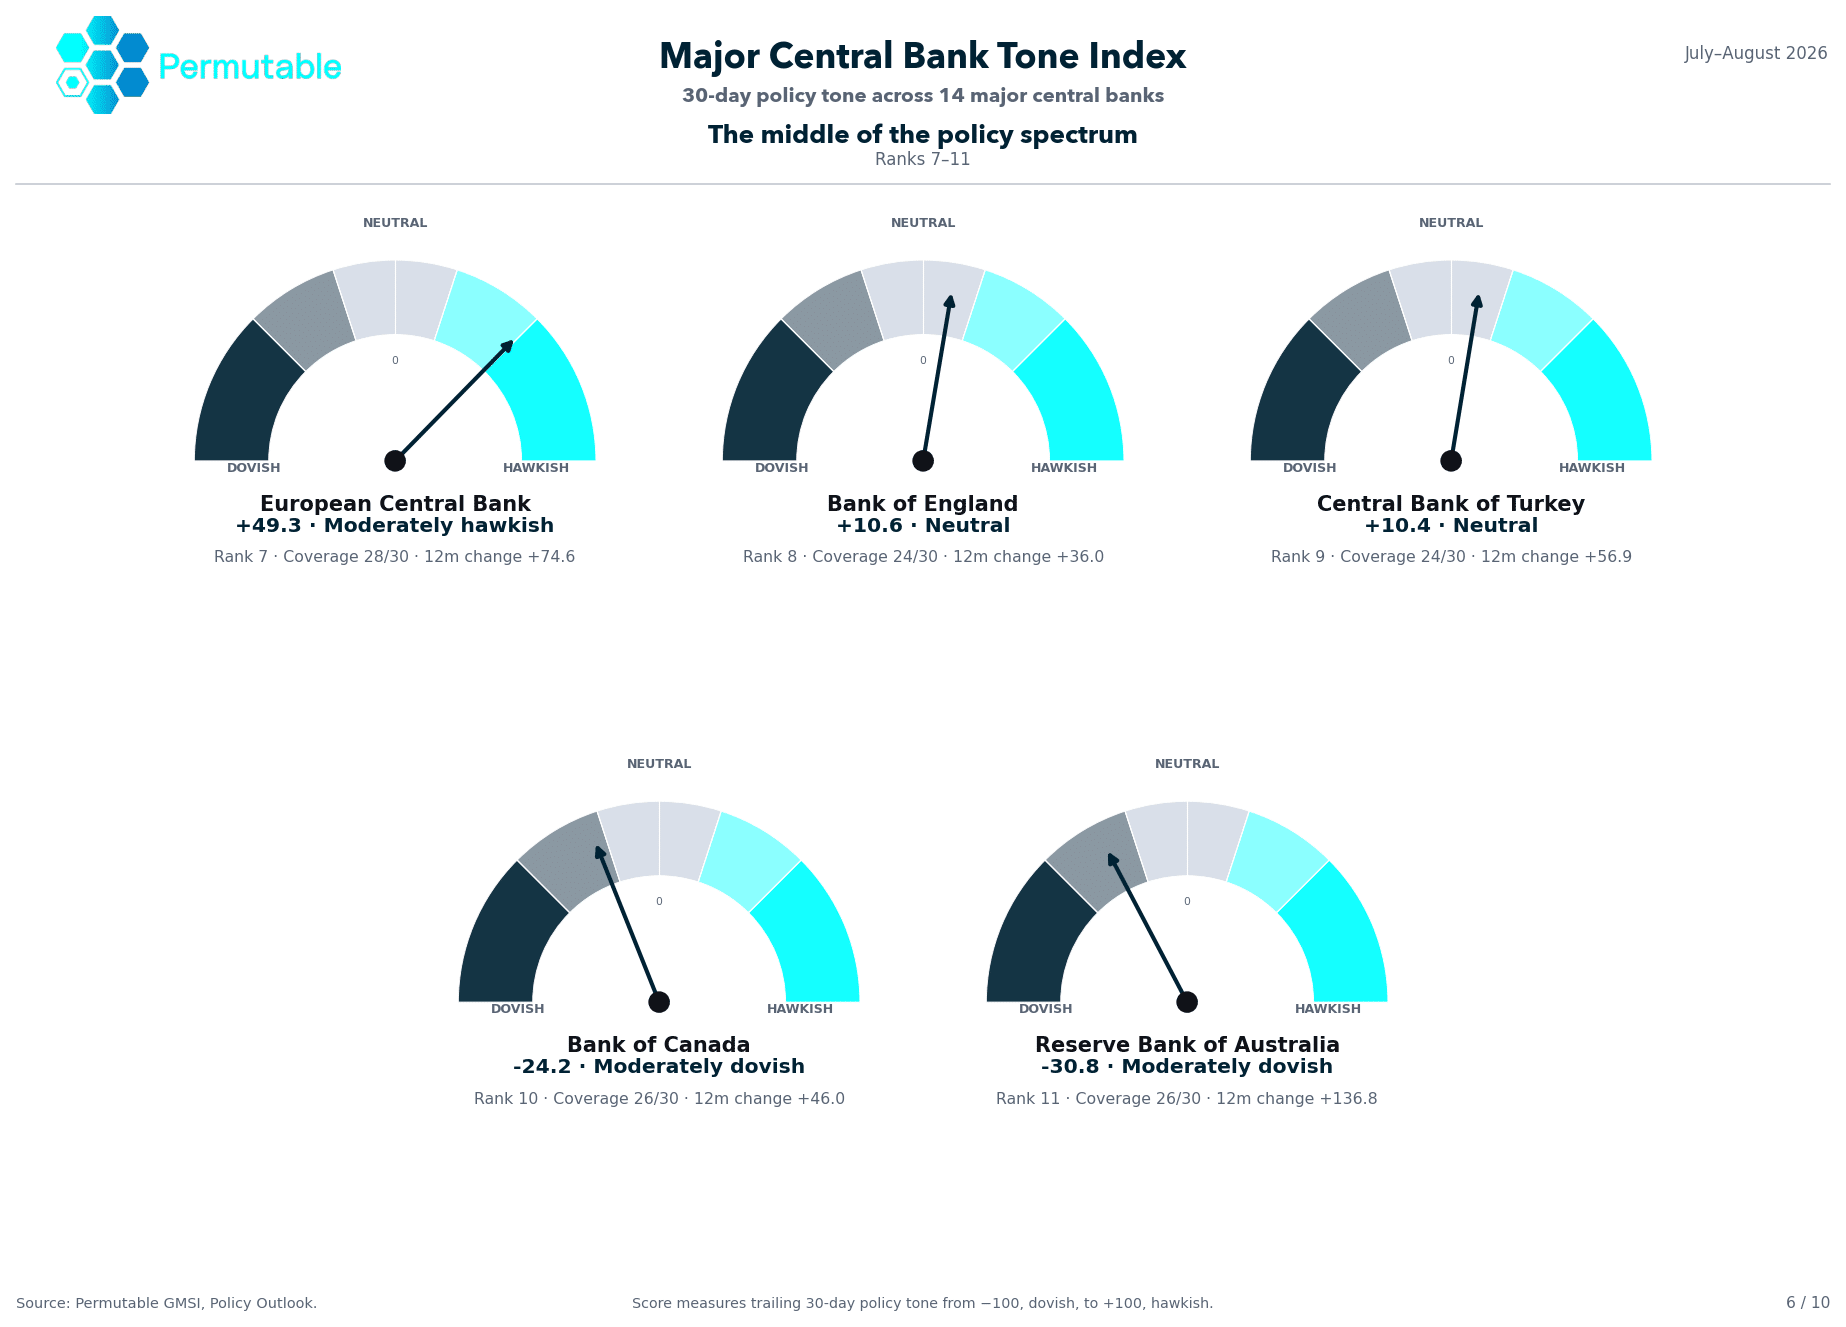
Permutable chart showing the middle of the central bank policy spectrum, with the ECB at +49.3, Bank of England at +10.6, Turkey at +10.4, Canada at −24.2 and Australia at −30.8.
Near-zero readings in the Major Central Bank Sentiment Index should not automatically be interpreted as policy inactivity.
The Bank of England and Turkey sit at +10.6 and +10.4 respectively. In both cases, the near-neutral reading represents a genuine split.
The Bank of England held Bank Rate at 3.75% by six votes to three, with the minority favouring 4%. Underlying disinflation is pulling policy in one direction while energy costs pull in the other.
Its twelve-month change of +36.0 shows which side of that argument has gained ground. As with the Fed, that shift has taken place against a rate that has not moved since the December 2025 cut to 3.75%.
Turkey also sits close to neutral despite a policy rate of 37%, held for a fourth consecutive meeting in July. The central bank continues to emphasise tightness until price stability is secured, while weaker demand has reopened the question of when cuts can begin.
The index measures the path of the policy debate from here, rather than the absolute degree of restriction already in place.
The European Central Bank sits at +49.3, up 74.6 points over twelve months and well ahead of the rest of the middle group.
It is also one of only two central banks in the monitor whose hawkish shift in sentiment has already been matched by policy. The July hold at a 2.25% deposit rate came six weeks after a rise in June, the ECB’s first increase in almost three years and the first by a major Western central bank in this cycle.
The Governing Council said in July that the inflationary impact of the latest energy shock had not fully passed through. The duration of that shock is key.
Energy prices that remain elevated for several quarters can stop behaving like a temporary relative-price adjustment and begin feeding into wages and contracts.
At that point, policymakers have less room simply to look through the shock, potentially shifting the central bank policy outlook further towards the hawkish side.
Canada and Australia illustrate why the current index level and its trajectory need to be read together.
Canada sits at −24.2, but has moved +46.0 points in a hawkish direction over twelve months.
The Bank of Canada held its policy rate at 2.25% on 15 July, a sixth consecutive hold, describing the setting as appropriate for supporting the recovery while inflation returns towards target. Its last move, like the Fed’s and the Bank of England’s, predates the current hold streak that began in December.
Australia is more striking. The Reserve Bank of Australia remains moderately dovish at −30.8, but its twelve-month shift is +136.8, the second largest in the entire monitor.
Headline inflation eased from 4.0% in May to 3.8% in June, reducing some urgency around another increase. Trimmed-mean inflation remained at 3.6%, however, still above the RBA’s band.
Australia therefore remains dovish on the level while having travelled a considerable distance towards the hawkish end.

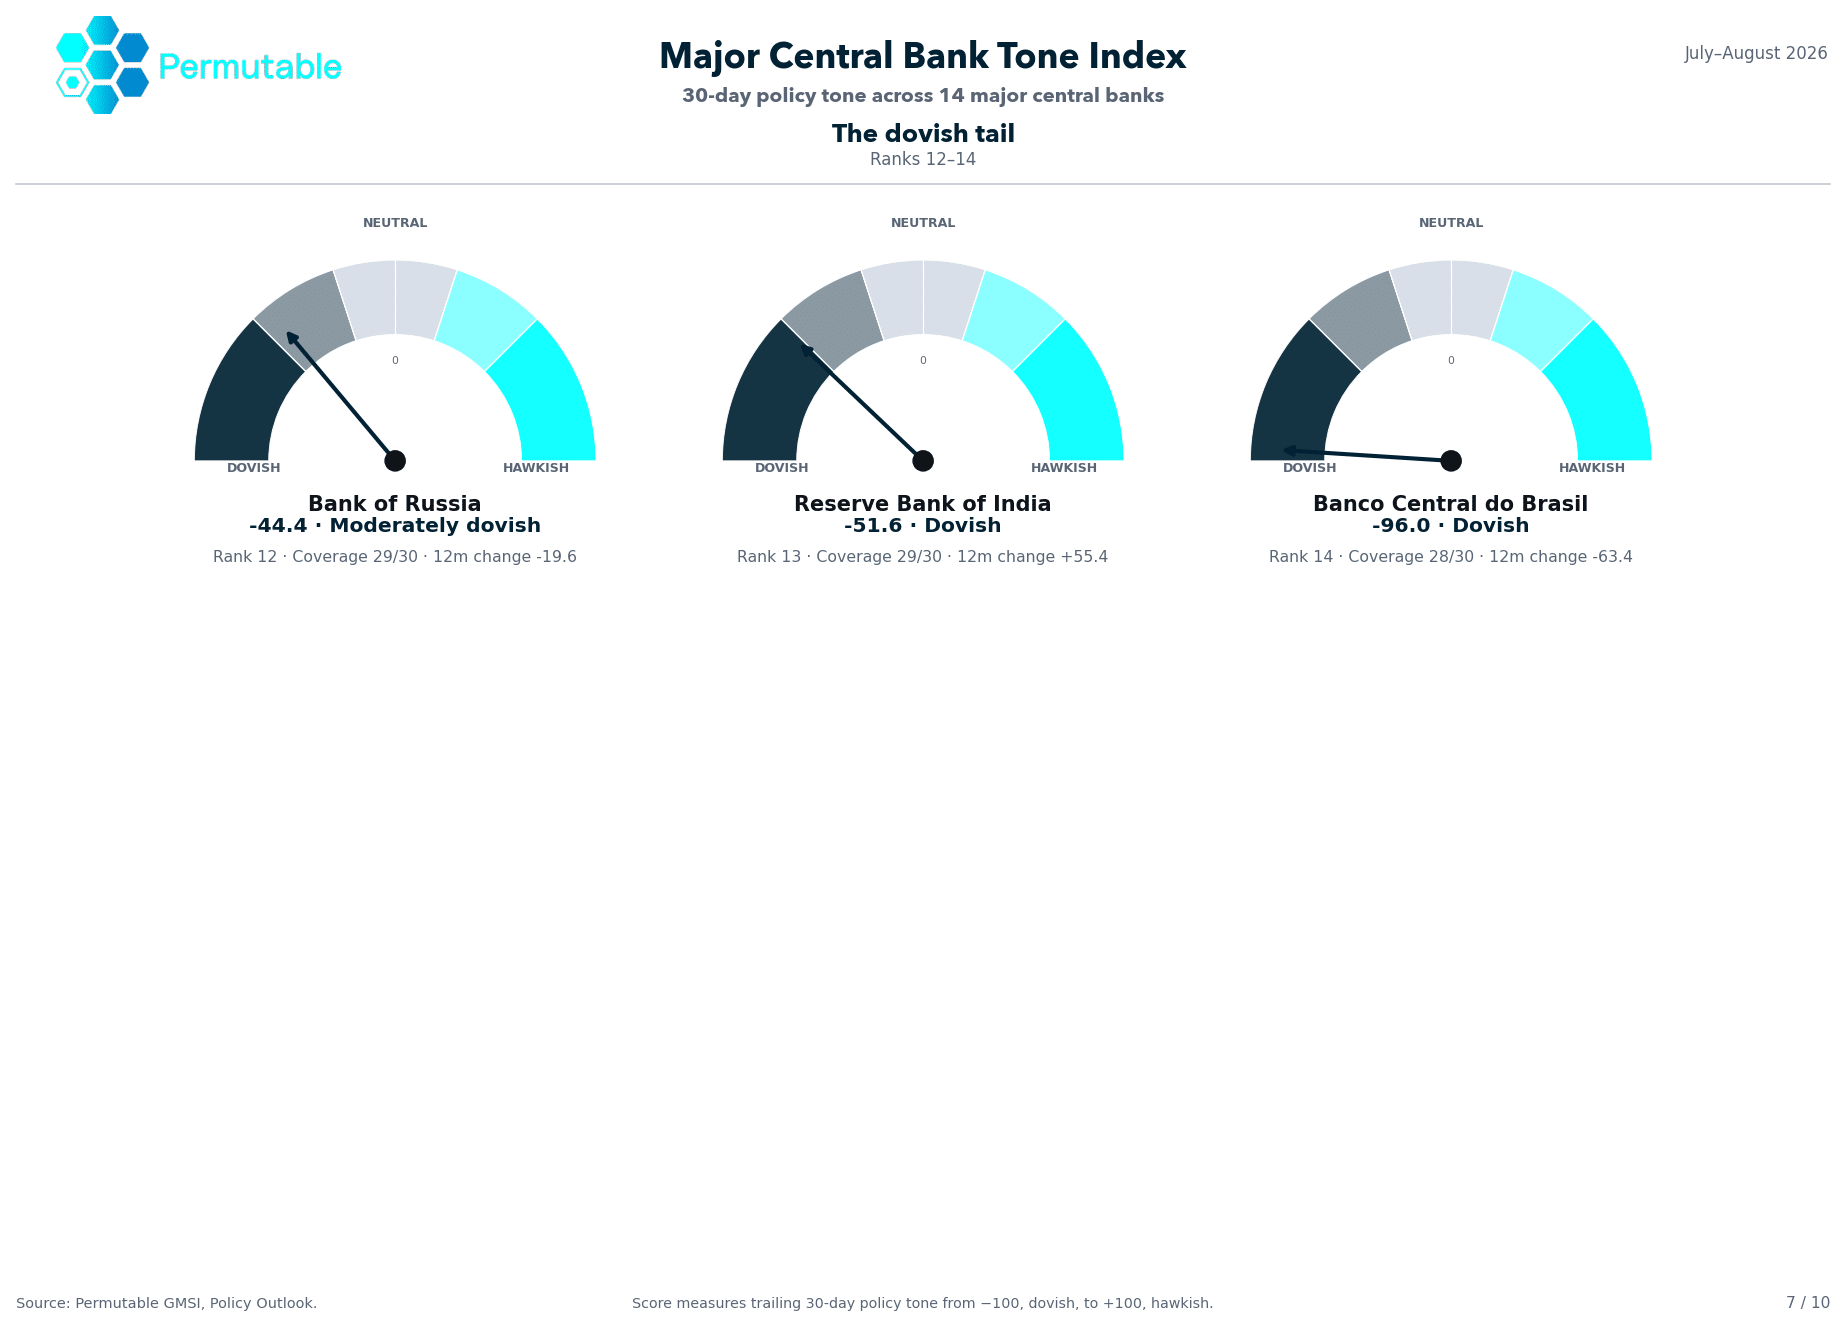
Permutable chart showing the dovish end of the Major Central Bank Sentiment Index, with the Bank of Russia at −44.4, Reserve Bank of India at −51.6 and Banco Central do Brasil at −96.0 over the 30 days to 6 August 2026.
India is the clearest example of a dovish current reading masking a more hawkish longer-term move.
The Reserve Bank of India sits at −51.6, with a twelve-month change of +55.4.
That is the widest gap anywhere in the monitor between the current level and the direction of travel.
The RBI held its repo rate at 5.25%, maintained a neutral stance and lowered its full-year inflation projection, assessing much of the recent inflation pressure as food- and fuel-related.
This pushes the immediate tightening question further out without changing the formal policy stance.
India is not signalling an imminent hike. The significance lies in how far policy-outlook sentiment has moved relative to where it stood twelve months ago.
Banco Central do Brasil remains the strongest dovish signal in the monitor at −96.0.
Copom cut the Selic rate to 14% on 5 August as inflation and activity softened.
The communication nevertheless remained cautious. Inflation expectations are still above target, the labour market remains firm and fiscal risk continues to feature in the assessment.
None of those qualifications has yet materially altered the easing story.
Brazil is also one of only two central banks whose policy-outlook sentiment has moved more dovish over twelve months. The other is Russia.
The Bank of Russia scores −44.4, down 19.6 over the year, after cutting its policy rate by 25 basis points to 14%. It simultaneously lifted its 2026 inflation forecast to 6–7% and highlighted rising inflation expectations, suggesting a potentially slower pace of subsequent easing.
Three conclusions emerge from the complete cross-section.
At the hawkish edge, Japan and the United States are being covered almost entirely through the question of the next hike, supported by the two deepest evidence bases in the monitor.
Across the contested middle, near-neutral readings contain some of the most active policy debates, particularly where energy costs are competing with softer demand and cooling labour markets.
And across the complete ranking, 12 of 14 twelve-month changes point towards the hawkish end, while only two of the fourteen have so far translated that shift into a rate increase.
The distribution has widened, but it has widened while the cross-section as a whole has also shifted more hawkish.
Three channels have the potential to shift several central banks simultaneously.
Japan’s reading is already pinned at +99.4, leaving almost no room for the headline score itself to register further hawkish pressure.
That makes the depth and persistence of the underlying coverage increasingly important.
If the yen weakens again, imported costs could feed into domestic prices and make September the first meeting forced to deal directly with renewed inflation pressure.
The key variable is not intervention alone, but the rate differential that produced the currency move.
The ECB has already said that the latest energy shock has not fully passed through, and has already raised once in response to it.
Canada, Australia and the UK also sit in the middle of the distribution, where softer demand is competing with energy-related inflation pressure.
A shock that persists for several quarters could move several central banks together.
For rates portfolios, a correlated move across the middle of the distribution may prove more consequential than one further hawkish surprise from a central bank already at the top.
India sits at −51.6 despite a +55.4 twelve-month shift. Australia has the same broad shape, with a +136.8 shift sitting behind a current dovish reading.
Neither is necessarily close to hiking.
But the dovish end of the distribution is thinner than the ranking alone suggests, leaving Brazil increasingly isolated at the extreme.
Permutable’s Major Central Bank Sentiment Index measures directional policy-outlook sentiment over a trailing 30 days for 14 major central banks.
Scores range from −100 to +100:
The window in this report ends on 6 August 2026.
Each observation is point-in-time. A historical score reflects only information available on that date, with no subsequent revision, allowing the series to be replayed systematically in a backtest.
Coverage days record how many of the 30 days contained qualifying policy coverage.
Readings based on fewer than 20 days should be treated more cautiously. In this window, those are:
New Zealand sits at the threshold with 20 days.
The twelve-month change compares the current score with the same trailing measure one year earlier.
The index measures the balance of the policy debate. It is not a probability attached to the next policy decision and is not a forecast of the policy rate.
Permutable’s Global Macro Sentiment Indices convert global information into hourly, point-in-time macro sentiment signals across more than 95 economies and 70 macro topics.
Every observation is historically preserved and traceable to its underlying drivers, supporting live monitoring and systematic replay from the same record.
A macro, rates or FX research desk can therefore test whether a turn in policy sentiment appeared before the vote that confirmed it, how broadly the change spread across the central-bank cross-section, and where it subsequently appeared in rates and currencies.
Access the complete five-page analysis of 14 major central banks, including the Major Central Bank Sentiment Index rankings, directional policy-outlook sentiment, twelve-month changes, coverage depth and implications for rates and currencies.
This analysis explains how investors can identify macro regime shifts before official data fully confirms them. Using Permutable signals from Japan, Turkey and Brazil, it examines persistent JGB repricing, transitions into and out of high-inflation environments, and changes in central-bank reaction functions. It is written for macro portfolio managers, rates and FX desks, economists, strategists and systematic researchers globally today.
Macro regime shifts rarely arrive with a clean announcement. By the time an inflation regime, policy cycle or rates repricing is obvious in official data, much of the market adjustment may already have taken place. The harder task for investors is to identify when the relationship between data, policy language and asset prices has begun to change – and whether that change is likely to persist.
Japan, Turkey and Brazil show three different versions of the same problem. In Japan, cooling monetary-policy sentiment has not been matched by a return to the old JGB yield range. In Turkey, falling headline inflation is not enough to prove that the high-inflation process has broken. In Brazil, the key signal is not the level of the SELIC rate, but whether the central-bank reaction function is shifting from one policy narrative to another.
This article uses Permutable’s Global Macro Sentiment Indices to examine how regime shifts can be detected earlier through the interaction of narrative strength, breadth, persistence and market confirmation. The aim is not to treat sentiment as a standalone forecast, but to show how point-in-time macro signals can help investors distinguish temporary noise from a more durable change in the process driving inflation, policy and asset prices.
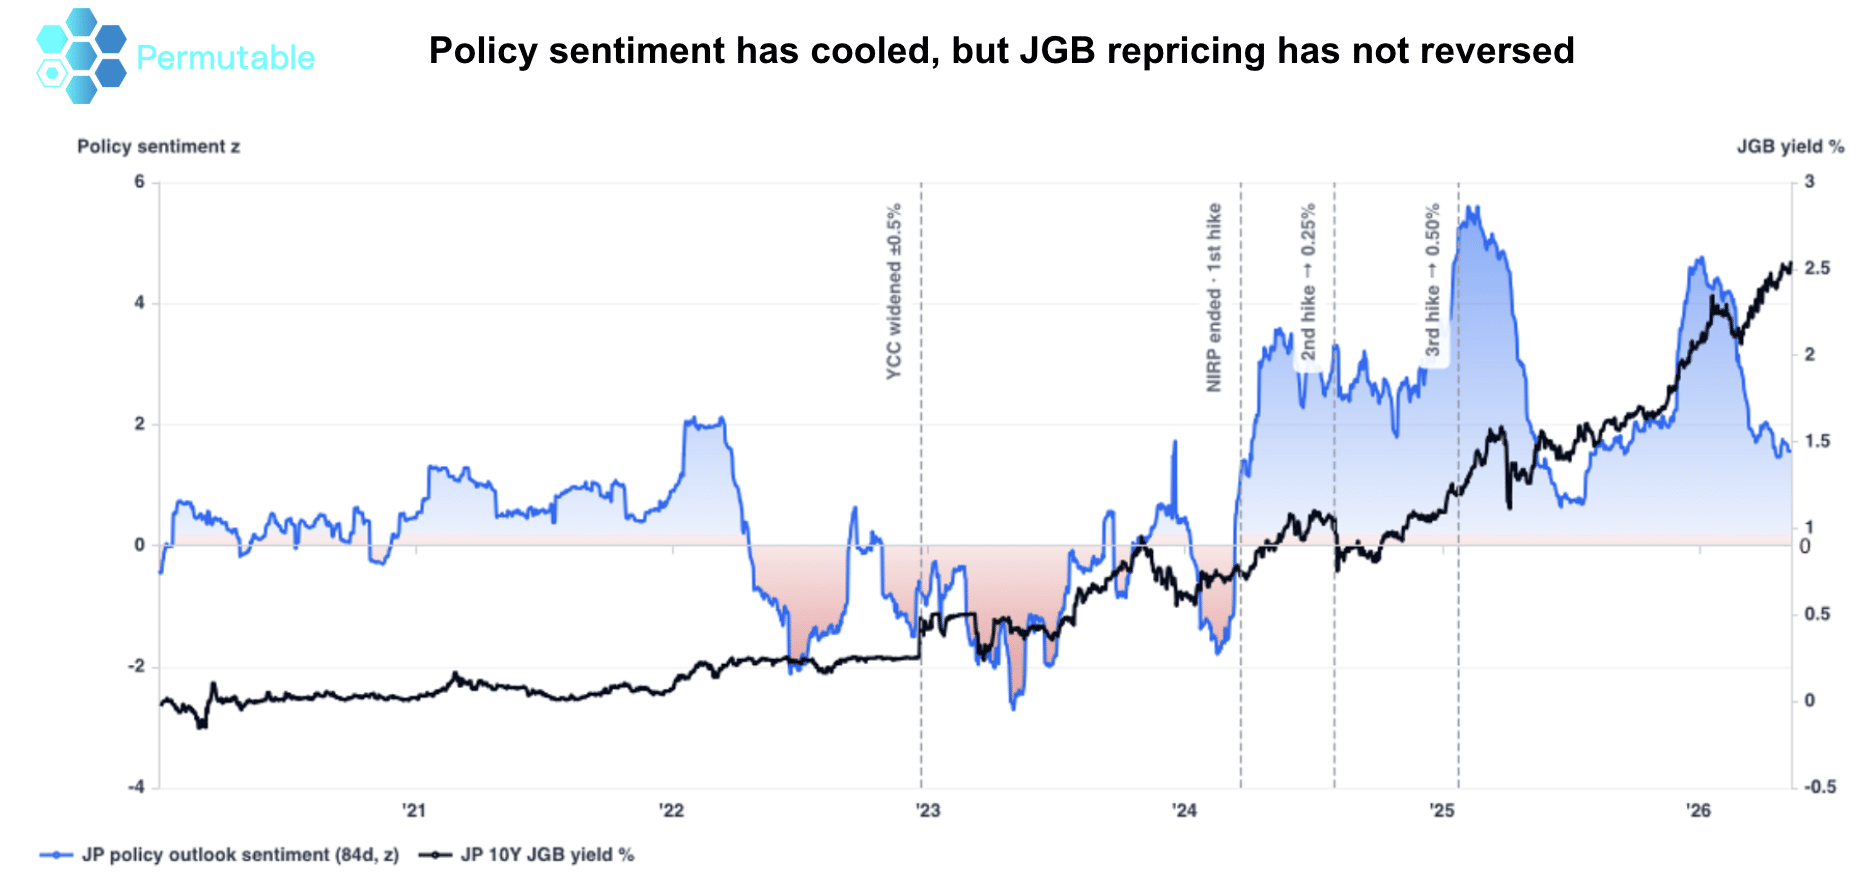
In the case of Japan, monetary-policy narrative has cooled sharply from its 2025 peak. The JGB market has not followed it back.
Permutable’s Japan policy-outlook sentiment measure had fallen from the extreme hawkish readings reached around the Bank of Japan’s third rate increase. Yet the 10-year JGB yield continued towards 2.5 per cent rather than returning to the range that prevailed under yield curve control.
That divergence is the signal. It suggests the market is no longer treating the exit from ultra-loose policy as a temporary adjustment. It is pricing a different monetary regime.
Macro shifts are often recognised too late because analysis focuses on levels rather than relationships. A high inflation print, a rate increase or a sharp bond move may be important, but none establishes a new regime alone. The regime changes when the process connecting inflation, policy and asset prices changes – and stays changed.
This is consistent with James Hamilton’s regime-switching framework, which treats major economic breaks as changes in the process generating the data rather than ordinary fluctuations around a stable trend.
For years, Japan’s rates market was organised around a clear policy anchor. Negative short-term rates, large-scale JGB purchases and yield curve control constrained borrowing costs and suppressed the long end.
In March 2024, the Bank of Japan ended negative interest rates and yield curve control. It shifted to a framework in which the short-term interest rate once again became the primary policy instrument.
The chart shows that the transition occurred in stages.

Policy sentiment was mostly positive through 2020 and 2021 without producing a durable break higher in yields. It weakened during 2022 and 2023, even as the Bank allowed greater flexibility around the 10-year yield target. The decisive change came around the end of negative rates in early 2024. Policy sentiment moved sharply higher and remained elevated through subsequent rate increases.
The peak itself is not the strongest evidence of regime change. What followed is more revealing.
Policy sentiment has since fallen from close to five standard deviations at its extreme to around 1.5 on the latest reading. The 10-year JGB yield had not returned to its pre-normalisation range. It continued to rise.
That is the difference between a cyclical policy signal and a structural repricing. A cyclical signal should reverse as the immediate hawkish impulse fades. A regime shift leaves behind a new market-clearing level because investors have changed their assumptions about inflation persistence, the equilibrium rate, policy tolerance or the supply of duration.
The chart can’t identify which of those explanations is dominant – nor should it be read as proof that policy sentiment caused the move in yields. However, it does show that cooling policy language has not restored the old relationship between the narrative and the curve.
For a rates desk, the relevant question is therefore not whether the Bank sounds less hawkish than it did at the peak but what evidence would be required for the market to price the old regime again.
A sustained collapse in inflation and wage pressure, a clear dovish shift in Bank communication and a reversal across the curve would weaken the regime interpretation. So far, the chart shows cooling sentiment without that market reversal.
Turkey demonstrates why the same distinction is key in inflation analysis.
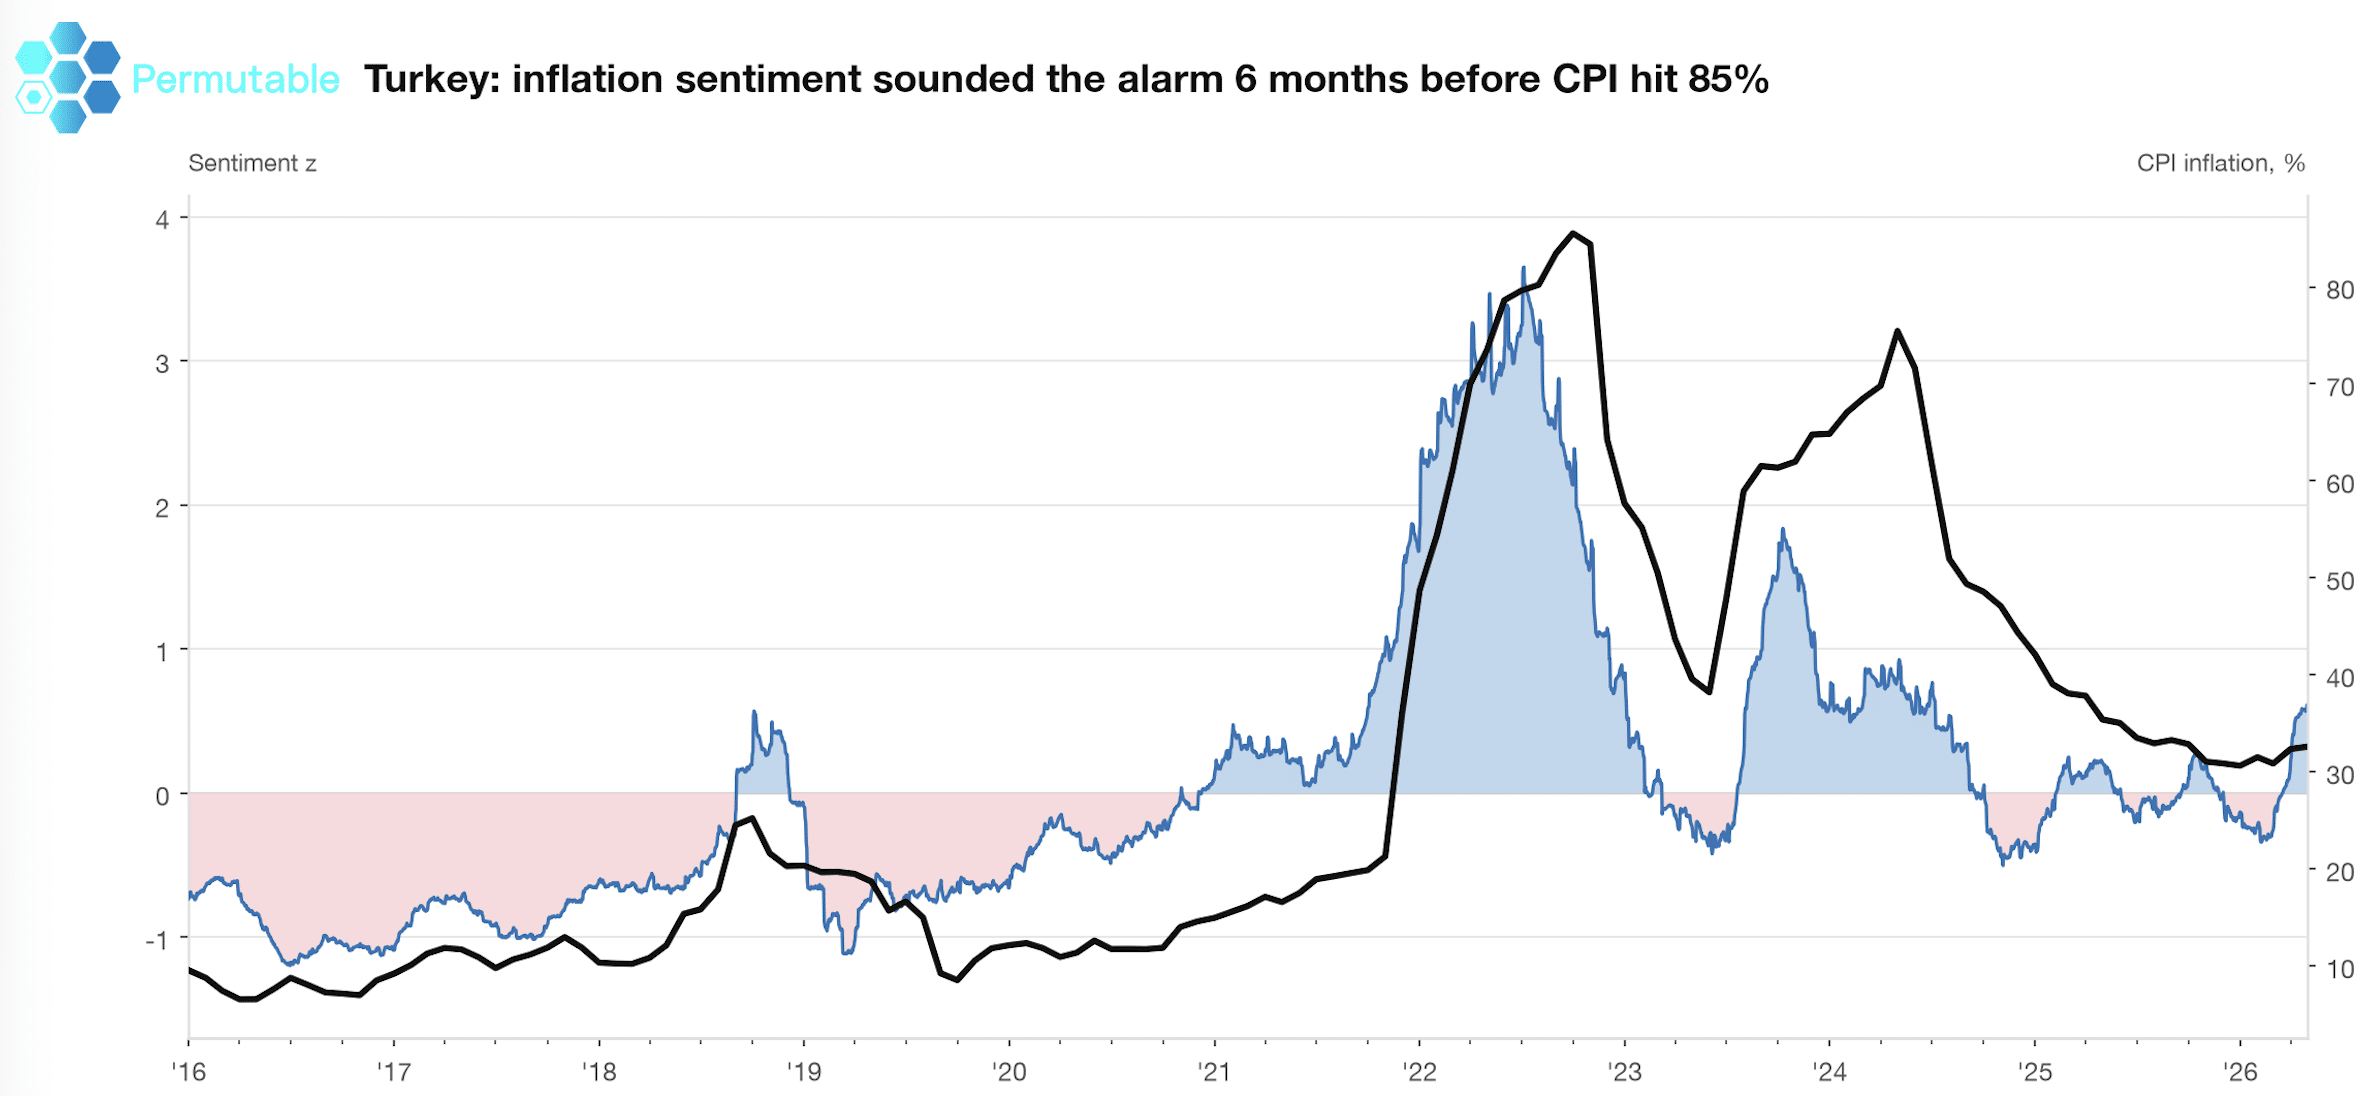
Permutable’s Turkey inflation signal helps differentiate between an economy remaining inside a high-inflation regime and one beginning to leave it. Annual CPI can fall because of base effects while the forces sustaining inflation remain active.
Currency weakness, wage resets, administered-price increases and household expectations can continue reinforcing one another after headline inflation has peaked. A lower annual rate is therefore not sufficient evidence of a durable transition.
A turn becomes more credible when several channels change together. Local reporting begins to indicate weaker pass-through. Pricing pressure loses breadth. Demand softens. Policy credibility improves. Inflation sentiment falls and remains lower rather than rebounding after one favourable release.
The investment question is not simply whether inflation has declined, but whether the system producing inflation has changed.
Our analysis of Turkey, Brazil and Nigeria applies this regime-based approach to emerging-market inflation, separating changes in headline data from changes in the underlying inflation process.

Brazil offers a policy-cycle version of the same problem.
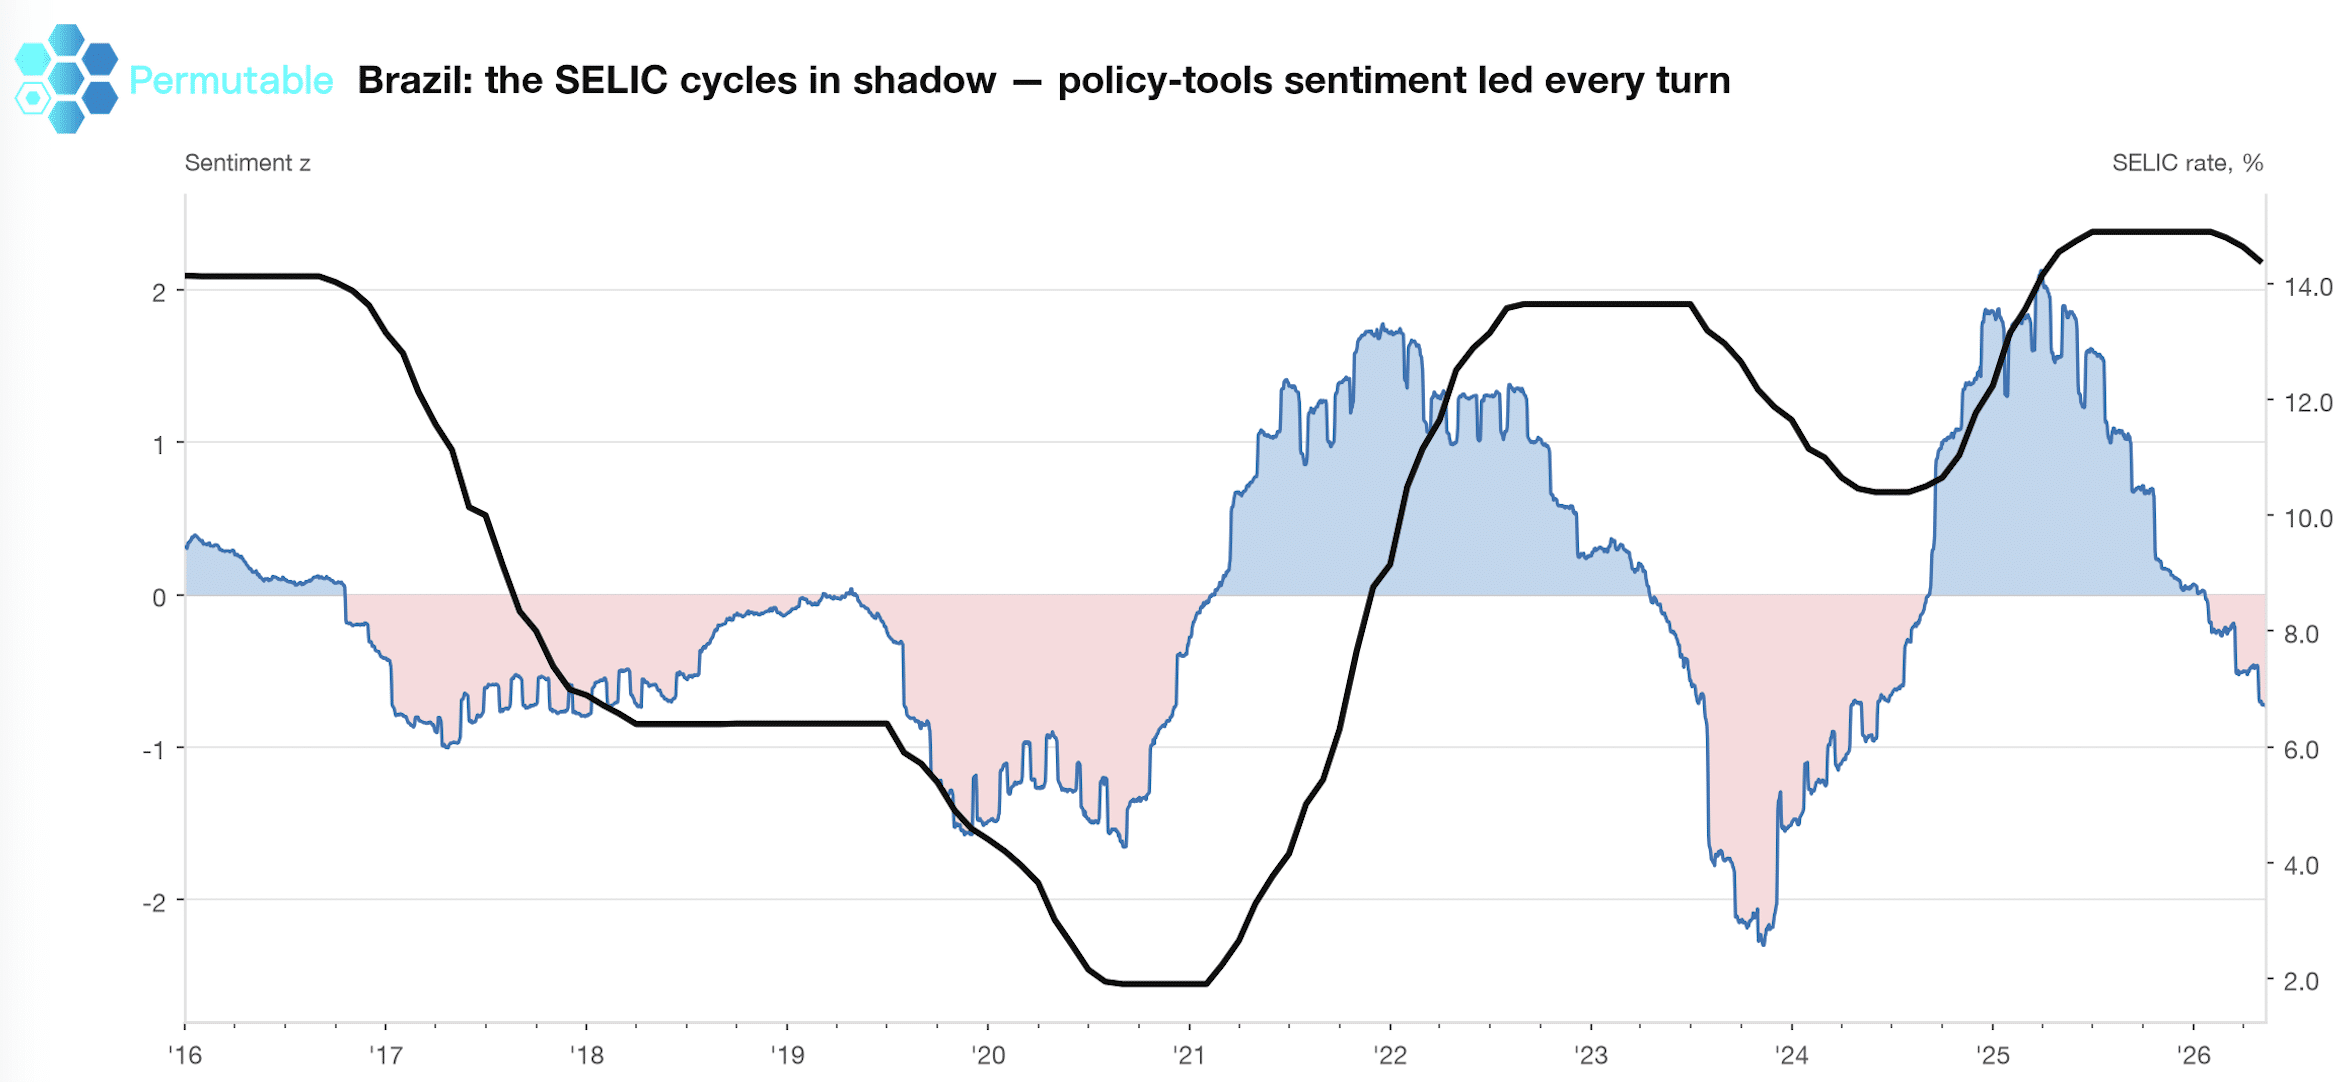
Permutable’s Brazil policy sentiment has alternated between hawkish and dovish phases as the balance between inflation, growth, fiscal risk and the scope for easing has changed. The turning points are key because they show when one policy narrative is losing control and another is becoming dominant.
This is not the same as predicting the next SELIC decision.
A central bank can continue cutting rates within a relatively hawkish environment if its communication stresses limited room to ease, fiscal uncertainty or renewed inflation risk. Equally, a high nominal rate can coexist with a genuinely dovish transition when the debate moves towards a sustained easing cycle.
The regime signal lies in the reaction function – how policymakers are likely to respond to the same incoming data – rather than in the current level of the policy rate.
For rates and FX investors, that distinction can help separate a temporary repricing around one meeting from a broader change in the expected direction, pace and limits of the policy cycle.

Across Japan, Turkey and Brazil, four tests are key:
– Direction – has the signal moved decisively away from its previous range?
– Breadth – is the change visible across multiple drivers, sources and parts of the economy?
– Persistence – does it survive beyond one release, policy meeting or market shock?
– Confirmation – is the shift also becoming visible in market pricing, forecast revisions or hard data?
News-based indicators are most useful as an early information layer, not as stand-alone trade instructions. ECB research has found that newspaper sentiment contains timely economic information that can materially improve euro-area GDP nowcasts. New York Fed research similarly demonstrates the value of synthesising large, mixed-frequency datasets as new information arrives.
Historical testing must also be conducted on a point-in-time basis. Revised economic series and retrospectively reconstructed narratives can make turning points appear far cleaner than they were to investors at the time.
Permutable’s Global Macro Sentiment Indices provide country- and topic-level signals, distinguish domestic from international narratives and preserve the point-in-time history required for systematic testing. Their interpretation can be strengthened through formal regime-detection methods, including Markov-switching or hidden Markov models, which estimate whether sentiment is operating within a low-pressure, transitional or high-pressure state.
In the Japan chart, the 84-day z-score measures the current policy-outlook reading relative to its recent distribution. A regime model can assess whether that movement represents a temporary deviation or a more persistent change in the underlying narrative. For genuine point-in-time testing, the classification should rely on filtered regime probabilities calculated using only information available on each date, rather than smoothed probabilities estimated with the benefit of later observations.
The signal therefore captures the strength, direction and persistence of the policy narrative, while the regime classification provides a systematic test of whether its behaviour has materially changed. Neither should be interpreted as a forecast of the next Bank of Japan decision, proof of causality or, in isolation, a trading signal.
Use Permutable’s Global Macro Sentiment Indices to track changes in inflation, growth and monetary-policy narratives across more than 95 economies.
Point-in-time history supports regime modelling, historical testing and systematic research without hindsight, while continuously updated signals help investors assess whether an emerging change is broadening, persisting and gaining confirmation across markets and official data.
Explore how GMSI can support regime classification, rates and FX research, macro nowcasting and cross-country analysis
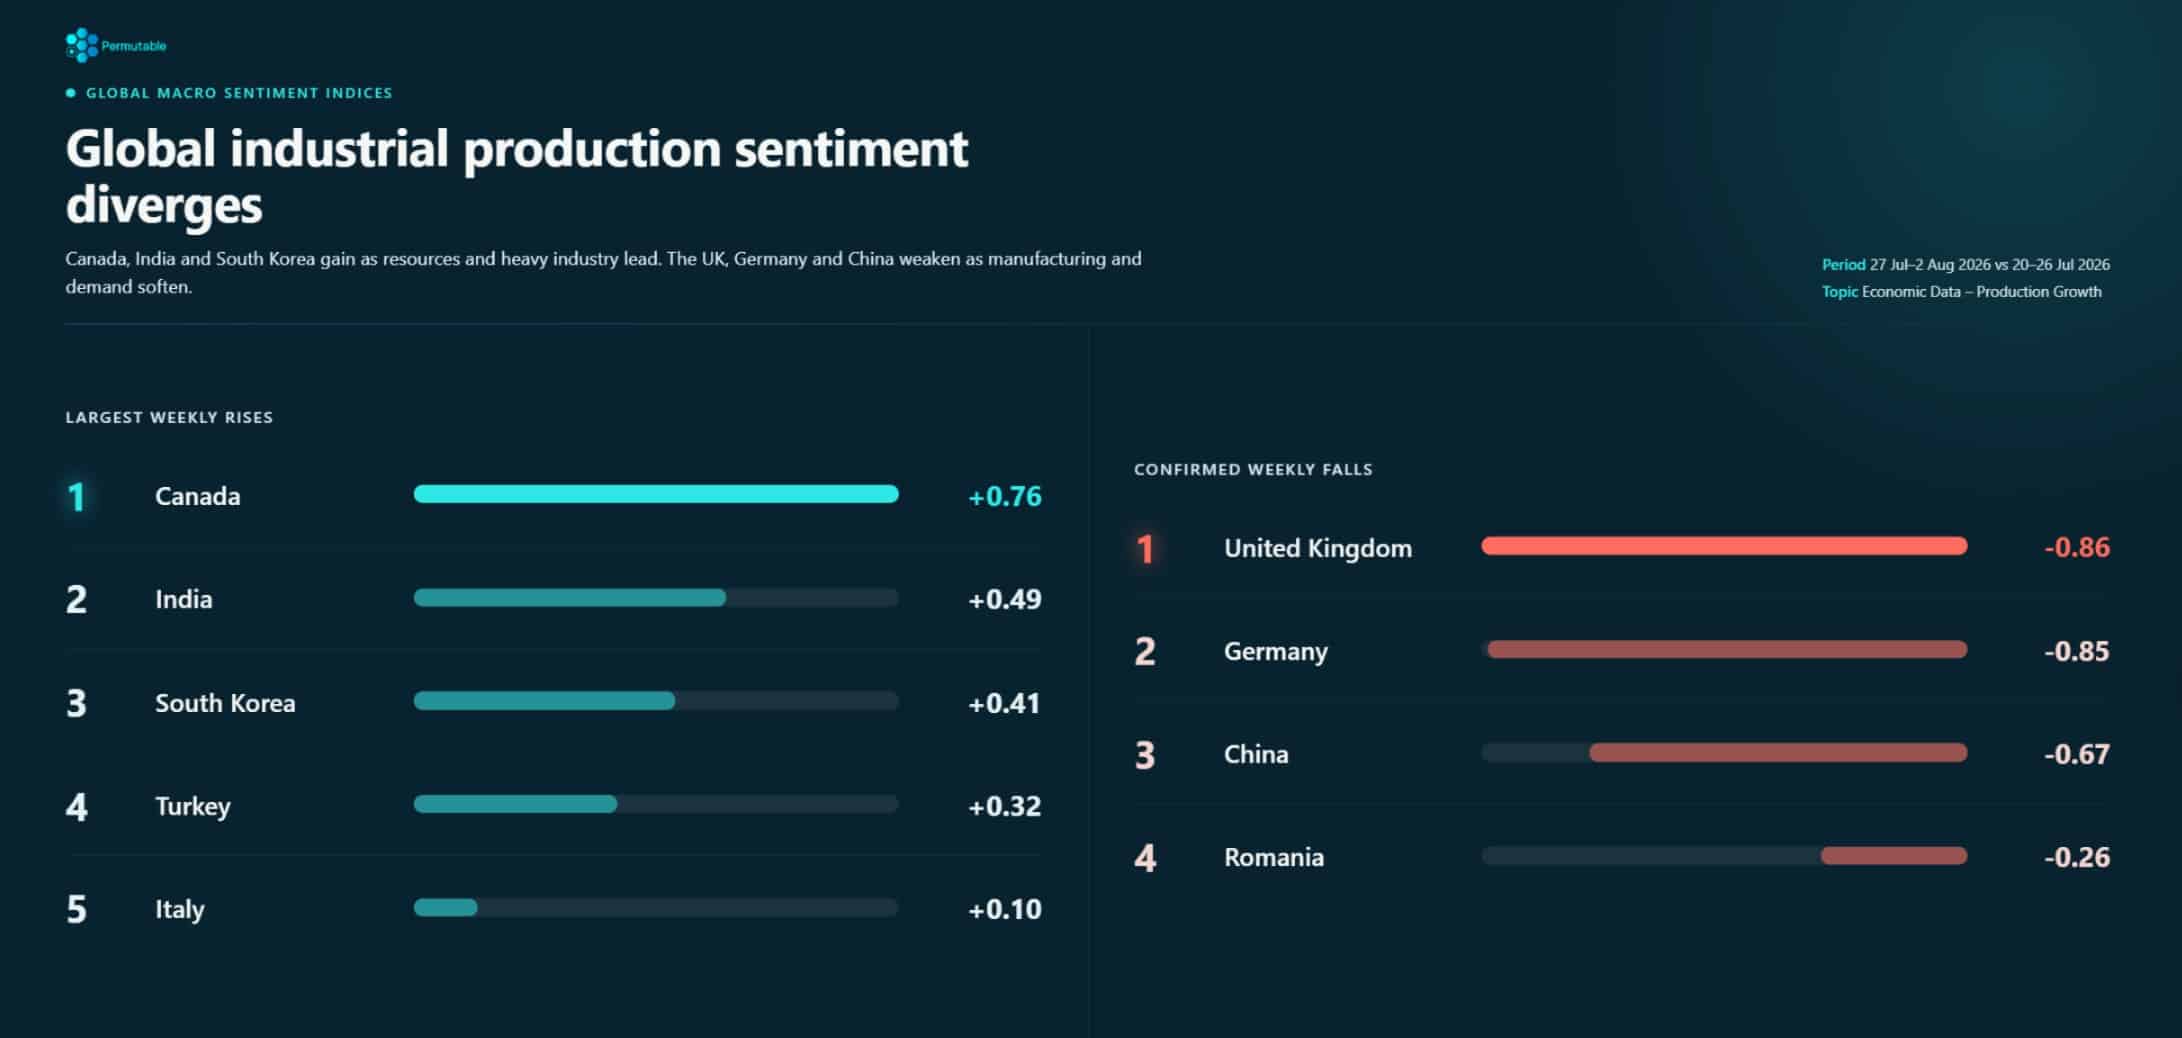
This analysis uses Permutable’s Global Macro Sentiment Indices (GMSI) to track shifts in industrial-production sentiment across major economies in 2026. It shows heavy industry gaining momentum in Canada, India, South Korea and Turkey, while the UK, Germany, China and Romania weaken. It is aimed at institutional investors, economists, strategists and corporate decision-makers monitoring global manufacturing, commodities, demand and industrial-cycle divergence.

The global industrial cycle has not so much turned as separated.
Permutable’s latest sentiment data shows the strongest GMSI signals have come from economies supplying the physical ingredients of growth: oil, coal, metals and productive capacity. Canada led this week’s rise, followed by India and South Korea. Turkey benefited from steel. Italy, after several false dawns, produced a somewhat firmer run of orders and sales.
The weaker group occupied another part of the factory floor. British vehicle production remained subdued. German industry had tolerable backward-looking data but an increasingly uncomfortable discussion about what comes next. China’s official manufacturing survey slipped below the line separating expansion from contraction in July.
None of this amounts to a synchronised industrial recovery. Mines, mills and power systems can gain momentum while manufacturers dependent on household demand, export orders and competitive pricing continue to wait for theirs.
The rankings compare average directional industrial-production sentiment per matched headline in the seven days ending 2 August with the preceding period, 20-26 July.
An average score is used because America naturally produces more economic news than Romania. That should not, by itself, constitute stronger industrial momentum.
A rising reading means the coverage became more consistently associated with higher production, new capacity or improving operating conditions. A falling one reflects a greater concentration of weak orders, lower output, closures or production constraints.
Countries require at least 15 matched headlines in both periods. A numerical move is published only where the dominant high-impact stories support it. This removes some of the excitement from a top-five ranking, but also some of the fiction.
| Rank | Country | Weekly change |
| 1 | Canada | +0.76 |
| 2 | India | +0.49 |
| 3 | South Korea | +0.41 |
| 4 | Turkey | +0.32 |
| 5 | Italy | +0.10 |
Canada recorded the largest rise as oil, gas and mining displaced the less persuasive parts of its manufacturing story.
This was not a factory renaissance. The improvement came from industries able to turn commodity demand and existing assets into additional production. Oil-sands performance strengthened, mining investment advanced and the resource economy regained its familiar role as the part of Canadian industry prepared to do the heavy lifting.
Commodity exporters are often accused of lacking industrial sophistication. They tend to mind less when commodity prices and investment are moving in their favour.
India’s rise was harder to dismiss as a collection of favourable coal and steel headlines.
Industrial production increased by 7.3% from a year earlier in June. Manufacturing rose by 7.8%, electricity and gas supply by 10.6%, and 19 of the 23 manufacturing groups recorded growth. The composition was as useful as the headline number: energy, capital goods and infrastructure-related production moved together.
India’s industrial story is becoming broader, which is generally preferable to becoming louder. Emerging-market growth releases have never suffered from a shortage of noise.
South Korea recorded one of the clearest improvements in the ranking.
Semiconductors remain central to the economy, as they have an inconvenient habit of being central to almost every discussion of Korean industry. This week’s signal was more interesting. Production strengthened alongside consumption, facility investment and business expectations.
South Korea often turns early in the manufacturing cycle. Whether it also leads the rest of the world is another matter, and usually where the forecast notes become longer.
Turkey’s industrial signal rose as steel and metals outweighed weakness closer to the household sector.
Heavy industry supplied the favourable comparisons, capacity plans and better export narrative. White goods and other interest-rate-sensitive industries remained under pressure. The economy, as ever, managed to contain more than one cycle at the same time.
The result was an industrial expansion with a pronounced lean towards infrastructure and external markets. Turkish households were less involved.
Italy completed the top five with the sort of improvement that requires careful handling.
Industrial production fell by 0.3% in May after three monthly increases, although output remained 1.1% higher than a year earlier. The three months to May were also stronger than the preceding quarter. This is not a boom, nor even much of a rebound. It is, however, better than an unbroken decline.
Italy’s ranking is best read as evidence of an industrial turn under consideration. Confirmation, in the Italian data tradition, can arrive later.
| Rank | Country | Weekly change |
| 1 | United Kingdom | −0.86 |
| 2 | Germany | −0.85 |
| 3 | China | −0.67 |
| 4 | Romania | −0.26 |
Only four countries passed the full evidence test for falling industrial sentiment.
Saudi Arabia recorded a large numerical decline, but its leading stories concerned plans to raise oil production. Ukraine was also removed because much of its signal came from reporting on Russian refineries damaged by Ukrainian attacks. Neither makes a particularly convincing account of weakening domestic production.
Several other countries lost numerical momentum while retaining predominantly expansionary headlines. A fifth fall would have made the table tidier and the analysis worse.
The UK recorded the largest confirmed decline as vehicle manufacturing returned to the centre of the industrial discussion.
Production remained weak during the first half of the year. Model changes, plant disruption and soft commercial-vehicle demand have all played a part. The precise mixture varies; the result has been more dependable.
Britain has many promising advanced-manufacturing strategies. Its existing car plants must meanwhile continue producing cars.
Germany’s GMSI score fell almost as sharply as Britain’s, although the hard data did not describe an industrial collapse.
Production rose by 0.9% in May and was unchanged from a year earlier. Orders and the backlog also strengthened. The deterioration occurred elsewhere: in the assessment of Germany’s competitive position, the future of its car industry and the willingness of companies to keep investing at home.
The German industrial model has not stopped working. That is a lower hurdle than it used to be.
China’s decline had a firmer cyclical basis.
The official manufacturing PMI fell to 49.2 in July from 50.3 in June, taking activity back below the expansion threshold. Production capacity was not the obvious problem. New demand was.
China has spent years demonstrating how much it can make. The more pressing task is finding buyers at margins producers are willing to accept.
Romania completed the falling group as energy availability became the main industrial constraint.
Lower electricity generation and weaker hydrocarbon output raised concerns over supply through the summer. New factories and future capacity plans still featured in the news. They were less useful to plants needing power now.
Industrial strategy generally sounds grander than grid reliability. The latter still determines whether the machines run.
Leadership within the industrial cycle passed towards the economies closest to physical production.
Canada benefited from extraction and mining investment. India combined stronger energy supply with wider manufacturing growth. Turkey drew momentum from metals. South Korea offered the more encouraging prospect of output, investment and consumption improving at the same time. Italy, cautiously, joined the group through a better pipeline of orders and sales.
The weaker economies arrived there by different routes.
Britain remained burdened by automotive production. Germany’s current output was steadier than its industrial self-confidence. China had ample capacity and less convincing demand. Romania encountered the older and less abstract difficulty of supplying enough power.
This leaves the world with an industrial expansion that is real, but selective. Mines can open, steel output can rise and power generation can improve without producing a broad recovery in manufactured trade or household demand.
The market consequences are equally uneven. Higher resource production can support capital expenditure and commodity supply. It does not guarantee stronger factory employment, consumer spending or export orders.
For now, the heavy industries are finding momentum. The rest of the factory cycle has yet to decide whether to follow.
Methodology: Permutable GMSI directional sentiment for Economic Data-Production Growth-Industrial, combining domestic and international coverage. The ranking compares average sentiment per matched headline in the seven days ending 2 August 2026 with the preceding seven-day period, 20–26 July. Countries required at least 15 matched headlines in both periods. Numerical moves were published only where their direction was supported by the dominant high-impact headlines.
The second quarter began with conflict in the Gulf and disruption through the Strait of Hormuz. It ended under the floodlights of the World Cup. On 29 July, the Federal Reserve held rates at 3.50-3.75%, with three members dissenting in favour of a quarter-point rise, the first estimate of Q2 GDP followed the next morning. In between, crude’s geopolitical premium ebbed, rebuilt and repeatedly changed the inflation picture. Official data fixed the quarter after the event. GMSI tracked the shifts while they were still unfolding.
On the morning of the decision, the Committee had a June CPI report that captured energy prices near their local trough and a quarterly PCE measure that compressed several turns in oil into a single number. The advance GDP estimate was still a day away. The Fed was judging a moving economy through data that had already begun to age.
That is not a defect in official statistics, it is the price of measurement. They settle the record after the period has closed, while policy is made before that record is complete. For a macro desk, the question is what can fill the interval without sacrificing accountability.
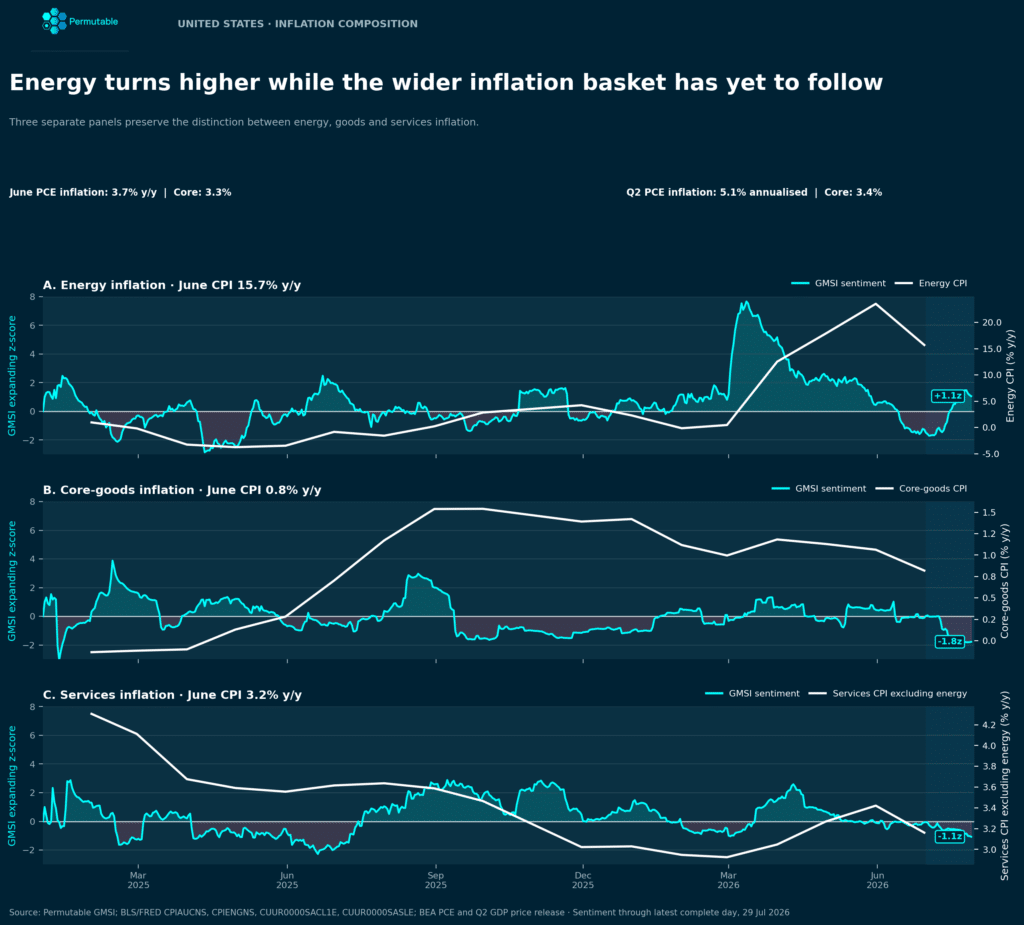
Read that morning, the three charts described a consistent position. Expenditure sentiment sat above its historical baseline, private demand was not cracking. Energy inflation had turned up again, to roughly +1.1 standard deviations. Core goods and services stood below its baseline sentiment level, so the wider basket had yet to follow. Policy sentiment had fallen from an extraordinary late-June peak of nearly +3 to below +1, leaving the hawkish argument narrower than it had been a month earlier but still standing. A hold with three dissents is a reasonable reading of that configuration.

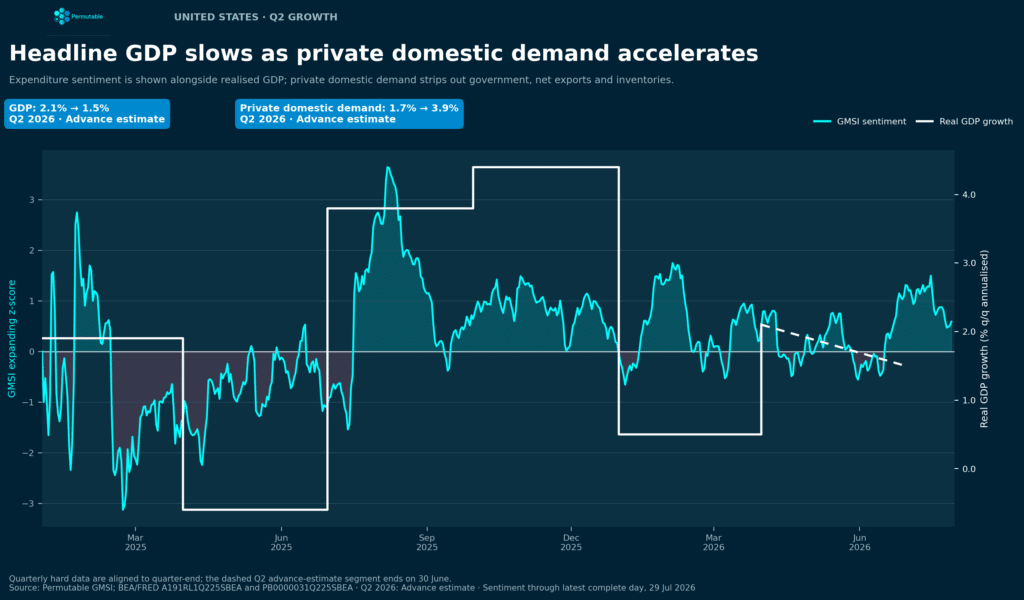
Real GDP grew at an annualised 1.5%, down from 2.1% and below consensus. The composition is worth more than the total. Real final sales to private domestic purchasers, which strip out government spending, inventories and net exports, accelerated from 1.7% to 3.9%. That is the series to watch when asking whether restrictive rates have begun to restrain the private demand most exposed to monetary policy, and it suggests they have not.
Households spent, and fixed investment held firm on equipment, software and computing capacity. The expansion leaned on a narrow group of capital-intensive industries. The drag on the headline came from government expenditure, inventories and the external accounts, which subtract from measured output while carrying a different policy message from cancelled capital plans or retrenching consumers.
The US growth Chart shows expenditure sentiment recovering through the back half of the quarter and holding above baseline into late July. It never described an economy shifting up a gear, and never one heading for contraction. Two quarters can print the same headline and mean opposite things, and the signal was pointing at the composition well before the advance estimate confirmed it.
This leaves the Fed uncomfortable in both directions. Private demand near 4% is difficult to reconcile with an economy that needs to find ways to spur output in other areas, while a 1.5% headline, fading industrial momentum and a concentrated capital cycle provide little justification for raising rates simply because activity remains resilient. On their own the national accounts justify waiting. They say much less about the second question, which is whether July’s energy move remains a relative-price shock or begins to spread.

The energy panel is the record of a quarter that would not settle. The risk premium in energy built as the Gulf conflict threatened the strait, drained away as shipping kept moving and the diplomacy held, and rebuilt through July as tension between Washington and Tehran returned. Each phase was long enough to look like a trend and too short to be one.
June’s CPI caught the trough. Consumer prices fell over the month as energy retreated, and that report offered policymakers evidence of relief just as the series had begun to turn back. By the latest complete observation energy sentiment sits above +1 standard deviation again.
The wider inflation basket has not moved with it. Core-goods sentiment ended near -1.8 and services near -1.1, and the hard data are consistent with that: energy CPI ran at 15.7% year on year in June, against core goods at 0.8% and services at 3.2%. The PCE figures show the same shape, with Q2 headline inflation of 5.1% annualised against a core rate of 3.4%. Core excludes food and energy by construction, and much of that gap reflects energy.
The divergence matters because the Fed does not set policy against crude. An energy shock lifts the headline, squeezes real incomes and unsettles expectations. It becomes a monetary problem when it starts setting the price of things that are not oil. The route is well documented, as fuel and freight reach manufactured goods through transport and imported inputs, and services follow later through airfares, repairs, insurance and hospitality. How much survives the journey depends on contracts, margins, and whether firms expect customers to absorb the pass through of increased costs.
The strength of private demand makes that last condition more likely to bind. A shock arriving into a weak consumer tends to compress margins rather than final prices. When private domestic demand is growing near 4%, firms have more scope to pass the shock on. There is no sign in the panels that they have, and goods and services sentiment may show whether the pressure is broadening before that pass-through becomes visible in the official data.
The first links have turned and the rest have not, which makes the current episode a warning rather than a case for higher rates. September becomes considerably harder to see past a hike if all indicators begin to converge together.

The unchanged range of 3.50-3.75% masks an unusually divided hold, with three members preferring a quarter-point increase. The split reflects the tensions in the other two charts. Growth slowed while private demand strengthened, the headline eased while energy risk returned, and the labour market cooled without deteriorating enough to argue for cuts.
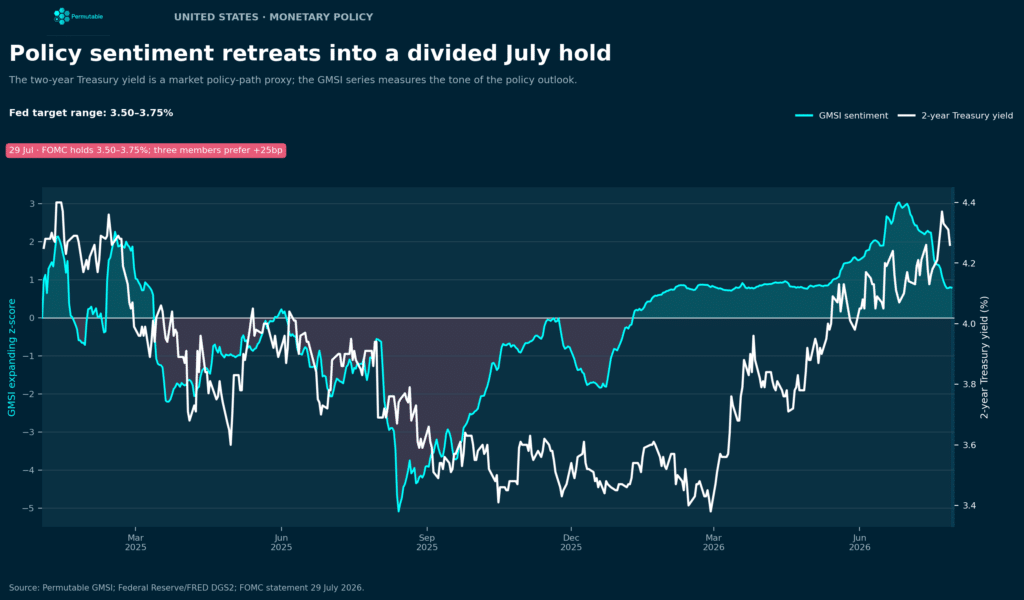
The policy outlook chart tracks how that argument developed. Policy-outlook sentiment climbed through the spring and surged to almost +3 standard deviations in late June, when expensive oil, firm demand and persistent inflation made another increase a central part of the policy debate. The impulse faded before the meeting, and by the latest observation the series had fallen below +1. The two-year Treasury yield stayed elevated throughout.
That difference needs handling with care. Nothing here establishes that sentiment leads the rates market, and the chart is not offered as evidence that it does. It shows that the breadth and volume of the tightening argument declined without a matching move in pricing, which is a positioning question rather than a forecasting one.
In June the hawkish case rested on several arguments at once. By late July it rested largely on one: that a renewed energy shock would eventually reach underlying prices while spending held up. The dissents confirm that another increase is no longer hypothetical, and the retreat in sentiment indicates that the evidence for acting immediately had narrowed. September stays live, with the burden falling on incoming inflation data.
Official statistics settle what happened, and nothing replaces them. GDP fixes the rate and composition of growth, CPI and PCE fix the prices people paid, and the statement fixes the policy delivered. They also arrive after the period has closed and describe it as though it had a single character, which the second quarter did not.
Sentiment addresses the interval those releases leave behind. It is point-in-time, so the June 2025 reading on the chart is the reading a desk saw in June 2025 rather than a restatement, which is the minimum condition for a backtest to mean anything. It is normalised against expanding history, so today’s level is comparable with one from eleven years ago. And it separates by topic, which is why energy, core goods and services can be read against each other rather than averaged into a single index that would have shown little this month.
In this episode that produced three use cases. The energy panel dated the last official inflation print and indicated how much of June’s relief had already expired in July. The goods and services panels gave the question of second-round effects a level and a direction. The policy panel measured the argument surrounding the rates market ahead of a divided decision.
None of this forecasts the next decimal of GDP or claims priority over the yield curve. The real value is within tracking the macro landscape in real time, between the releases. A desk still has to judge how the underlying picture is changing, and it is better to make that judgement with evidence that is point in time, measured and open to testing.
The Fed can wait while those signals remain separated. Its room narrows if they begin to converge: firm private demand, persistent energy pressure, broader inflation sentiment and a renewed hawkish turn in the policy outlook.
The second quarter has closed, but its policy argument has not. The advance estimate provided the first account of growth. The next decision will depend on whether July’s energy shock remains confined to the headline or begins to alter the economy underneath it.
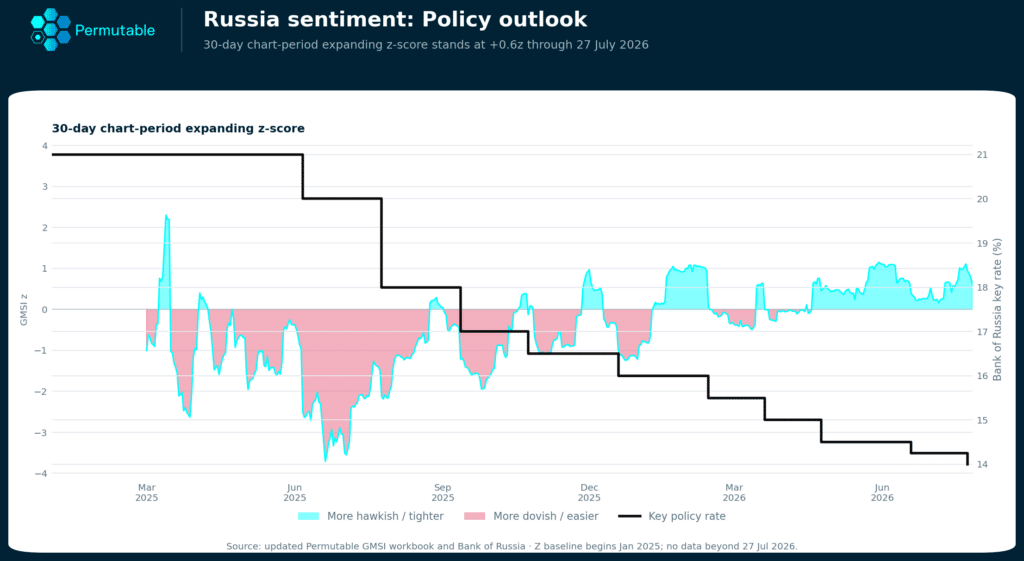
In this article we examine a growing divergence in Russia inflation outlook using the Global Macro Sentiment Indices. The Bank of Russia has cut its key rate substantially since 2025 as price pressures eased. Yet the latest GMSI signals across monetary policy, supply chains and inflation are now moving the other way, pointing to renewed pressure beneath the official disinflation.
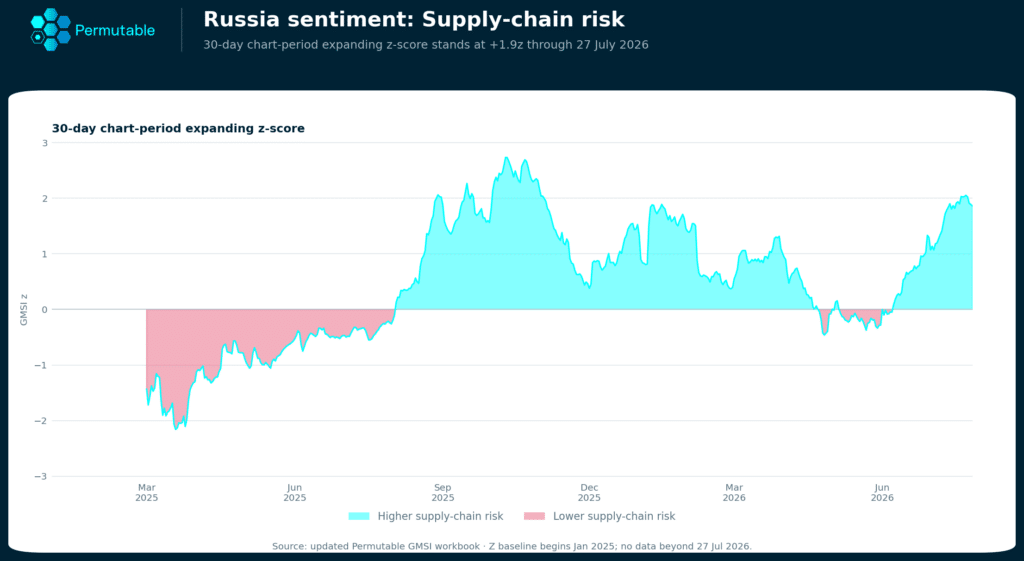
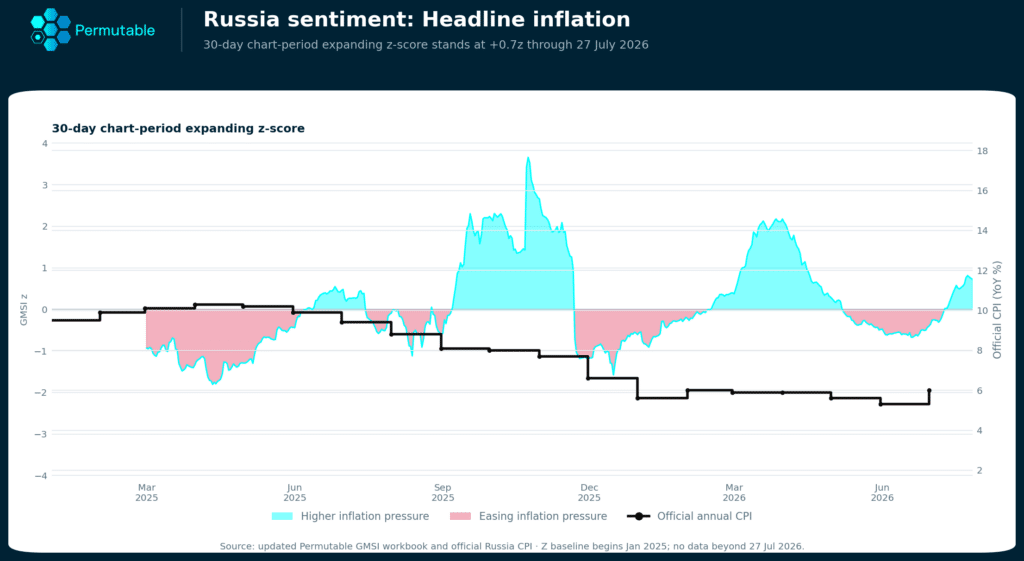
For most of the past eighteen months Russia inflation outlook has been running a disinflation story that looked, until recently, close to completion. Annual inflation fell from above 10% in early 2025 to roughly 5.3% by the beginning of this summer, allowing the central bank to lower its key rate from 21% to 14%.By June, however, inflation was back at 6%. The tide had begun to turn. The four sentiment panels below show how that reversal was already taking shape across monetary policy, supply chains, prices and political tension, leaving the earlier disinflation story looking increasingly fragile.

On the policy-outlook chart, the run of rate cuts appears as a long descending staircase. Yet directional sentiment focused on macroeconomic implication shows that coverage has pivoted the other way, shifting through the first half of 2026 towards the hawkish side of neutral to stand at +0.6z, even as the Bank of Russia has continued to ease. The signal tracks the direction of policy commentary rather than a market instrument, so it is best read as evidence that the expected policy path is becoming tighter while the current rate still falls.
The July decision brought that tension into the open. The central bank lowered the key rate, but raised its inflation forecast, lifted the projected rate path and said further cuts would proceed more slowly, citing inflation expectations, impaired production capacity and a more expansionary fiscal outlook. It also warned that a wider structural deficit could keep policy tighter than its baseline assumes. That matters, because it means the pressure on rates is not only a temporary supply story: fiscal demand is reducing the room to look through the shock.
The pressure runs in the other direction as well. In the run-up to the meeting, businesses squeezed by high borrowing costs pushed for relief, and calls from Moscow had called for further cuts. The Bank is therefore not simply weighing inflation against growth. It is trying to slow its own easing cycle while much of the corporate sector presses for cheaper credit.

The pressure now sits in supply. The supply-chain risk panel has climbed to +1.9z, close to the top of its two-year range, after rising sharply since June. At first, the move reflected attacks on refineries, oil depots and transport routes, alongside fuel shortages and tighter diesel supply. What has changed is where the disruption bites. For much of the war, the economic strain was concentrated in the oil complex. It has now moved closer to the infrastructure of everyday consumption.
Since 18 July, Ukrainian drones have struck warehouse facilities operated by Wildberries, Russia’s largest online retailer. The first attacks hit logistics hubs in Kotovsk and Elektrostal, killing workers and injuring dozens. Further sites were later affected in southern Russia and near St Petersburg. By late July, warehouses representing roughly 10% of the company’s logistics capacity had reportedly been attacked, while separate estimates placed the share potentially out of service nearer 8%.
These are not peripheral targets. Russia’s leading online marketplaces handle goods and services worth the equivalent of roughly 8.5% of GDP and support about four million jobs. They have become part of the country’s consumer infrastructure, particularly in regions where physical retail is thinner. Strikes on refineries raise costs upstream; strikes on warehouses bring the disruption closer to the shelf.
The attacks have also landed on a retail system with limited spare capacity. Russia’s number of physical shops fell over the past year, the first nationwide decline reported in a quarter of a century, with thousands of outlets disappearing from Moscow and St Petersburg. That does not imply national shortages. It does leave fewer alternatives when a major distribution hub is disrupted, particularly outside the largest cities.
The same imbalance is visible in fuel distribution. Supplies have been redirected from Siberia and supplemented with imports from Belarus to stabilise the Moscow region, while shortages have persisted elsewhere. The result is a more uneven geography of disruption-and a growing sense that the economic burden is no longer confined to refineries, ports or the front.

Bottlenecks and constraints on the domestic supply chains are beginning to coincide with renewed price pressure. The headline-inflation sentiment has risen to +0.7z after spending much of the disinflation below neutral, turning before the published series. Annual inflation, having fallen to around 5.5% earlier in the summer, stood closer to 6% by late June.
Much of the pressure predates the warehouse attacks. Inflation was already firming through fuel as repeated strikes on refining infrastructure soured the availability of supply. Reports of shortages and queues at petrol stations became more common palace in parts of the country. Petrol prices rose by 6.88% m-o-m in June, while diesel costs also increased during the agricultural season, with farmers being particularly worse off and having limited scope to reduce consumption.
The Bank of Russia has acknowledged that higher fuel costs are spreading into a broader range of goods and services, prompting it to raise its 2026 inflation forecast to 6–7%. Its assessment remains measured: much of the increase is considered temporary, underlying inflation is put at 4-5%, and weaker demand is expected to limit further pass-through. Fuel, fruit and vegetables have accounted for much of the recent volatility, reflecting both seasonal supply conditions and the higher cost of transporting perishable goods quickly through the distribution network. The inflation outlook is becoming increasingly uneven as the pressure is no longer confined to a single category.

The attacks on warehouses form one part of a wider rise in the domestic economic cost of the war. The political-tension panel remains close to the top of its two-year range, although the recent increase is not driven by logistics alone. The underlying coverage extends to mobilisation and preparations for possible unrest, disputes over wage arrears and staff shortages, public dissatisfaction and reported friction within the political system.
The panel is shown as a rolling sentiment sum rather than a standardised score because the signal has remained elevated for so long that z-scoring compresses the change that matters. At around 2,640, it remains well above the levels recorded in early 2025, even after easing from its June peak.
The reading comes with one caveat: much of the late-July coverage is international reporting on these themes rather than a direct measure of Russian public reaction. Its political significance lies less in any single headline than in the growing visibility of the war’s social cost. Fuel shortages, transport disruption, delayed wages and the prospect of further mobilisation are becoming harder to contain within the economic sphere alone.
The Central Bank had good reason to continue cutting. Inflation had fallen materially, domestic demand was weakening and business expectations for output had softened. Lending growth had slowed to a crawl, consumer-facing firms were under pressure and high borrowing costs were suppressing discretionary spending.
The forces now pushing in the opposite direction are largely supply-driven: damaged refining capacity, more expensive transport and disruption to the distribution of consumer goods. Interest rates cannot repair a refinery or replace a warehouse. But cutting too quickly while those shocks feed into expectations risks turning a temporary rise in prices into persistent inflationary pressure. Households’ own expectations tell the story, perceived inflation rose to 14.7% in July from 12.4% in June, far above the Bank’s revised forecast of 6-7%.
Keeping policy restrictive carries costs of its own. Credit conditions remain tight, businesses are pressing for cheaper borrowing and consumer-facing activity is weakening. At the same time, a more expansionary budget as the conflict persists would leave monetary policy carrying a greater share of the burden.
Where the government and central bank go next will depend in part on whether strikes against refineries and warehouses continue. Damaged capacity creates immediate disruption, but much of it can eventually be rebuilt. The greater risk is that a prolonged deterioration in supply chains pushes costs further into services and hardens wage demands. That would be far more difficult to reverse. The first signs of renewed price pressure have therefore left the Bank in an increasingly precarious position, with its tolerance for further inflation likely to be tested at the next meeting.
Read through the official data alone, Russia in mid-2026 appears to be an economy in which disinflation has progressed far enough to permit lower interest rates. The point in time sentiment from the GMSI offers a less settled reading. The decline in inflation was genuine, but it is meeting a fresh round of supply pressure just as the central bank has begun to ease. The first shock came through fuel and refining capacity and has spread into freight, food and services, while the attacks on major warehouses have exposed the vulnerability of the consumer-distribution network. None of this yet amounts to a return to the inflation regime of 2024 or early 2025. It does make the final stage of disinflation harder, and the next rate cut less straightforward.
This analysis powered by Permutable’s Global Macro Sentiment Indices examines where energy inflation pressure is intensifying as oil disruption, currency weakness and higher import costs move into domestic economies. It compares Saudi Arabia, Chile, Indonesia, Mexico and Japan, while explaining why no confirmed declines were published. It is aimed at investors, economists, policymakers, risk teams and commodity or macro strategists tracking inflation transmission across markets.
Energy inflation sentiment rose most sharply in Saudi Arabia, Chile and Indonesia as disruption around Saudi oil routes pushed crude prices higher and began feeding into fuel, import and fiscal pressures elsewhere. Mexico and Japan completed the five confirmed rises. No country passed the full evidence test for a weekly fall: although several numerical averages declined, their dominant headlines continued to describe rising energy costs.
Permutable’s latest Global Macro Sentiment Indices rankings capture the point at which higher oil prices began to move beyond global commodity markets and into country-level inflation concerns.
Saudi Arabia recorded the largest weekly increase. The signal was driven by threats to Red Sea ports, attacks on Saudi-linked tankers and the risk that shipping disruption could constrain global supply. This is primarily a Saudi-associated oil-market signal rather than evidence of an equivalent increase in Saudi household energy prices.
The transmission was more direct elsewhere. Chilean coverage moved towards imminent increases in petrol and diesel prices. In Japan, higher crude prices and a weak yen lifted the import bill and electricity costs. Indonesia’s signal strengthened through the fiscal cost of more expensive oil and the effect of higher non-subsidised fuel prices. Mexican headlines increasingly connected stronger oil benchmarks with domestic petrol costs.
The common driver was the same, but the mechanism differed: physical supply risk in Saudi Arabia, pump-price pass-through in Chile and Mexico, import-cost inflation in Japan, and subsidy and budget pressure in Indonesia.
The rankings compare 20–26 July 2026 with 13–19 July 2026 using the canonical GMSI topic Economic Data-Inflation–Energy.
A rise means that average directional sentiment per matched headline moved towards stronger energy-price pressure. This may include higher oil, gas, electricity or fuel prices, as well as evidence that those costs are passing into consumer inflation, imports, public finances or business expenses.
A fall requires headline evidence of moderating energy prices or weaker inflation pass-through. A lower numerical average is not sufficient when the dominant stories still describe rising costs.
Domestic and international coverage are combined. Sentiment is divided by matched headline count in each seven-day period so countries with larger news volumes do not dominate the comparison.
For energy exporters, the signal may reflect supply disruption and international price pressure associated with the country rather than domestic consumer-price inflation alone.
| Rank | Country | 13–19 July | 20–26 July | Weekly change |
| 1 | Saudi Arabia | −0.004 | +0.609 | +0.613 |
| 2 | Chile | −0.016 | +0.268 | +0.284 |
| 3 | Indonesia | −0.108 | +0.104 | +0.211 |
| 4 | Mexico | +0.150 | +0.277 | +0.127 |
| 5 | Japan | +0.310 | +0.423 | +0.114 |
Average directional sentiment per matched headline. A higher value indicates stronger energy inflation pressure.
Saudi Arabia’s signal moved from broadly balanced to strongly inflationary as the threat to regional oil infrastructure became more concrete. The focus shifted from general Middle East tension towards port disruption, tanker attacks and the possibility of a sustained premium in global oil prices.
The ranking reflects Saudi Arabia’s central position in the global oil-supply system. The immediate inflation mechanism runs through international crude and transport costs, with the effects then transmitted to energy-importing economies.
Chile’s energy inflation signal turned decisively higher as global oil gains began to feed into expectations for domestic petrol and diesel prices. Coverage moved from earlier reports of relatively low fuel costs towards specific warnings of increases from the end of July.
Chile’s move is one of the clearest cases of external energy pressure approaching domestic inflation. The mechanism operates through both the oil benchmark and the exchange rate.
Indonesia moved from negative to positive energy inflation sentiment as the discussion shifted towards the budgetary and consumer consequences of higher oil prices. The strongest stories focused less on the commodity price itself than on who would absorb the increase.
Indonesia’s signal is therefore not limited to headline inflation. The pressure is being transmitted through subsidies, government spending choices and the relative cost of conventional transport.
Mexico’s energy inflation signal strengthened as higher crude benchmarks were joined by reports of rising domestic petrol prices. As an oil producer and fuel consumer, Mexico experiences the shock through both export revenues and household costs.
The Mexican story is not simply that the country benefits from expensive oil. The downstream effect depends on refining capacity, fuel imports and the extent to which retail prices are absorbed by government, producers or consumers.
Japan’s already elevated energy inflation signal rose further as higher crude prices combined with currency weakness. The country’s dependence on imported energy makes this one of the most direct transmission channels in the ranking.
Japan’s ranking illustrates the interaction between commodities and foreign exchange. Even where the global oil move is shared, a weaker currency can materially increase the inflationary effect.
No country passed the full evidence test for a confirmed decline in energy inflation sentiment this week.
The five largest numerical falls were:
| Numerical rank | Country | 13–19 July | 20–26 July | Weekly change | Evidence verdict |
| 1 | United Kingdom | +0.461 | −0.071 | −0.532 | Excluded |
| 2 | Canada | +0.368 | +0.004 | −0.364 | Excluded |
| 3 | France | +0.470 | +0.165 | −0.304 | Excluded |
| 4 | Hungary | +0.385 | +0.175 | −0.210 | Excluded |
| 5 | South Africa | +0.179 | +0.006 | −0.173 | Excluded |
These countries are not treated as confirmed falls because their dominant high-impact headlines continued to point towards stronger energy-price pressure:
The numerical declines may reflect changes in the wider distribution of matched headlines, but they do not provide sufficiently coherent evidence of easing energy inflation pressure. They are therefore excluded from the confirmed ranking.
The energy inflation story became more geographically specific. During the preceding week, much of the coverage centred on the general rise in oil prices following escalating Middle East tensions. Between 20 and 26 July, that broad shock developed into a series of more defined transmission channels.
Saudi Arabia became the centre of the global supply-risk story as attacks on tankers and threats to Red Sea ports raised concerns about physical delivery. Chilean and Mexican coverage moved closer to the consumer, with specific reports of petrol-price increases. Japan’s import data showed how higher oil and a weaker currency were combining to raise the domestic cost of energy. In Indonesia, the shock appeared through the public finances and the cost of maintaining fuel support.
The absence of confirmed falls is equally important. Some country averages declined, but the underlying news flow remained dominated by higher oil, gas, fuel and electricity prices. This was therefore not a week in which energy inflation pressure split evenly between countries. The strongest evidence continued to point in one direction, even where the numerical intensity of the signal softened.
The result is a ranking led by countries closest to one of three mechanisms: disruption to oil supply, reliance on imported energy, or direct pass-through into fuel prices and public finances.
This edition covers the canonical GMSI topic Economic Data–Inflation–Energy, which includes oil, gas, electricity and fuel-price inflation, together with their economic and consumer-price pass-through.
The latest observation period is 20–26 July 2026, compared with 13–19 July 2026. The analysis uses:
The ranking is based on weekly change rather than the absolute level of energy inflation sentiment.
Countries are included only when:
Where a numerical fall is not supported by the underlying headline mix, the country is excluded rather than used to fill the ranking mechanically.
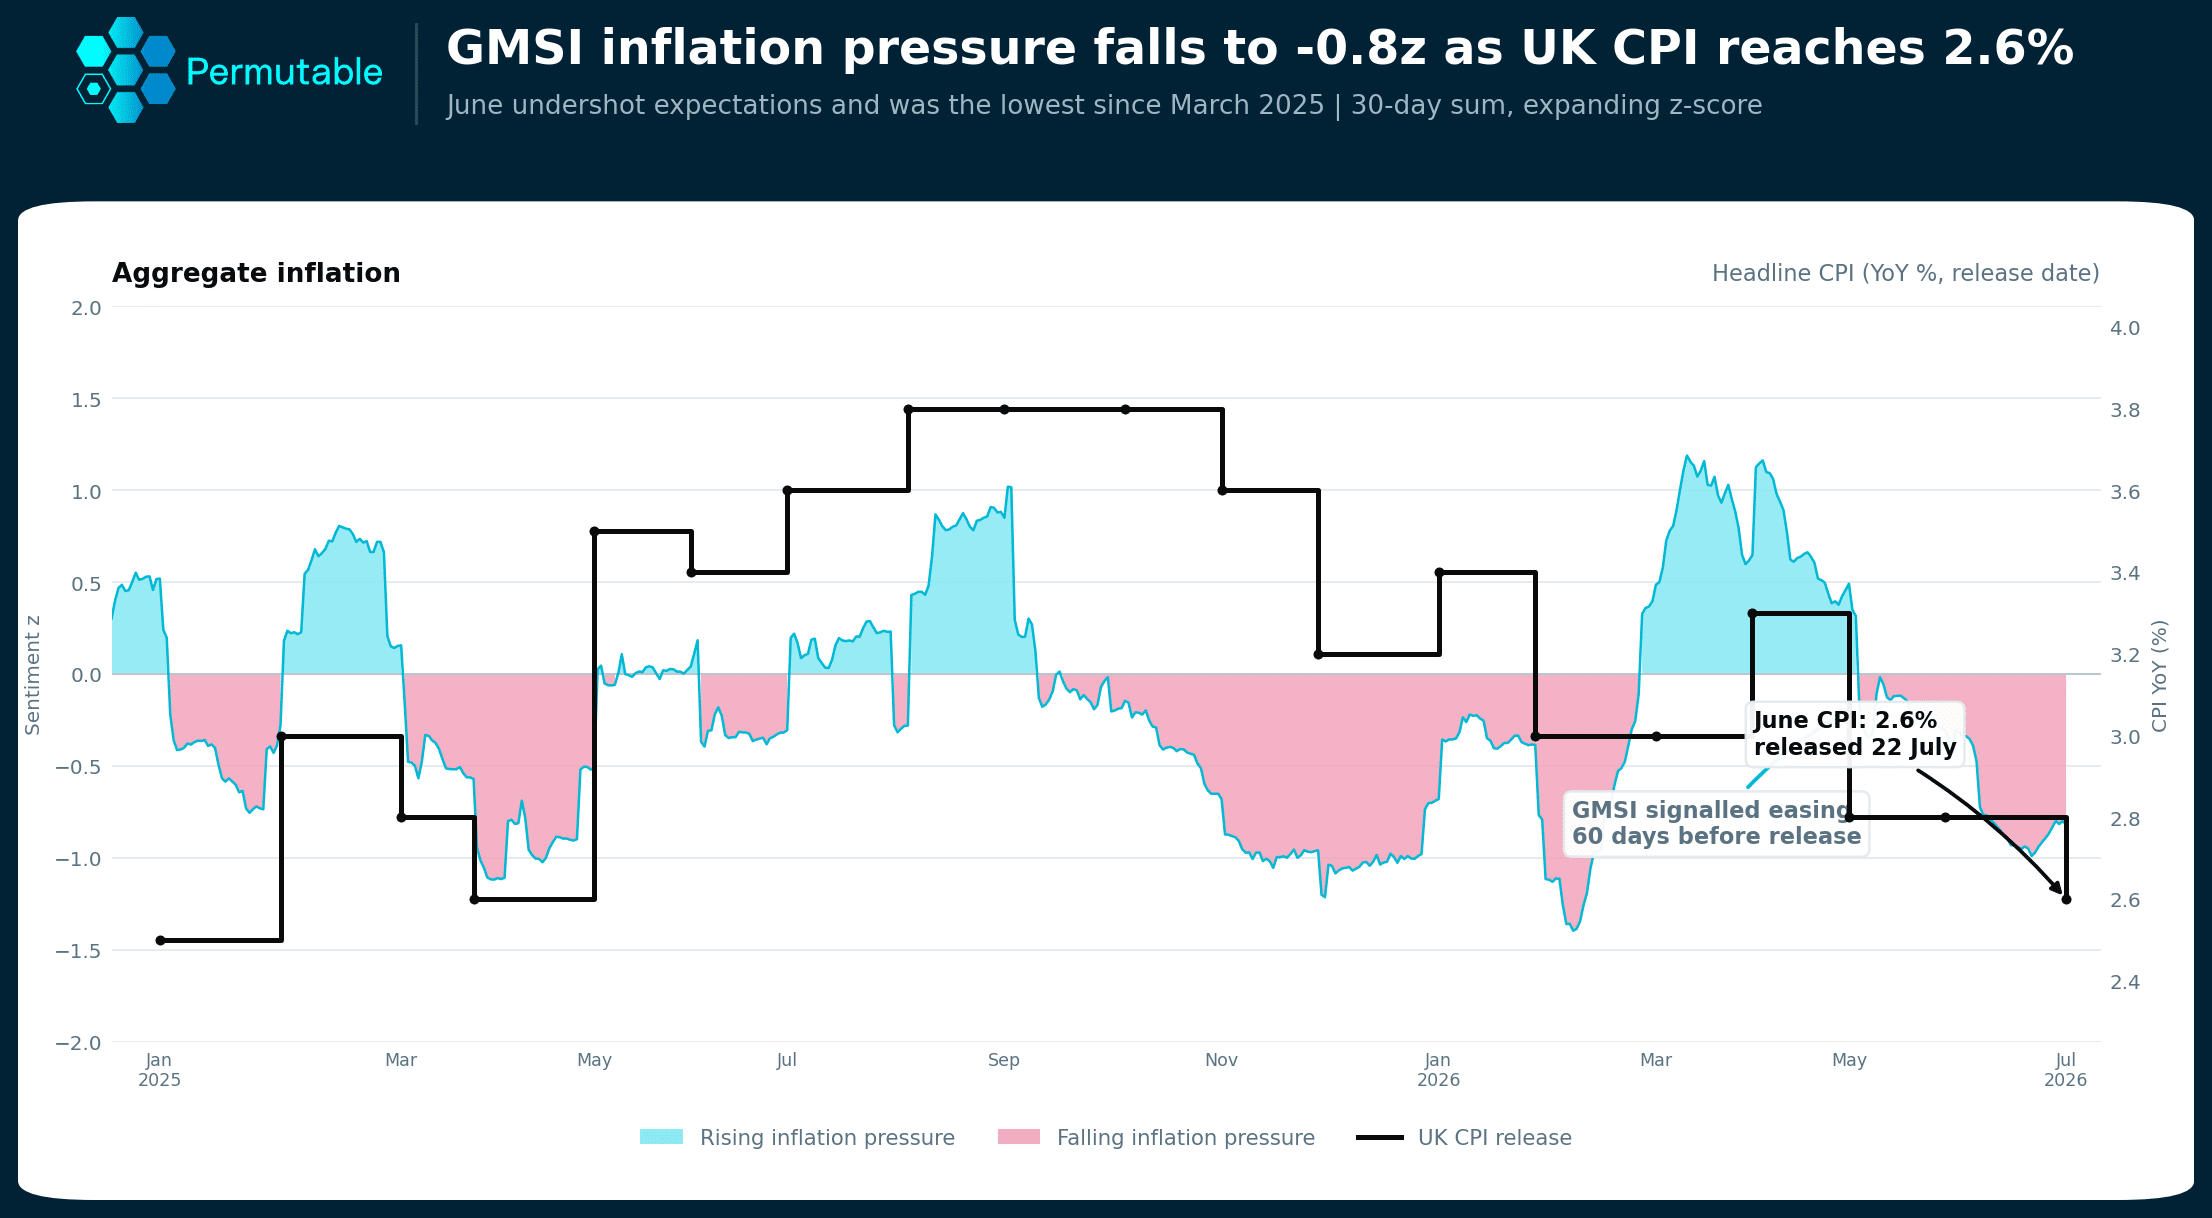
This analysis explains how Permutable’s Global Macro Sentiment Indices identified falling UK inflation pressure before the June CPI release confirmed the slowdown. It is aimed at macro strategists, rates traders, economists, quantitative researchers and investment teams seeking earlier, point-in-time signals to complement official data, improve market timing and support discretionary or systematic inflation research across UK rates and currency markets.
Permutable’s Global Macro Sentiment Index was reading falling UK inflation pressure long before the official figures caught up. When the June print landed on 22 July, headline inflation had eased to 2.6%. Aggregate sentiment now sits well into negative territory, a sharp turn from the +1.2z peak it reached in early spring, when energy sentiment spiked alongside the US-Iran conflict.

The chart tells the story in two colours. The cyan reading, rising inflation pressure, built through February and March, topped out just above one standard deviation, then rolled over. By May it had given way to light red, falling pressure, and has stayed there since. The CPI release, the black step line against the right axis, only caught up on 22 July, when the June figure printed at 2.6%. GMSI had turned negative a full two months before that.
The print came in below consensus, the lowest reading since March 2025. Cheaper food did most of the work, helped by summer clothing discounts that cut deeper than last year’s. Motor fuels made the single biggest downward contribution: pump prices fell as an earlier Middle East truce took the heat out of supply. Food and drink inflation cooled to 1.7%, its softest since August 2024, with sugar, jam, syrups and confectionery leading the way down.
Official inflation data is necessarily backward-looking. The June CPI figure described price changes that had already occurred and was not published until 22 July.
GMSI provides a different information layer. It structures macroeconomic reporting and commentary by:
Permutable’s Global Macro Sentiment Indices are updated hourly and are designed to provide historical and live inputs that institutional teams can transform, normalise and test within their own research processes. GMSI is a raw feature layer rather than a completed trading strategy or official inflation forecast.
For discretionary teams, the UK series can help identify the narratives driving a change in inflation pressure. For systematic teams, the same data can be used to construct and test features against rates, currencies, inflation markets or other economically relevant variables.
The value is not that every change will predict the next CPI figure. It is that the information flow can be measured before the corresponding official data is released.
The UK inflation outlook remains exposed to a renewed increase in energy costs.
Ofgem raised the energy price cap by 13% from 1 July to 30 September 2026, increasing the illustrative annual bill for a typical direct-debit household to £1,862. Because the change took effect after the June measurement period, its direct impact will begin to appear in subsequent inflation releases.
Energy-market risks have also increased again. Brent crude traded above $95 per barrel on 22 July as conflict in the Middle East intensified. Any assessment of the future inflation impact should distinguish between a temporary market spike and a sustained increase that passes through to fuel, transport, production and food costs.
The Bank of England’s next monetary-policy decision is scheduled for 30 July 2026. Bank Rate currently stands at 3.75%, while the Bank’s inflation target remains 2%.
As of 22 July, the GMSI aggregate signal remained at −0.8z and continued to indicate falling inflation pressure. It was not yet showing the broad build in rising pressure that would confirm a new inflationary regime.
The signals to monitor next are:
The chart should state the precise construction of the displayed GMSI feature, including:
GMSI measures the direction and intensity of macroeconomic narratives. It does not directly measure consumer prices, guarantee a lead over official data or constitute an investment recommendation.
Find out how Permutable’s point-in-time macro signals could support your institution’s research, trading, risk or portfolio workflows, and explore access to sample data for evaluation. Get in touch with our team to discuss your use case.
This report analyses why China’s 4.3% Q2 2026 growth masks a widening imbalance between resilient industrial output and weakening domestic demand. Using Permutable’s Global Macro Sentiment Indices, it examines expenditure, property, inflation, trade and industrial momentum. It is aimed at investors, economists, strategists, risk teams and institutions monitoring China’s growth outlook and cross-market implications across global portfolios and policy-sensitive markets.
China’s second-quarter data revealed an economy increasingly divided between its capacity to produce and its ability to generate demand at home.
GDP growth slowed to 4.3% year on year in the second quarter, leaving first-half growth at 4.7%. Industrial output remained comparatively resilient, while exports accelerated sharply in June. Domestic indicators were markedly weaker: retail sales increased only modestly, private investment contracted and property investment remained deeply negative.
Permutable’s Global Macro Sentiment Indices, or GMSI, show how this divergence developed across expenditure, housing, inflation, trade and industrial activity.
The signals do not attempt to predict the precise number attached to an official economic release. They structure the information surrounding each economic topic to show where pressure is building, where momentum is weakening and how changes are transmitting through the economy.
China has not run short of goods to produce. Its difficulty lies in finding enough domestic buyers willing or able to absorb those goods at the same pace.
Permutable’s expenditure-growth sentiment signal deteriorated rapidly during the second quarter, falling to −1.7 standard deviations by 16 July. The decline placed the weakness primarily in spending and investment rather than in productive capacity.
Official data reflected the same imbalance. Retail sales returned to growth in June, but the improvement was insufficient to reverse the broader weakness across the first half. Private investment contracted more sharply than aggregate investment, while industrial production continued to expand.
One stronger month of consumption does not resolve the underlying pressure created by falling property values, uncertain income expectations and precautionary saving.

Property remains central to the transmission of credit, income and confidence through the Chinese economy.
Housing activity supports local-government revenue, construction employment, demand for materials and household wealth. When that channel weakens, the effect extends well beyond developers and housebuilding.
Permutable’s housing-activity sentiment signal staged a tentative revival during spring 2026, but the improvement faded back towards neutral. At the same time, new-home sales and property investment remained firmly negative.
Stabilisation may slow the decline, but it does not yet represent a durable recovery. Until households become more confident about the value of their largest asset, the incentive to save rather than spend is likely to remain powerful.

China’s price data provide another expression of the domestic-demand weakness.
The report shows input and producer-price pressure rising more quickly than consumer inflation. Imported energy and raw-material costs entered the industrial economy, but weak household demand limited companies’ ability to pass those costs through to consumers.
Permutable’s inflation sentiment climbed to +2.9 standard deviations in April as energy and producer-price pressure intensified. It subsequently reversed below neutral, indicating that the original cost shock had not developed into broad domestic reflation.
The result is a margin squeeze rather than a conventional consumer-inflation cycle, with smaller private firms particularly exposed.
China’s export performance has absorbed some of the production that the domestic economy could not.
Mechanical and electrical goods accounted for a large share of shipments, supported by overseas demand for semiconductors, computing equipment and advanced machinery.
However, Permutable’s trade-activity sentiment signal weakened substantially even as the official export figures accelerated. The signal declined from +3.8 standard deviations in January to approximately neutral.
This divergence matters because reported customs figures reflect goods that have already been produced and shipped. The sentiment signal captures the developing information environment around future orders, trading conditions, tariffs and policy risk.
Some demand may also have been brought forward, supporting current exports at the expense of later quarters. Exports therefore provide a release valve for excess production, but they do not rebuild household confidence or domestic consumption.

Industrial production remained the strongest part of China’s activity data through the first half of the year.
High-technology manufacturing, equipment production, batteries, industrial robots and advanced manufacturing equipment continued to grow rapidly.
Yet Permutable’s 90-day industrial sentiment signal weakened to −0.2 standard deviations by mid-July. Current output remained firm, but the information environment surrounding future industrial conditions became less supportive.
China’s factories do not need to enter outright contraction for the wider growth model to weaken. They need only lose enough momentum that industry and exports can no longer compensate for the weakness already present in property, household spending and private investment.
Three signals should indicate whether China’s imbalance is beginning to ease or spread:
If both stabilise near neutral, the external buffer may continue to support growth. If they follow expenditure sentiment more deeply into negative territory, the slowdown is spreading into the sectors that previously contained it.
A recovery that remains above neutral would provide early evidence that the property channel is beginning to reopen. Another short-lived rebound would suggest that stabilisation has not yet become recovery.
A durable move back through its historical norm would be the clearest sign that productive activity is translating into household spending and domestic investment again.
Permutable’s base case in the report is a further gradual loss of momentum, with growth moving towards 4% by year-end unless the policy mix shifts more decisively towards households.
Each signal aggregates the relevant GMSI topic-level sentiment over a rolling window. A 45-day window is used for expenditure, housing, inflation and trade, while the slower-moving industrial signal uses a 90-day window.
Values are standardised using an expanding, no-look-ahead z-score calculated only from information available at each historical date. A reading of +1σ or −1σ indicates that the signal is one standard deviation above or below its own historical norm at that point.
The signals are used in this analysis for coincident monitoring, sequencing and comparison with official data. They are not presented as statistically identified leading indicators or standalone trading recommendations.
Access the complete nine-page analysis, including the expenditure, property, inflation, trade and industrial sentiment charts, methodology and second-half outlook.